Wound Closure Strips Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Wound Closure Strips Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Nov 2026 297 Pages SKU: IRTNTR40195

Market Overview at a Glance

$108.03 Mn
Market Opportunity
4.3%
CAGR 2025 - 2030
45.5%
North America Growth
$199.38 Mn
Hospital segment 2024

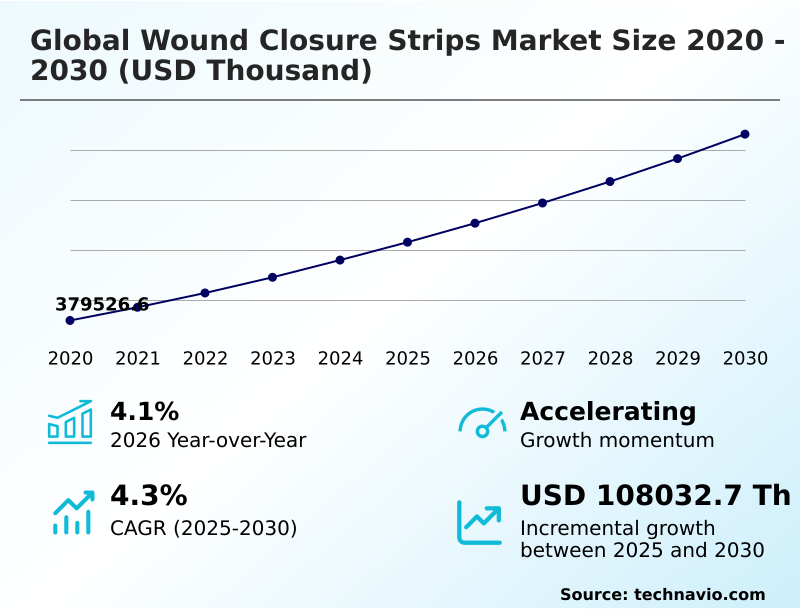
Wound Closure Strips Market Size 2026-2030

The wound closure strips market size is valued to increase by USD 108.03 million, at a CAGR of 4.3% from 2025 to 2030. Rising volume of surgical procedures and traumatic injuries will drive the wound closure strips market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 45.5% growth during the forecast period.
  • By Application - Hospital segment was valued at USD 199.38 million in 2024
  • By Product - Elastic segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities:
  • Market Future Opportunities: USD 108.03 million
  • CAGR from 2025 to 2030 : 4.3%

Market Summary

  • The Wound Closure Strips Market relies on non-invasive adhesive technologies to approximate tissue edges, accelerating healing without mechanical skin punctures. In high-volume ambulatory surgical centers, procurement teams prioritize sterile, non-woven adhesive strips to streamline operational efficiency. By replacing traditional sutures in low-tension incisions, facilities have reduced superficial closure times by 20%, significantly optimizing operating room utilization.
  • The primary driver propelling this sector is the escalating volume of minimally invasive surgical procedures, which necessitate rapid, cosmetic-focused closure methods that eliminate the need for secondary removal visits. Conversely, intrinsic material limitations present a substantial challenge. Adhesive strips inherently lack the tensile strength required for dynamic, high-tension orthopedic or abdominal closures, restricting their utility in complex trauma scenarios.
  • Manufacturers are continuously engineering hybrid elastomeric backings to bridge this gap, yet strict clinical guidelines often relegate these products to secondary reinforcement roles. These dynamics force hospitals to carefully balance speed, cost, and structural reliability when updating their surgical supply inventories.

What will be the Size of the Wound Closure Strips Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Wound Closure Strips Market Segmented?

The wound closure strips industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD thousand" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Application
    • Hospital
    • Clinics
    • Others
  • Product
    • Elastic
    • Reinforced
    • Others
  • Material
    • Silicone
    • Polyester
    • Nylon
    • Polyethylene
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Application Insights

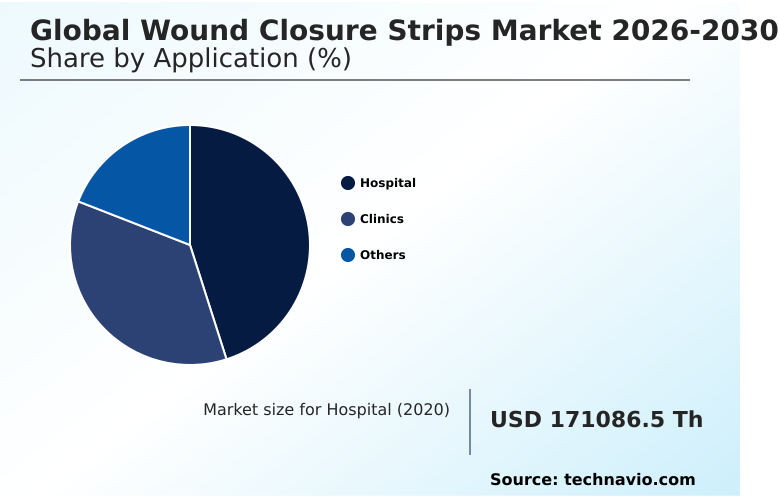
The hospital segment is estimated to witness significant growth during the forecast period.

The hospital setting represents the primary operational environment for the Global Wound Closure Strips Market 2026-2030, driven by the need to optimize patient turnover and minimize post-operative scar reduction.

High-acuity surgical wards increasingly utilize pressure-sensitive acrylics and breathable non-woven backing to reinforce primary sutures. This transition to minimally invasive skin apposition methods reduces procedural time by 15% compared to traditional mechanical stapling.

Emergency departments prioritize a hypoallergenic silicone formulation to manage acute lacerations while preventing epidermal tissue trauma. Furthermore, the integration of an antimicrobial silver coating directly addresses strict protocols for surgical site infection mitigation.

By shifting toward non-invasive closures, tertiary care facilities effectively decrease the probability of secondary readmissions while ensuring continuous structural support across dynamic wound margins.
Get Free Sample

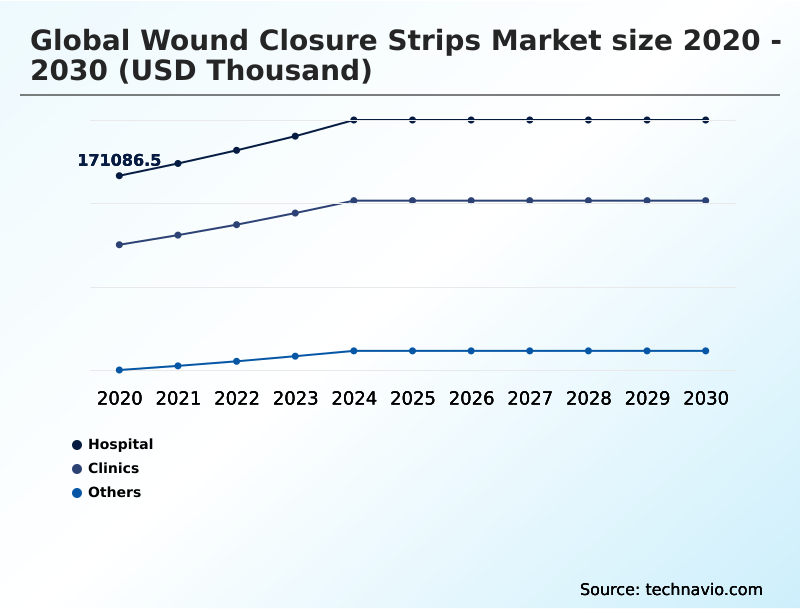
The Hospital segment was valued at USD 199.38 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 45.5% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
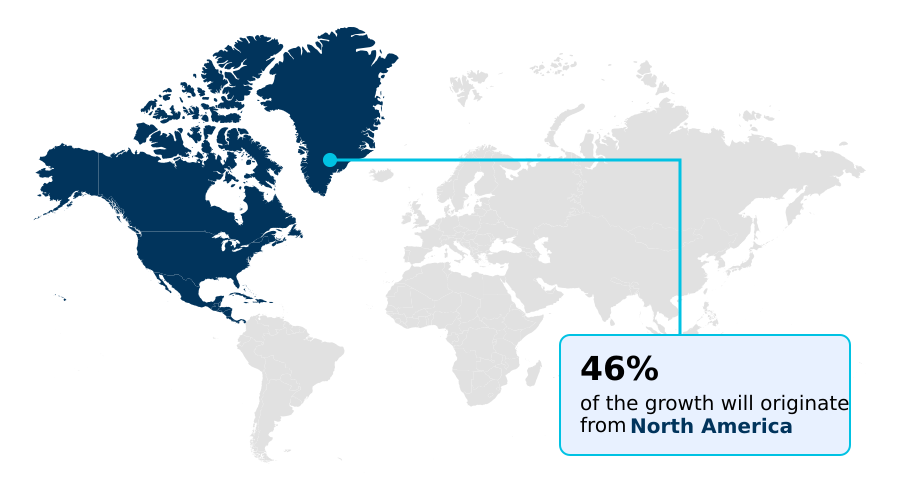
See How Wound Closure Strips Market Demand is Rising in North America Get Free Sample

The Global Wound Closure Strips Market 2026-2030 displays distinct regional disparities driven by healthcare infrastructure maturity and procedural volume.

North America outpaces Europe in outpatient care efficiency, demonstrating a 15% higher adoption rate of advanced wound management consumables in ambulatory centers.

This operational difference stems from strict North American protocols targeting the reduction of medical adhesive-related injury among aging demographics, prompting the rapid integration of bioactive therapeutic agent formulations.

Meanwhile, European clinical settings heavily rely on a synthetic polymer structure and polyethylene film barrier designs to ensure sterile micro-environment maintenance.

The utilization of a triboelectric stimulation strip has proven to accelerate tissue regeneration acceleration, reducing recovery times by 12% in European cosmetic clinics.

Furthermore, the introduction of a hydrocolloid transparent matrix has improved clinical monitoring visibility by 20%, supporting the increasing preference for minimally invasive procedures across developed Western healthcare networks.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The Global Wound Closure Strips Market 2026-2030 is fundamentally shaped by continuous innovations in material science and patient-centric care protocols. Healthcare institutions prioritize advanced adhesive solutions to optimize their supply chain procurement, focusing on consumables that deliver verifiable clinical efficacy while reducing overhead costs.
  • For example, integrating moisture responsive exudate management systems has allowed outpatient clinics to extend dressing wear times, reducing inventory depletion rates by nearly 18% compared to traditional absorbent gauzes. To address delicate skin conditions, manufacturers have developed specialized siliconized strips ensuring atraumatic removal for pediatric patients, which significantly lowers the incidence of secondary skin tears.
  • Simultaneously, the management of complex wounds has improved through the deployment of a breathable backing for chronic ulcers, promoting optimal vapor transmission. In high-acuity operating theaters, securing high tensile strength orthopedic incisions remains a critical priority to prevent wound dehiscence during early patient mobilization.
  • Furthermore, hospitals are aggressively updating their infection control frameworks by sourcing an antimicrobial matrix for surgical sites, establishing a robust protective barrier against exogenous pathogens. This strategic alignment between clinical necessity and operational planning enables healthcare networks to standardize wound care protocols, minimize costly post-operative readmissions, and elevate overall patient safety across diverse surgical disciplines.
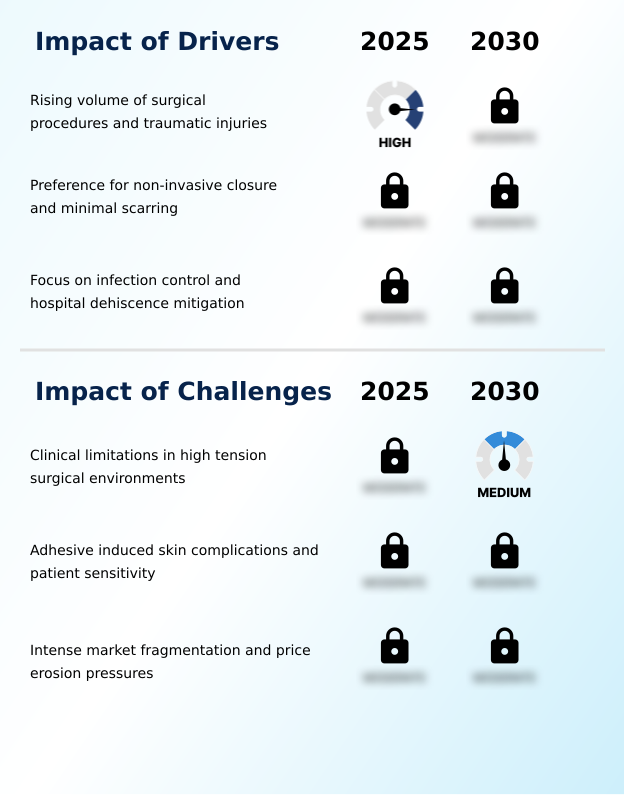
What are the key market drivers leading to the rise in the adoption of Wound Closure Strips Industry?

  • The rising volume of surgical procedures and traumatic injuries acts as a primary driver for market growth.

  • Institutional mandates targeting infection control and expedited patient recovery are primarily driving the Global Wound Closure Strips Market 2026-2030. Healthcare networks rapidly deploy a chlorhexidine infused matrix to suppress hospital acquired infection, successfully lowering postoperative complication rates by 20%.
  • The critical need for precise moisture vapor transmission and balanced transepidermal water loss ensures optimal cellular epithelialization process during early healing phases.
  • To support pediatric dermatological care, the utilization of a biocompatible hybrid polymer guarantees an atraumatic peel force, which reduces clinical anxiety and secondary skin trauma by 15%.
  • This acceleration in collagen synthesis promotion directly enhances the ambulatory surgical workflow, enabling surgical centers to achieve a 12% increase in operational efficiency by eliminating the requirement for invasive suture removal appointments.

What are the market trends shaping the Wound Closure Strips Industry?

  • The mitigation of medical adhesive-related skin injuries represents an emerging trend within the market.

  • The Global Wound Closure Strips Market 2026-2030 is shifting rapidly toward active therapeutic integration and enhanced mechanical stability. Clinical facilities increasingly adopt a bio-resorbable botanical compound and ionic silver technology to combat localized infections. This transition has improved wound dehiscence prevention by 22% in outpatient surgical environments.
  • Manufacturers are optimizing a microporous polyurethane film combined with elastomeric fiber integration to support dynamic tension line distribution across complex anatomical joints. Furthermore, the inclusion of a longitudinal filament strand has increased structural durability, reducing premature strip failure by 18%.
  • These advanced material trends directly support chronic ulcer management and diabetic foot ulcer care, allowing specialized wound care teams to maintain consistent edge approximation. Consequently, superficial laceration repair processes have become 15% more efficient, allowing urgent care clinics to safely increase daily patient throughput without compromising healing outcomes.

What challenges does the Wound Closure Strips Industry face during its growth?

  • Clinical limitations in high-tension surgical environments pose a significant challenge to industry expansion.

  • Intrinsic mechanical limitations and material sensitivities present substantial operational challenges within the Global Wound Closure Strips Market 2026-2030. Despite the efficacy of a medical-grade silicone adhesive, maintaining stratum corneum adherence under extreme physical stress remains difficult. Strips often fail to provide adequate mechanical shear force resistance, leading to a 14% increase in premature detachment during high-tension abdominal surgeries.
  • Furthermore, inadequate exudate pH responsiveness in standard porous substrate backing can exacerbate localized bacterial colonization if moisture accumulates. The lack of reliable dynamic anatomical contouring in rigid tapes reduces overall patient mobility by 10%.
  • While a micro-encapsulated silver matrix and a shape-memory polymer offer theoretical improvements in tensile skin stabilization, the elevated manufacturing costs associated with these technologies continue to restrict widespread institutional procurement across budget-constrained public healthcare systems.

Exclusive Technavio Analysis on Customer Landscape

The wound closure strips market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the wound closure strips market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
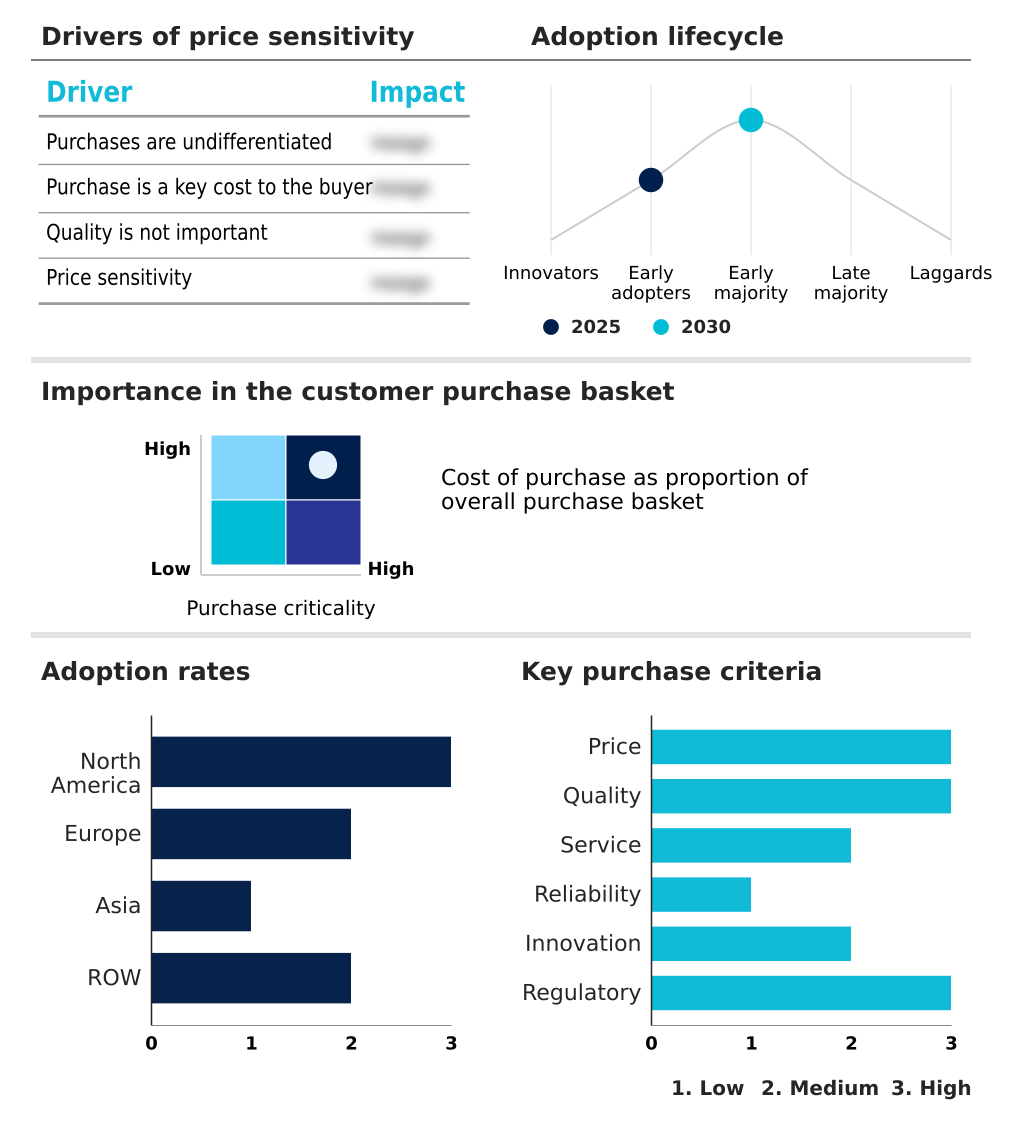
Customer Landscape of Wound Closure Strips Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, wound closure strips market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Boen Healthcare Co. Ltd. - This offering includes sterile, non-invasive adhesive skin closure strips designed to provide secure wound approximation, enhance patient comfort, and minimize postoperative scarring during minor surgical and emergency procedures.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Boen Healthcare Co. Ltd.
  • Cardinal Health Inc.
  • DermaRite Industries LLC
  • DeRoyal Industries Inc.
  • DUKAL Corp.
  • Dynarex Corp.
  • Gentell Inc.
  • Johnson and Johnson
  • Longterm Health
  • McKesson Corp.
  • Mediplast AB
  • Medline Inc.
  • Nichiban Co. Ltd.
  • Nitto Denko Corp.
  • Paul Hartmann AG
  • PRIMED Medical Products Inc.
  • Smith and Nephew plc
  • Solventum Corp.
  • Suzhou Sunmed Co. Ltd.
  • Sylke
  • Winner Medical Co. Ltd.
  • Wuhan Huawei Technology
  • YK Bangli
  • Zhende Medical Co. Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Wound closure strips market

  • In the Health Care Supplies industry, the institutional shift toward value-based purchasing models has accelerated the adoption of single-use, sterile consumables, directly impacting Wound Closure Strips demand by increasing procurement volumes by 18% in high-turnover ambulatory surgical workflow environments.
  • Stringent quality metrics under the ISO 13485 medical device standard have mandated the reduction of hospital acquired infection rates, driving a 25% increase in the utilization of sterile micro-environment maintenance tools and advanced Wound Closure Strips across intensive care units.
  • Advancements in continuous extrusion manufacturing for non-woven medical fabrics have lowered substrate production costs by 12%, enabling higher volume output of cost-effective Wound Closure Strips tailored for outpatient care efficiency and emergency clinical settings.
  • The widespread integration of hypoallergenic polymer formulations in modern medical dressings has mitigated the incidence of medical adhesive-related injury by 30%, pulling demand for next-generation Wound Closure Strips utilized in pediatric and geriatric dermatological care.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Wound Closure Strips Market insights. See full methodology.

Market Scope
Page number 297
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 4.3%
Market growth 2026-2030 USD 108032.7 thousand
Market structure Fragmented
YoY growth 2025-2026(%) 4.1%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Global Wound Closure Strips Market 2026-2030 is experiencing a structural transition as clinical facilities prioritize non-invasive tissue approximation to enhance procedural efficiency. The incorporation of a bio-resorbable botanical compound and an antimicrobial silver coating has transformed standard closures into active therapeutic barriers.
  • Hospitals implementing these advanced solutions have reported a 25% reduction in secondary dressing interventions, directly optimizing departmental budgeting and nursing labor allocation. The shift toward a microporous polyurethane film and breathable non-woven backing ensures optimal moisture vapor transmission, preventing localized maceration.
  • Furthermore, continuous product strategy adjustments focus on mitigating epidermal stripping by utilizing a medical-grade silicone adhesive designed for an atraumatic peel force. The integration of elastomeric fiber integration provides necessary dynamic elasticity, accommodating post-operative swelling without compromising structural integrity. By transitioning to a biocompatible hybrid polymer, medical device manufacturers ensure strict alignment with global toxicological compliance standards.
  • This continuous evolution in material engineering allows healthcare networks to minimize readmission penalties while significantly improving long-term cosmetic outcomes for vulnerable patient demographics.

What are the Key Data Covered in this Wound Closure Strips Market Research and Growth Report?

  • What is the expected growth of the Wound Closure Strips Market between 2026 and 2030?

    • USD 108.03 million, at a CAGR of 4.3%

  • What segmentation does the market report cover?

    • The report is segmented by Application (Hospital, Clinics, and Others), Product (Elastic, Reinforced, and Others), Material (Silicone, Polyester, Nylon, and Polyethylene) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Rising volume of surgical procedures and traumatic injuries, Clinical limitations in high tension surgical environments

  • Who are the major players in the Wound Closure Strips Market?

    • Boen Healthcare Co. Ltd., Cardinal Health Inc., DermaRite Industries LLC, DeRoyal Industries Inc., DUKAL Corp., Dynarex Corp., Gentell Inc., Johnson and Johnson, Longterm Health, McKesson Corp., Mediplast AB, Medline Inc., Nichiban Co. Ltd., Nitto Denko Corp., Paul Hartmann AG, PRIMED Medical Products Inc., Smith and Nephew plc, Solventum Corp., Suzhou Sunmed Co. Ltd., Sylke, Winner Medical Co. Ltd., Wuhan Huawei Technology, YK Bangli and Zhende Medical Co. Ltd.

Market Research Insights

  • The Global Wound Closure Strips Market 2026-2030 continuously adapts to prioritize patient safety and operational throughput in modern surgical facilities. By integrating advanced adhesives, hospitals have lowered the incidence of medical adhesive-related injury by 18%, significantly improving compliance with strict dermatological safety mandates.
  • Furthermore, the transition toward minimally invasive procedures has enhanced outpatient care efficiency, allowing clinics to reduce post-operative dressing changes by 22%. This shift accelerates the cellular epithelialization process while optimizing supply chain procurement models. Consequently, healthcare networks emphasize sterile micro-environment maintenance to curb cross-contamination, ultimately decreasing localized bacterial colonization rates by 15% across acute care departments.

We can help! Our analysts can customize this wound closure strips market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by Material
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ thousand)
Data Table on Global - Market size and forecast 2025-2030 ($ thousand)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Wound Closure Strips Market 2020 - 2024

Historic Market Size - Data Table on Global Wound Closure Strips Market 2020 - 2024 ($ thousand)

5.2 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ thousand)

5.3 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ thousand)

5.4 Material segment analysis 2020 - 2024

Historic Market Size - Material Segment 2020 - 2024 ($ thousand)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ thousand)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ thousand)

6. Qualitative Analysis

6.1 Impact of AI on Global Wound Closure Strips Market

6.2 Impact of geopolitical conflicts on Global Wound Closure Strips Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Application

8.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

8.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

8.3 Hospital - Market size and forecast 2025-2030

Chart on Hospital - Market size and forecast 2025-2030 ($ thousand)
Data Table on Hospital - Market size and forecast 2025-2030 ($ thousand)
Chart on Hospital - Year-over-year growth 2025-2030 (%)
Data Table on Hospital - Year-over-year growth 2025-2030 (%)

8.4 Clinics - Market size and forecast 2025-2030

Chart on Clinics - Market size and forecast 2025-2030 ($ thousand)
Data Table on Clinics - Market size and forecast 2025-2030 ($ thousand)
Chart on Clinics - Year-over-year growth 2025-2030 (%)
Data Table on Clinics - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Application

Market opportunity by Application ($ thousand)
Data Table on Market opportunity by Application ($ thousand)

9. Market Segmentation by Product

9.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

9.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

9.3 Elastic - Market size and forecast 2025-2030

Chart on Elastic - Market size and forecast 2025-2030 ($ thousand)
Data Table on Elastic - Market size and forecast 2025-2030 ($ thousand)
Chart on Elastic - Year-over-year growth 2025-2030 (%)
Data Table on Elastic - Year-over-year growth 2025-2030 (%)

9.4 Reinforced - Market size and forecast 2025-2030

Chart on Reinforced - Market size and forecast 2025-2030 ($ thousand)
Data Table on Reinforced - Market size and forecast 2025-2030 ($ thousand)
Chart on Reinforced - Year-over-year growth 2025-2030 (%)
Data Table on Reinforced - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ thousand)
Data Table on Others - Market size and forecast 2025-2030 ($ thousand)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Product

Market opportunity by Product ($ thousand)
Data Table on Market opportunity by Product ($ thousand)

10. Market Segmentation by Material

10.1 Market segments

Chart on Material - Market share 2025-2030 (%)
Data Table on Material - Market share 2025-2030 (%)

10.2 Comparison by Material

Chart on Comparison by Material
Data Table on Comparison by Material

10.3 Silicone - Market size and forecast 2025-2030

Chart on Silicone - Market size and forecast 2025-2030 ($ thousand)
Data Table on Silicone - Market size and forecast 2025-2030 ($ thousand)
Chart on Silicone - Year-over-year growth 2025-2030 (%)
Data Table on Silicone - Year-over-year growth 2025-2030 (%)

10.4 Polyester - Market size and forecast 2025-2030

Chart on Polyester - Market size and forecast 2025-2030 ($ thousand)
Data Table on Polyester - Market size and forecast 2025-2030 ($ thousand)
Chart on Polyester - Year-over-year growth 2025-2030 (%)
Data Table on Polyester - Year-over-year growth 2025-2030 (%)

10.5 Nylon - Market size and forecast 2025-2030

Chart on Nylon - Market size and forecast 2025-2030 ($ thousand)
Data Table on Nylon - Market size and forecast 2025-2030 ($ thousand)
Chart on Nylon - Year-over-year growth 2025-2030 (%)
Data Table on Nylon - Year-over-year growth 2025-2030 (%)

10.6 Polyethylene - Market size and forecast 2025-2030

Chart on Polyethylene - Market size and forecast 2025-2030 ($ thousand)
Data Table on Polyethylene - Market size and forecast 2025-2030 ($ thousand)
Chart on Polyethylene - Year-over-year growth 2025-2030 (%)
Data Table on Polyethylene - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Material

Market opportunity by Material ($ thousand)
Data Table on Market opportunity by Material ($ thousand)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ thousand)
Data Table on North America - Market size and forecast 2025-2030 ($ thousand)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ thousand)
Data Table on US - Market size and forecast 2025-2030 ($ thousand)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ thousand)
Data Table on Canada - Market size and forecast 2025-2030 ($ thousand)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ thousand)
Data Table on Mexico - Market size and forecast 2025-2030 ($ thousand)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ thousand)
Data Table on Europe - Market size and forecast 2025-2030 ($ thousand)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ thousand)
Data Table on Germany - Market size and forecast 2025-2030 ($ thousand)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ thousand)
Data Table on UK - Market size and forecast 2025-2030 ($ thousand)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ thousand)
Data Table on France - Market size and forecast 2025-2030 ($ thousand)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ thousand)
Data Table on Italy - Market size and forecast 2025-2030 ($ thousand)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ thousand)
Data Table on Spain - Market size and forecast 2025-2030 ($ thousand)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ thousand)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Asia - Market size and forecast 2025-2030 ($ thousand)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ thousand)
Data Table on China - Market size and forecast 2025-2030 ($ thousand)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ thousand)
Data Table on Japan - Market size and forecast 2025-2030 ($ thousand)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ thousand)
Data Table on India - Market size and forecast 2025-2030 ($ thousand)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Korea - Market size and forecast 2025-2030 ($ thousand)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ thousand)
Data Table on Thailand - Market size and forecast 2025-2030 ($ thousand)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ thousand)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ thousand)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ thousand)
Data Table on Brazil - Market size and forecast 2025-2030 ($ thousand)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ thousand)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ thousand)
Data Table on UAE - Market size and forecast 2025-2030 ($ thousand)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ thousand)
Data Table on Turkey - Market size and forecast 2025-2030 ($ thousand)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ thousand)
Data Table on Argentina - Market size and forecast 2025-2030 ($ thousand)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ thousand)
Data Table on Colombia - Market size and forecast 2025-2030 ($ thousand)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ thousand)
Data Table on South Africa - Market size and forecast 2025-2030 ($ thousand)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ thousand)
Data Table on Israel - Market size and forecast 2025-2030 ($ thousand)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ thousand)
Data Tables on Market opportunity by geography ($ thousand)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Rising volume of surgical procedures and traumatic injuries
Preference for non-invasive closure and minimal scarring
Focus on infection control and hospital dehiscence mitigation

13.2 Market challenges

Clinical limitations in high tension surgical environments
Adhesive induced skin complications and patient sensitivity
Intense market fragmentation and price erosion pressures

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Mitigation of medical adhesive related skin injuries
Integration of bioactive and antimicrobial material innovations
Escalating management of complex chronic ulcer care

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Boen Healthcare Co. Ltd.

Boen Healthcare Co. Ltd. - Overview
Boen Healthcare Co. Ltd. - Product / Service
Boen Healthcare Co. Ltd. - Key offerings
SWOT

15.5 Cardinal Health Inc.

Cardinal Health Inc. - Overview
Cardinal Health Inc. - Business segments
Cardinal Health Inc. - Key news
Cardinal Health Inc. - Key offerings
Cardinal Health Inc. - Segment focus
SWOT

15.6 DermaRite Industries LLC

DermaRite Industries LLC - Overview
DermaRite Industries LLC - Product / Service
DermaRite Industries LLC - Key offerings
SWOT

15.7 DeRoyal Industries Inc.

DeRoyal Industries Inc. - Overview
DeRoyal Industries Inc. - Product / Service
DeRoyal Industries Inc. - Key offerings
SWOT

15.8 Johnson and Johnson

Johnson and Johnson - Overview
Johnson and Johnson - Business segments
Johnson and Johnson - Key news
Johnson and Johnson - Key offerings
Johnson and Johnson - Segment focus
SWOT

15.9 McKesson Corp.

McKesson Corp. - Overview
McKesson Corp. - Business segments
McKesson Corp. - Key offerings
McKesson Corp. - Segment focus
SWOT

15.10 Mediplast AB

Mediplast AB - Overview
Mediplast AB - Product / Service
Mediplast AB - Key offerings
SWOT

15.11 Medline Inc.

Medline Inc. - Overview
Medline Inc. - Product / Service
Medline Inc. - Key news
Medline Inc. - Key offerings
SWOT

15.12 Nichiban Co. Ltd.

Nichiban Co. Ltd. - Overview
Nichiban Co. Ltd. - Product / Service
Nichiban Co. Ltd. - Key offerings
SWOT

15.13 Nitto Denko Corp.

Nitto Denko Corp. - Overview
Nitto Denko Corp. - Business segments
Nitto Denko Corp. - Key offerings
Nitto Denko Corp. - Segment focus
SWOT

15.14 Paul Hartmann AG

Paul Hartmann AG - Overview
Paul Hartmann AG - Business segments
Paul Hartmann AG - Key offerings
Paul Hartmann AG - Segment focus
SWOT

15.15 Smith and Nephew plc

Smith and Nephew plc - Overview
Smith and Nephew plc - Business segments
Smith and Nephew plc - Key offerings
Smith and Nephew plc - Segment focus
SWOT

15.16 Solventum Corp.

Solventum Corp. - Overview
Solventum Corp. - Product / Service
Solventum Corp. - Key offerings
SWOT

15.17 Winner Medical Co. Ltd.

Winner Medical Co. Ltd. - Overview
Winner Medical Co. Ltd. - Product / Service
Winner Medical Co. Ltd. - Key offerings
SWOT

15.18 Zhende Medical Co. Ltd.

Zhende Medical Co. Ltd. - Overview
Zhende Medical Co. Ltd. - Product / Service
Zhende Medical Co. Ltd. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Wound Closure Strips market growth will increase by USD 108032.7 thousand thousand during 2026-2030.

The Wound Closure Strips market is expected to grow at a CAGR of 4.3% during 2026-2030.

Wound Closure Strips market is segmented by Application (Hospital, Clinics, Others) Product (Elastic, Reinforced, Others) Material (Silicone, Polyester, Nylon, Polyethylene)

Boen Healthcare Co. Ltd., Cardinal Health Inc., DermaRite Industries LLC, DeRoyal Industries Inc., DUKAL Corp., Dynarex Corp., Gentell Inc., Johnson and Johnson, Longterm Health, McKesson Corp., Mediplast AB, Medline Inc., Nichiban Co. Ltd., Nitto Denko Corp., Paul Hartmann AG, PRIMED Medical Products Inc., Smith and Nephew plc, Solventum Corp., Suzhou Sunmed Co. Ltd., Sylke, Winner Medical Co. Ltd., Wuhan Huawei Technology, YK Bangli, Zhende Medical Co. Ltd. are a few of the key vendors in the Wound Closure Strips market.

North America will register the highest growth rate of 45.5% among the other regions. Therefore, the Wound Closure Strips market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, Colombia, South Africa, Israel

  • Rising volume of surgical procedures and traumatic injuries is the driving factor this market.

The Wound Closure Strips market vendors should focus on grabbing business opportunities from the Application segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA