Uncoated Paper Market Analysis, Size, and Forecast 2026-2030: APAC (China, India, and Japan), Europe (Germany, France, and Italy), North America (US, Mexico, and Canada), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Uncoated Paper Market Analysis, Size, and Forecast 2026-2030:
APAC (China, India, and Japan), Europe (Germany, France, and Italy), North America (US, Mexico, and Canada), Middle East and Africa (Turkey, South Africa, and Saudi Arabia), South America (Brazil, Argentina, and Colombia), and Rest of World (ROW)

Published: Nov 2026 307 Pages SKU: IRTNTR81853

Market Overview at a Glance

$9.26 B
Market Opportunity
3.3%
CAGR 2025 - 2030
54.8%
APAC Growth
$31.28 B
Uncoated woodfree paper segment 2024

Uncoated Paper Market Size 2026-2030

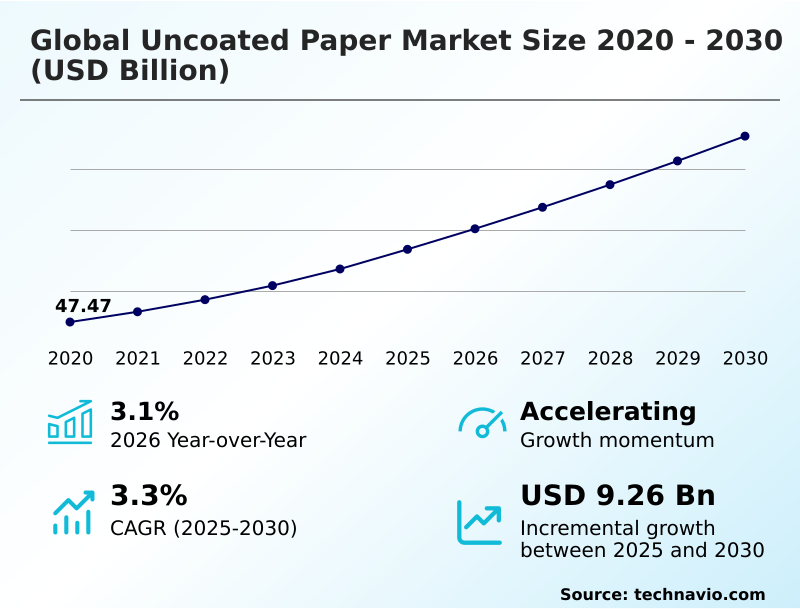
The uncoated paper market size is valued to increase by USD 9.26 billion, at a CAGR of 3.3% from 2025 to 2030. Transition toward sustainable paper-based packaging solutions. will drive the uncoated paper market.

Major Market Trends & Insights

  • APAC dominated the market and accounted for a 54.8% growth during the forecast period.
  • By Product Type - Uncoated woodfree paper segment was valued at USD 31.28 billion in 2024
  • By Type - Between 60 to 100 GSM segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 15.21 billion
  • Market Future Opportunities: USD 9.26 billion
  • CAGR from 2025 to 2030 : 3.3%

Market Summary

  • The Uncoated Paper Market demonstrates enduring structural resilience, driven by a transition toward circular economic models and specialized commercial printing applications. Enterprise supply chains are actively redesigning packaging portfolios, replacing petroleum-derived films with renewable cellulose substrates to meet stringent environmental compliance targets.
  • This material transition has enabled large retail organizations to reduce non-recyclable packaging waste by 40%, significantly improving corporate sustainability metrics. The primary driver propelling this sector is the rapid adoption of high-speed inkjet printing systems, which require treated uncoated sheets to absorb water-based pigments rapidly without strike-through. Consequently, publishers can execute efficient short-run print cycles that eliminate unsold inventory pulping.
  • Conversely, the market faces a substantial challenge from the aggressive digitalization of enterprise workflows. The permanent migration to electronic document repositories has structurally depressed the consumption of standard cut-size office paper.
  • Despite these digital headwinds, continuous innovations in surface chemistry and sustainable fiber sourcing ensure that uncoated media remains an indispensable component within premium publishing, sustainable packaging, and specialized industrial converting operations.

What will be the Size of the Uncoated Paper Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Uncoated Paper Market Segmented?

The uncoated paper industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product type
    • Uncoated woodfree paper
    • Uncoated mechanical paper
    • Specialty uncoated paper
  • Type
    • Between 60 to 100 GSM
    • Below 60 GSM
    • Above 100 GSM
  • Application
    • Printing and publishing
    • Office and business communication
    • Writing and educational stationery
    • Packaging and labeling
  • Geography
    • APAC
      • China
      • India
      • Japan
      • Indonesia
      • South Korea
      • Australia
    • Europe
      • Germany
      • France
      • Italy
      • UK
      • Spain
      • The Netherlands
    • North America
      • US
      • Mexico
      • Canada
    • Middle East and Africa
      • Turkey
      • South Africa
      • Saudi Arabia
      • UAE
      • Israel
    • South America
      • Brazil
      • Argentina
      • Colombia

By Product Type Insights

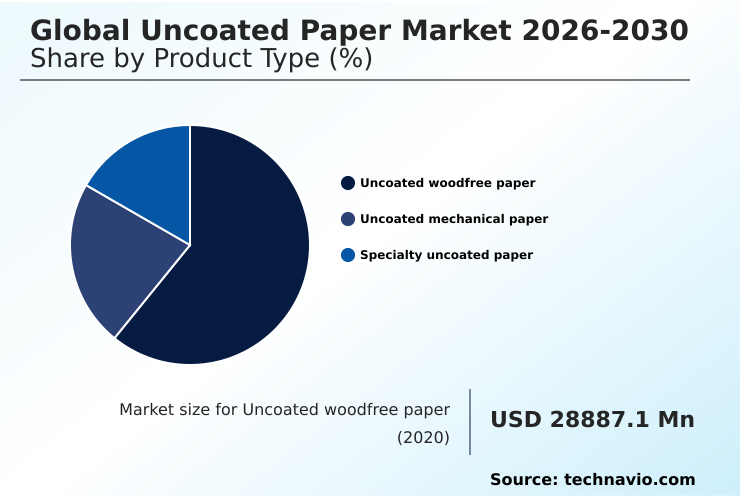
The uncoated woodfree paper segment is estimated to witness significant growth during the forecast period.

Uncoated woodfree paper dictates commercial printing standards by providing a structurally stable, high opacity substrate essential for high-volume publishing.

The manufacturing relies on advanced chemical pulp digestion to ensure complete lignin removal process execution, resulting in superior stability and resistance to aging.

This segmentation profoundly impacts business operations, as enterprise publishers require substrates that guarantee optimal toner adhesion without feathering. Utilizing these engineered grades, commercial print facilities have improved print run efficiency by 15% compared to alternative sheets.

The transition toward sustainable materials further accelerates demand, making these papers indispensable for circular economy packaging strategies. This shift enables organizations to eliminate excess inventory costs while maintaining premium presentation quality.
Get Free Sample

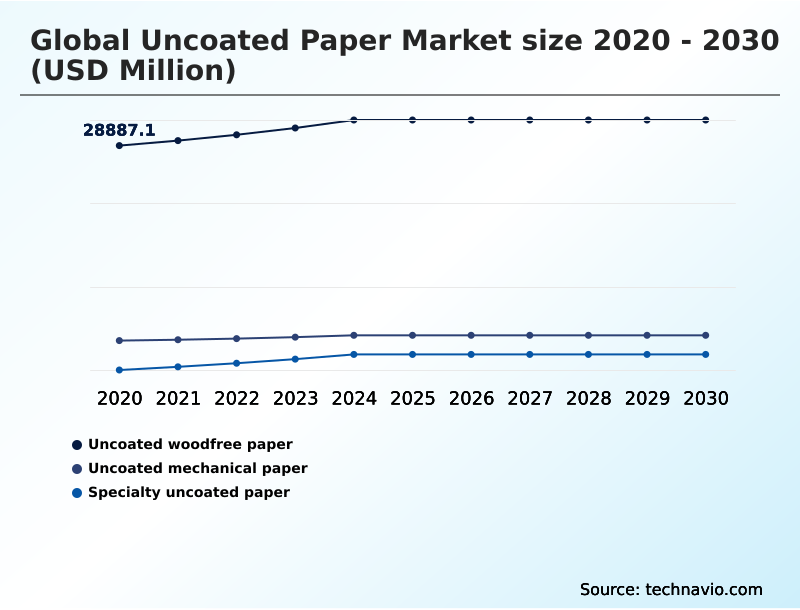
The Uncoated woodfree paper segment was valued at USD 31.28 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

APAC is estimated to contribute 54.8% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
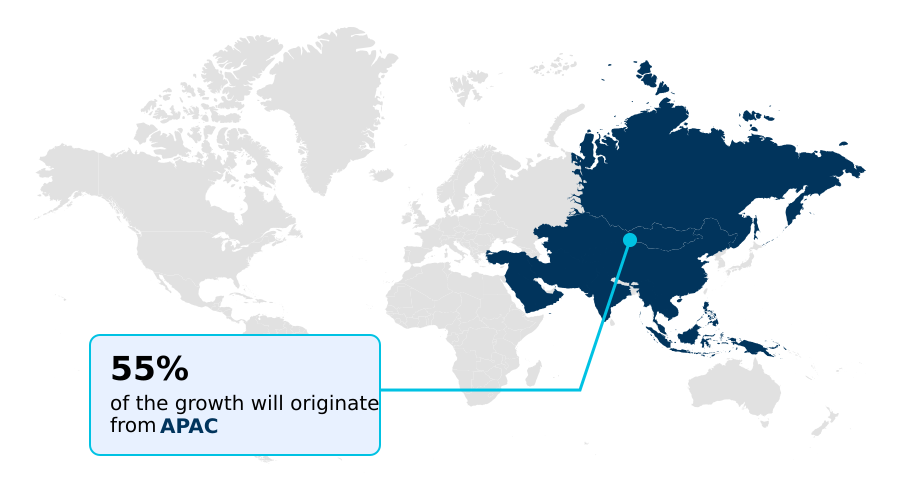
See How Uncoated Paper Market Demand is Rising in APAC Get Free Sample

The Asia-Pacific region dominates the Uncoated Paper Market by leveraging vast short-rotation plantation assets and modernized manufacturing infrastructure.

Compared to Europe, where structural graphic demand has contracted by 15% due to digital migration, Asia-Pacific exhibits a 20% higher institutional consumption rate driven by expanding educational procurement.

European operators offset domestic volume declines by focusing on premium tactile surface topography and strict certified sustainable forestry benchmarks.

In contrast, Asian manufacturers achieve massive economies of scale by integrating biomass cogeneration systems to power operations, lowering per-ton thermal energy costs by 25%. This cost disparity allows Asian mills to export highly competitive uncoated kraft paper globally.

Both regions are actively refining thermomechanical pulp processing to enhance ink receptivity. By aligning localized supply chain strategies with these distinct regional demands, international conglomerates secure durable operational efficiency.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The structural transformation of the Uncoated Paper Market is heavily influenced by the rigorous demands of specialized commercial applications and evolving environmental legislation. Enterprise publishers are rapidly adopting high speed digital printing uncoated sheets to facilitate distributed, short-run book manufacturing, which mitigates inventory risks and lowers long-distance logistics expenditures.
  • In parallel, the consumer goods sector is prioritizing sustainable uncoated retail packaging substrates to replace conventional multi-layer plastic films, achieving a 30% improvement in municipal recycling compliance rates compared to legacy polymer packaging.
  • This strategic shift requires advanced fiber engineering, prompting manufacturers to engineer recycled fiber uncoated woodfree paper that delivers exceptional brightness and structural integrity without relying entirely on virgin pulp.
  • The luxury marketing and boutique financial sectors continue to rely on tactile premium uncoated commercial printing to convey brand authenticity and prestige, utilizing heavy basis weights that coated alternatives simply cannot replicate. Furthermore, the pharmaceutical industry sustains non-cyclical demand for lightweight uncoated pharmaceutical insert paper, balancing extreme thinness with high tensile strength to ensure flawless operation on automated folding lines.
  • By integrating these highly specialized substrates into their procurement strategies, global corporations not only optimize their direct operational workflows but also fortify their overarching sustainability and supply chain resilience objectives.
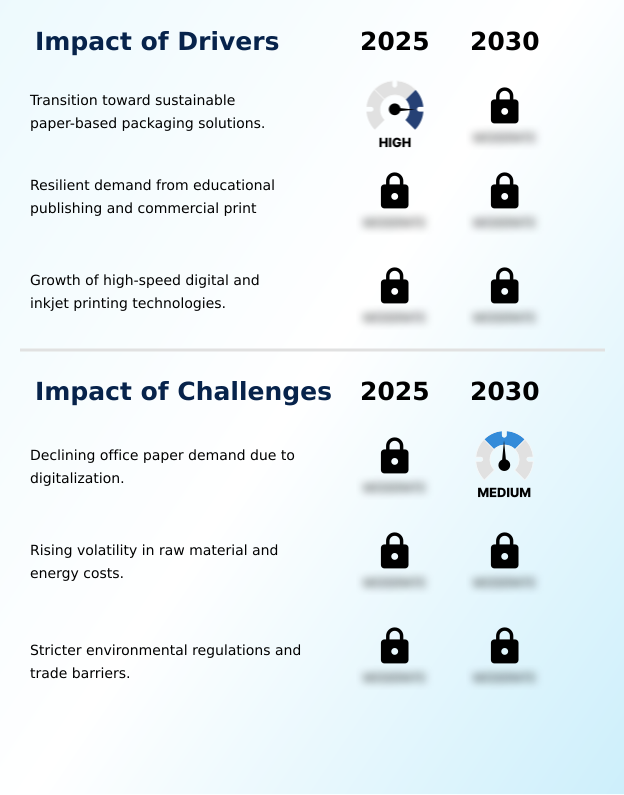
What are the key market drivers leading to the rise in the adoption of Uncoated Paper Industry?

  • The transition toward sustainable paper-based packaging solutions propels market expansion as consumer goods conglomerates aggressively replace synthetic polymers with biodegradable cellulose alternatives.

  • A primary catalyst propelling the Uncoated Paper Market is the aggressive expansion of short-run digital commercial printing. Because traditional offset systems require large minimum orders, print service providers are migrating to high-velocity inkjet webs that demand specialized uncoated media.
  • By incorporating micro porous surface additives and complex surface mineral treatments at the size press, papermakers have improved water based pigment fixation by 30%, virtually eliminating strike-through.
  • This chemical innovation ensures optimal dimensional sheet stability and superior web offset runnability during rapid thermal drying, allowing commercial printers to decrease paper waste by 15%.
  • The resulting ability to execute flawless print on demand fulfillment empowers global publishers to slash warehouse inventory costs by 22%. Ultimately, this material evolution secures the indispensability of uncoated substrates within highly automated graphic communication networks.

What are the market trends shaping the Uncoated Paper Industry?

  • Strategic capacity rationalization and asset optimization are actively reshaping the market landscape as manufacturers retire obsolete machinery to improve operational margins. This disciplined approach aligns production volumes with resilient baseline demand, preventing supply gluts and stabilizing long-term pricing structures.

  • The Uncoated Paper Market is experiencing a profound shift toward high-yield resource circularity and automated process optimization. Driven by intense margin pressure, mills are transforming into integrated biorefineries utilizing closed loop water circulation to minimize freshwater intake.
  • The adoption of strict effluent discharge management has reduced compliance violation risks by 18%, while modernized drying processes ensuring perfect sheet moisture balance have lowered thermal energy consumption by 25%. This operational modernization enables the production of premium uncoated sheets that offer superior tensile energy absorption for demanding packaging applications.
  • Furthermore, the industry is increasingly utilizing enzymatic deinking technology to process post consumer recycled fiber, seamlessly integrating recovered materials without sacrificing brightness. This strategic trend allows packaging converters to secure resilient materials while meeting regulatory mandates, enhancing supply chain sustainability.

What challenges does the Uncoated Paper Industry face during its growth?

  • Declining office paper demand due to digitalization significantly restrains volume growth as corporate enterprises and administrative institutions transition permanently to cloud-based document management workflows.

  • The Uncoated Paper Market is severely constrained by extreme volatility in raw material procurement and process energy expenditures. Because manufacturing is inherently heat-heavy, unpredictable fossil gas tariffs and stringent decarbonization mandate compliance penalties deeply fracture operating budgets.
  • Mills attempting to achieve high speed inkjet compatibility face intense margin compression, causing localized production costs for advanced chemical inputs to surge by up to 28% during supply chain bottlenecks. Furthermore, the mandatory application of a natural moisture resistance barrier requires enormous capital outlays, extending facility equipment amortization horizons by 40%.
  • When producers attempt to transfer these accumulated costs, enterprise buyers frequently downgrade their basis weights. This inability to consistently pass input inflation onto price-sensitive converters forces manufacturers to prioritize inexpensive precipitated calcium carbonate fillers and synthetic sizing agents, highlighting an enduring operational vulnerability.

Exclusive Technavio Analysis on Customer Landscape

The uncoated paper market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the uncoated paper market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
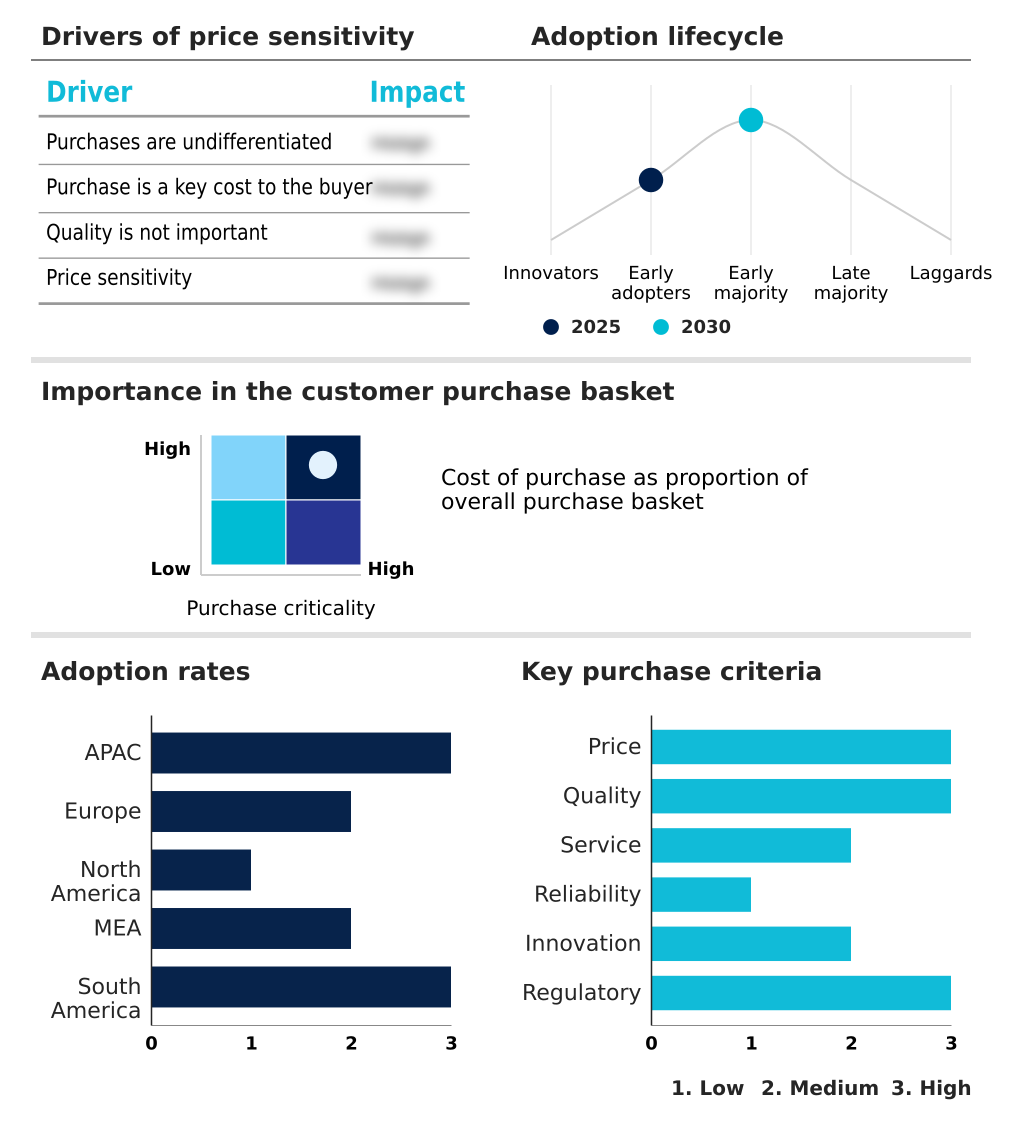
Customer Landscape of Uncoated Paper Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, uncoated paper market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Ambani Paper LLP - The vendor provides premium uncoated fine papers, high-opacity offset sheets, and tactile book papers engineered for sustainable packaging and advanced commercial printing applications.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Ambani Paper LLP
  • Asia Pulp and Paper Group
  • Burgo Group SpA
  • Domtar Corp.
  • FEDRIGONI Spa
  • Holmen AB
  • ITC Paperboards and Specialty
  • JK Paper Ltd.
  • Mondi Plc
  • Nippon Paper Industries Co. Ltd.
  • Oji Paper Co. Ltd
  • Packaging Corp. of America
  • RP Paper Impex Pvt Ltd
  • Sappi Ltd.
  • Stora Enso Oyj
  • Suzano SA
  • Sylvamo Corp
  • The Navigator Co. SA
  • UPM Communication Papers
  • West Coast Paper Mills Ltd.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Uncoated paper market

  • In the Paper Products industry, the widespread implementation of extended producer responsibility regulations has accelerated the transition from single-use plastics to renewable cellulose, directly impacting Uncoated Paper demand by driving a 25% increase in procurement for high-strength kraft packaging substrates.
  • The rapid modernization of high-speed digital inkjet printing technologies has forced paper manufacturers to reformulate surface sizing chemistry, resulting in a 30% improvement in water based pigment fixation that directly expands the commercial application range for Uncoated Paper.
  • Stricter effluent discharge management standards across major manufacturing hubs have compelled mills to invest heavily in closed loop water circulation networks, reducing freshwater consumption by 40% and altering the baseline production cost structure for Uncoated Paper.
  • The integration of enzymatic deinking technology in secondary fiber processing has enabled mills to incorporate up to 50% post consumer recycled fiber without compromising structural integrity, thereby allowing Uncoated Paper manufacturers to meet stringent corporate decarbonization mandate compliance targets.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Uncoated Paper Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 3.3%
Market growth 2026-2030 USD 9264.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 3.1%
Key countries China, India, Japan, Indonesia, South Korea, Australia, Germany, France, Italy, UK, Spain, The Netherlands, US, Mexico, Canada, Turkey, South Africa, Saudi Arabia, UAE, Israel, Brazil, Argentina and Colombia
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • Manufacturers in the Uncoated Paper Market are executing rigorous capacity rationalization to align production output with shifting consumption paradigms. This strategic pivot profoundly influences boardroom-level supply chain planning, as executives decommission uncompetitive assets and redirect capital toward high-yield packaging and specialty grades.
  • By concentrating operations within fully integrated facilities utilizing thermomechanical pulp processing and advanced chemical pulp digestion, enterprises have achieved a 20% reduction in baseline manufacturing overhead compared to non-integrated peers. This consolidation empowers firms to invest heavily in synthetic sizing agents and surface mineral treatments, which are critical for establishing high speed inkjet compatibility on modern commercial presses.
  • Furthermore, the implementation of precipitated calcium carbonate fillers allows mills to maintain sheet bulk while reducing overall fiber consumption. These optimized formulations guarantee rapid moisture penetration and sharp color fidelity. By integrating these advanced surface chemistries, paper producers protect their operating margins and deliver superior material reliability, directly supporting converters in their quest for operational excellence.

What are the Key Data Covered in this Uncoated Paper Market Research and Growth Report?

  • What is the expected growth of the Uncoated Paper Market between 2026 and 2030?

    • USD 9.26 billion, at a CAGR of 3.3%

  • What segmentation does the market report cover?

    • The report is segmented by Product Type (Uncoated woodfree paper, Uncoated mechanical paper, and Specialty uncoated paper), Type (Between 60 to 100 GSM, Below 60 GSM, and Above 100 GSM), Application (Printing and publishing, Office and business communication, Writing and educational stationery, and Packaging and labeling) and Geography (APAC, Europe, North America, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • APAC, Europe, North America, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Transition toward sustainable paper-based packaging solutions. , Declining office paper demand due to digitalization.

  • Who are the major players in the Uncoated Paper Market?

    • Ambani Paper LLP, Asia Pulp and Paper Group, Burgo Group SpA, Domtar Corp., FEDRIGONI Spa, Holmen AB, ITC Paperboards and Specialty, JK Paper Ltd., Mondi Plc, Nippon Paper Industries Co. Ltd., Oji Paper Co. Ltd, Packaging Corp. of America, RP Paper Impex Pvt Ltd, Sappi Ltd., Stora Enso Oyj, Suzano SA, Sylvamo Corp, The Navigator Co. SA, UPM Communication Papers and West Coast Paper Mills Ltd.

Market Research Insights

  • The Uncoated Paper Market is rapidly evolving to support high-performance industrial and commercial requirements. Facilities leveraging advanced dimensional sheet stability have reduced web offset runnability errors by 22%, driving significant operational efficiency gains. Furthermore, the integration of a specialized moisture resistance barrier has allowed packaging converters to increase the deployment of circular economy packaging formats by 35% across retail sectors.
  • By maintaining precise sheet moisture balance, commercial printers successfully mitigate paper curl during rapid heat fluctuations. Consequently, enterprise clients adopting these engineered substrates achieve a 15% reduction in overall printing downtime, proving that tactical material selection directly influences supply chain predictability and corporate profitability.

We can help! Our analysts can customize this uncoated paper market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product Type
Executive Summary - Chart on Market Segmentation by Type
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Uncoated Paper Market 2020 - 2024

Historic Market Size - Data Table on Global Uncoated Paper Market 2020 - 2024 ($ million)

5.2 Product Type segment analysis 2020 - 2024

Historic Market Size - Product Type Segment 2020 - 2024 ($ million)

5.3 Type segment analysis 2020 - 2024

Historic Market Size - Type Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Uncoated Paper Market

6.2 Impact of Geopolitical Conflicts on Global Uncoated Paper Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product Type

8.1 Market segments

Chart on Product Type - Market share 2025-2030 (%)
Data Table on Product Type - Market share 2025-2030 (%)

8.2 Comparison by Product Type

Chart on Comparison by Product Type
Data Table on Comparison by Product Type

8.3 Uncoated woodfree paper - Market size and forecast 2025-2030

Chart on Uncoated woodfree paper - Market size and forecast 2025-2030 ($ million)
Data Table on Uncoated woodfree paper - Market size and forecast 2025-2030 ($ million)
Chart on Uncoated woodfree paper - Year-over-year growth 2025-2030 (%)
Data Table on Uncoated woodfree paper - Year-over-year growth 2025-2030 (%)

8.4 Uncoated mechanical paper - Market size and forecast 2025-2030

Chart on Uncoated mechanical paper - Market size and forecast 2025-2030 ($ million)
Data Table on Uncoated mechanical paper - Market size and forecast 2025-2030 ($ million)
Chart on Uncoated mechanical paper - Year-over-year growth 2025-2030 (%)
Data Table on Uncoated mechanical paper - Year-over-year growth 2025-2030 (%)

8.5 Specialty uncoated paper - Market size and forecast 2025-2030

Chart on Specialty uncoated paper - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty uncoated paper - Market size and forecast 2025-2030 ($ million)
Chart on Specialty uncoated paper - Year-over-year growth 2025-2030 (%)
Data Table on Specialty uncoated paper - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product Type

Market opportunity by Product Type ($ million)
Data Table on Market opportunity by Product Type ($ million)

9. Market Segmentation by Type

9.1 Market segments

Chart on Type - Market share 2025-2030 (%)
Data Table on Type - Market share 2025-2030 (%)

9.2 Comparison by Type

Chart on Comparison by Type
Data Table on Comparison by Type

9.3 Between 60 to 100 GSM - Market size and forecast 2025-2030

Chart on Between 60 to 100 GSM - Market size and forecast 2025-2030 ($ million)
Data Table on Between 60 to 100 GSM - Market size and forecast 2025-2030 ($ million)
Chart on Between 60 to 100 GSM - Year-over-year growth 2025-2030 (%)
Data Table on Between 60 to 100 GSM - Year-over-year growth 2025-2030 (%)

9.4 Below 60 GSM - Market size and forecast 2025-2030

Chart on Below 60 GSM - Market size and forecast 2025-2030 ($ million)
Data Table on Below 60 GSM - Market size and forecast 2025-2030 ($ million)
Chart on Below 60 GSM - Year-over-year growth 2025-2030 (%)
Data Table on Below 60 GSM - Year-over-year growth 2025-2030 (%)

9.5 Above 100 GSM - Market size and forecast 2025-2030

Chart on Above 100 GSM - Market size and forecast 2025-2030 ($ million)
Data Table on Above 100 GSM - Market size and forecast 2025-2030 ($ million)
Chart on Above 100 GSM - Year-over-year growth 2025-2030 (%)
Data Table on Above 100 GSM - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Type

Market opportunity by Type ($ million)
Data Table on Market opportunity by Type ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Printing and publishing - Market size and forecast 2025-2030

Chart on Printing and publishing - Market size and forecast 2025-2030 ($ million)
Data Table on Printing and publishing - Market size and forecast 2025-2030 ($ million)
Chart on Printing and publishing - Year-over-year growth 2025-2030 (%)
Data Table on Printing and publishing - Year-over-year growth 2025-2030 (%)

10.4 Office and business communication - Market size and forecast 2025-2030

Chart on Office and business communication - Market size and forecast 2025-2030 ($ million)
Data Table on Office and business communication - Market size and forecast 2025-2030 ($ million)
Chart on Office and business communication - Year-over-year growth 2025-2030 (%)
Data Table on Office and business communication - Year-over-year growth 2025-2030 (%)

10.5 Writing and educational stationery - Market size and forecast 2025-2030

Chart on Writing and educational stationery - Market size and forecast 2025-2030 ($ million)
Data Table on Writing and educational stationery - Market size and forecast 2025-2030 ($ million)
Chart on Writing and educational stationery - Year-over-year growth 2025-2030 (%)
Data Table on Writing and educational stationery - Year-over-year growth 2025-2030 (%)

10.6 Packaging and labeling - Market size and forecast 2025-2030

Chart on Packaging and labeling - Market size and forecast 2025-2030 ($ million)
Data Table on Packaging and labeling - Market size and forecast 2025-2030 ($ million)
Chart on Packaging and labeling - Year-over-year growth 2025-2030 (%)
Data Table on Packaging and labeling - Year-over-year growth 2025-2030 (%)

10.7 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.3.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.3.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.3.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.3.4 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.3.5 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.3.6 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.3 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.4 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.5.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.5.2 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.5.3 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.2 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.3 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.5 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Transition toward sustainable paper-based packaging solutions.
Resilient demand from educational publishing and commercial print
Growth of high-speed digital and inkjet printing technologies.

13.2 Market challenges

Declining office paper demand due to digitalization.
Rising volatility in raw material and energy costs.
Stricter environmental regulations and trade barriers.

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Strategic capacity rationalization and asset optimization
Surging corporate and consumer preference for tactile specialty uncoated grades
Decarbonization and resource circularity in pulp and paper manufacturing

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Burgo Group SpA

Burgo Group SpA - Overview
Burgo Group SpA - Product / Service
Burgo Group SpA - Key offerings
SWOT

15.5 Holmen AB

Holmen AB - Overview
Holmen AB - Business segments
Holmen AB - Key offerings
Holmen AB - Segment focus
SWOT

15.6 ITC Paperboards and Specialty

ITC Paperboards and Specialty - Overview
ITC Paperboards and Specialty - Product / Service
ITC Paperboards and Specialty - Key offerings
SWOT

15.7 JK Paper Ltd.

JK Paper Ltd. - Overview
JK Paper Ltd. - Business segments
JK Paper Ltd. - Key offerings
JK Paper Ltd. - Segment focus
SWOT

15.8 Mondi Plc

Mondi Plc - Overview
Mondi Plc - Business segments
Mondi Plc - Key news
Mondi Plc - Key offerings
Mondi Plc - Segment focus
SWOT

15.9 Nippon Paper Industries Co. Ltd.

Nippon Paper Industries Co. Ltd. - Overview
Nippon Paper Industries Co. Ltd. - Business segments
Nippon Paper Industries Co. Ltd. - Key offerings
Nippon Paper Industries Co. Ltd. - Segment focus
SWOT

15.10 Oji Paper Co. Ltd

Oji Paper Co. Ltd - Overview
Oji Paper Co. Ltd - Product / Service
Oji Paper Co. Ltd - Key offerings
SWOT

15.11 Packaging Corp. of America

Packaging Corp. of America - Overview
Packaging Corp. of America - Business segments
Packaging Corp. of America - Key offerings
Packaging Corp. of America - Segment focus
SWOT

15.12 Sappi Ltd.

Sappi Ltd. - Overview
Sappi Ltd. - Business segments
Sappi Ltd. - Key offerings
Sappi Ltd. - Segment focus
SWOT

15.13 Stora Enso Oyj

Stora Enso Oyj - Overview
Stora Enso Oyj - Business segments
Stora Enso Oyj - Key news
Stora Enso Oyj - Key offerings
Stora Enso Oyj - Segment focus
SWOT

15.14 Suzano SA

Suzano SA - Overview
Suzano SA - Business segments
Suzano SA - Key offerings
Suzano SA - Segment focus
SWOT

15.15 Sylvamo Corp

Sylvamo Corp - Overview
Sylvamo Corp - Business segments
Sylvamo Corp - Key offerings
Sylvamo Corp - Segment focus
SWOT

15.16 The Navigator Co. SA

The Navigator Co. SA - Overview
The Navigator Co. SA - Business segments
The Navigator Co. SA - Key offerings
The Navigator Co. SA - Segment focus
SWOT

15.17 UPM Communication Papers

UPM Communication Papers - Overview
UPM Communication Papers - Product / Service
UPM Communication Papers - Key offerings
SWOT

15.18 West Coast Paper Mills Ltd.

West Coast Paper Mills Ltd. - Overview
West Coast Paper Mills Ltd. - Business segments
West Coast Paper Mills Ltd. - Key offerings
West Coast Paper Mills Ltd. - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Uncoated Paper market growth will increase by USD 9264.6 million during 2026-2030.

The Uncoated Paper market is expected to grow at a CAGR of 3.3% during 2026-2030.

Uncoated Paper market is segmented by Product type (Uncoated woodfree paper, Uncoated mechanical paper, Specialty uncoated paper) Type (Between 60 to 100 GSM, Below 60 GSM, Above 100 GSM) Application (Printing and publishing, Office and business communication, Writing and educational stationery, Packaging and labeling)

Ambani Paper LLP, Asia Pulp and Paper Group, Burgo Group SpA, Domtar Corp., FEDRIGONI Spa, Holmen AB, ITC Paperboards and Specialty, JK Paper Ltd., Mondi Plc, Nippon Paper Industries Co. Ltd., Oji Paper Co. Ltd, Packaging Corp. of America, RP Paper Impex Pvt Ltd, Sappi Ltd., Stora Enso Oyj, Suzano SA, Sylvamo Corp, The Navigator Co. SA, UPM Communication Papers, West Coast Paper Mills Ltd. are a few of the key vendors in the Uncoated Paper market.

APAC will register the highest growth rate of 54.8% among the other regions. Therefore, the Uncoated Paper market in APAC is expected to garner significant business opportunities for the vendors during the forecast period.

China, India, Japan, Indonesia, South Korea, Australia, Germany, France, Italy, UK, Spain, The Netherlands, US, Mexico, Canada, Turkey, South Africa, Saudi Arabia, UAE, Israel, Brazil, Argentina, Colombia

  • Transition toward sustainable paper-based packaging solutions. is the driving factor this market.

The Uncoated Paper market vendors should focus on grabbing business opportunities from the Product type segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA