Healthcare Education Solutions Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Healthcare Education Solutions Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), APAC (China, Japan, and India), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Nov 2026 291 Pages SKU: IRTNTR40829

Market Overview at a Glance

$7.80 B
Market Opportunity
9.9%
CAGR 2025 - 2030
32%
North America Growth
$7.57 B
Classroom-based segment 2024

Healthcare Education Solutions Market Size 2026-2030

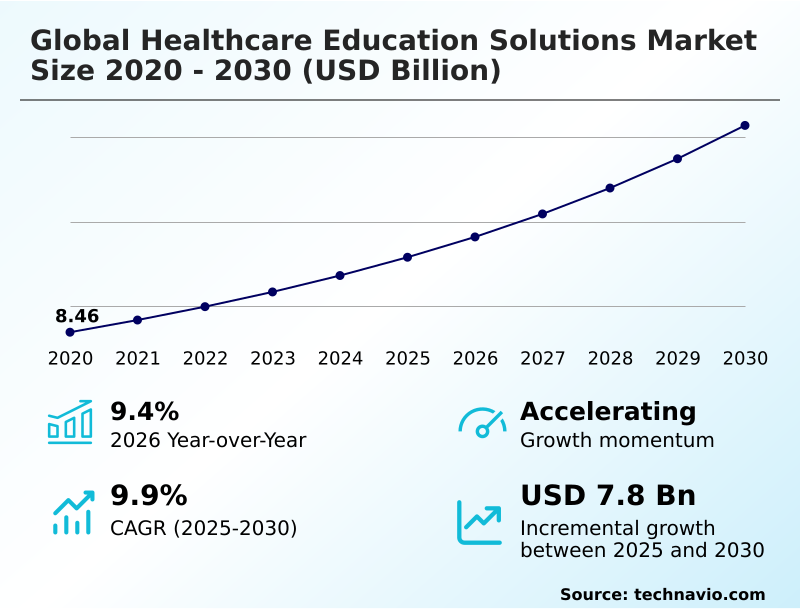
The healthcare education solutions market size is valued to increase by USD 7.80 billion, at a CAGR of 9.9% from 2025 to 2030. Surging global shortage of skilled healthcare professionals will drive the healthcare education solutions market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 32% growth during the forecast period.
  • By Delivery - Classroom-based segment was valued at USD 7.57 billion in 2024
  • By End-user - Physician segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 12.23 billion
  • Market Future Opportunities: USD 7.80 billion
  • CAGR from 2025 to 2030 : 9.9%

Market Summary

  • The Healthcare Education Solutions Market is experiencing rapid structural progression sustained by an accelerating technological evolution across multi-tenant cloud platforms and high-fidelity simulation hardware. To address the severe healthcare workforce deficit, hospital systems are dramatically expanding student enrollment capacities and accelerating clinical onboarding programs.
  • This surging shortage of skilled healthcare professionals acts as a primary driver, compelling institutions to adopt virtual reality surgical trainers and adaptive micro-learning algorithms to scale training volume without compromising patient safety protocols. In a practical operational scenario, academic medical centers deploying integrated electronic health record simulators have reduced clinical onboarding time by 20% compared to traditional didactic methods.
  • However, the market faces substantial friction from high capital acquisition expenditures and infrastructure costs. Allocating extensive capital for advanced standardized patient simulation suites presents a formidable purchasing barrier for regional hospital networks operating under constrained budgets.
  • Despite these financial challenges, the imperative to maintain accreditation compliance frameworks and deliver verifiable evidence of graduate clinical preparedness ensures sustained institutional investment in evidence-based clinical decision support tools and interprofessional healthcare education platforms.

What will be the Size of the Healthcare Education Solutions Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Healthcare Education Solutions Market Segmented?

The healthcare education solutions industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Delivery
    • Classroom-based
    • E-learning
  • End-user
    • Physician
    • Non-physician
  • Application
    • Cardiology
    • Radiology
    • Neurology
    • Pediatrics
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Delivery Insights

The classroom-based segment is estimated to witness significant growth during the forecast period.

The classroom-based segment within the sector commands a foundational share of institutional training volume, driven by the indispensable requirement for hands-on clinical skills development and direct faculty mentorship.

Physical tactile training remains mandatory to instill fine motor skills and procedural muscle memory under high-pressure clinical scenarios. Academic institutions heavily invest in procedural task trainers to provide realistic clinical environments that align with competency-based medical education.

By integrating hybrid simulation environments, medical schools have improved procedural error detection by 15%, ensuring trainees practice critical care protocols safely.

Regulatory accreditation compliance frameworks mandate specific minimum thresholds for physical clinical laboratory hours, sustaining the reliance on face-to-face instruction and tactile skill verification for long-term operational success.
Get Free Sample

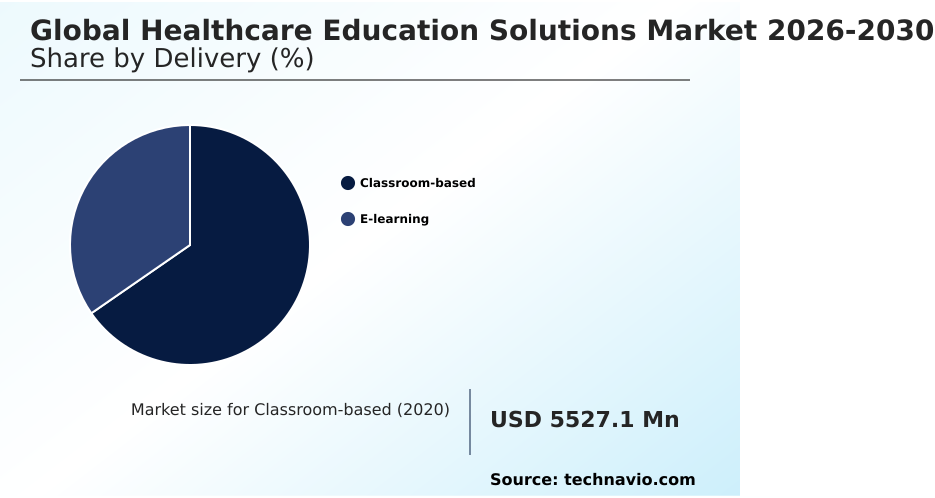
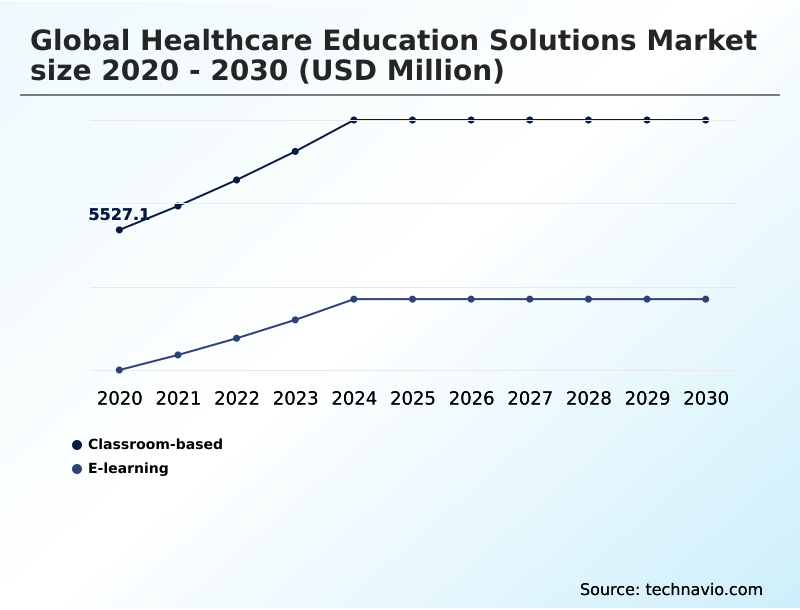
The Classroom-based segment was valued at USD 7.57 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 32% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
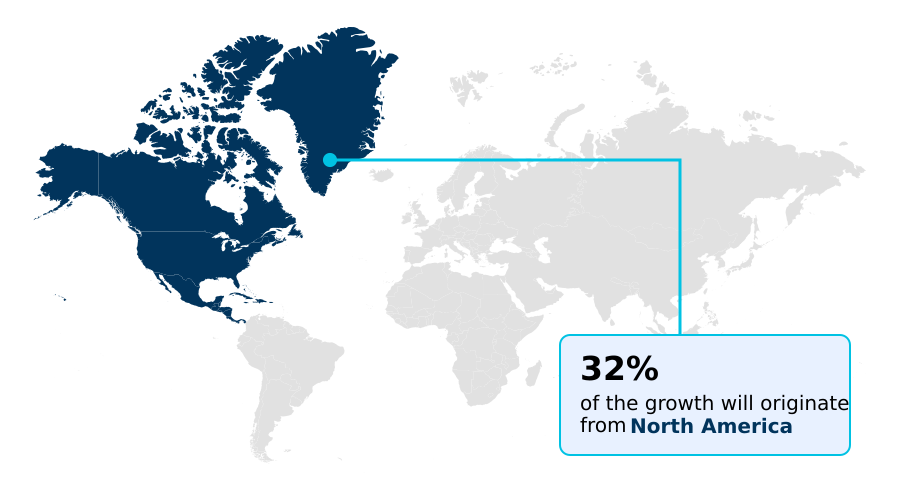
See How Healthcare Education Solutions Market Demand is Rising in North America Get Free Sample

The geographic landscape reveals distinct regional adoption patterns driven by varying healthcare infrastructure investments. North America maintains a dominant position, characterized by heavy investments in electronic health record simulators and digital health initiatives.

Institutions in this region have achieved a 35% reduction in clinical training errors by integrating high-fidelity patient manikins into their curricula. In contrast, APAC is experiencing the most rapid expansion, propelled by massive medical university capacity growth.

While North American facilities focus on advanced immersive environments, APAC institutions are rapidly deploying mobile-accessible clinical reference tools to bridge geographical training gaps, resulting in a 40% increase in remote asynchronous learning participation.

This divergence highlights how mature markets prioritize complex technical integrations, whereas emerging regions leverage scalable mobile solutions to accelerate clinical readiness efficiently.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Healthcare Education Solutions sector is fundamentally restructuring how medical institutions approach clinical skill acquisition and continuous professional development. As academic medical centers navigate complex accreditation requirements, the competency-based medical education curriculum transition has become a central strategic priority, ensuring that graduates demonstrate verifiable objective clinical competencies.
  • To facilitate this shift, institutions are heavily investing in virtual reality surgical training modules, which allow learners to practice high-stakes interventions in a zero-risk environment. This immersive approach has demonstrated a nearly two-fold improvement in procedural muscle memory retention compared to traditional textbook learning, directly optimizing operational planning by reducing the time required for supervised clinical rotations.
  • Furthermore, the seamless cloud-hosted learning management system integration enables administrators to centralize educational data, streamlining compliance reporting and resource allocation across disparate hospital campuses. By deploying AI-powered clinical skill assessment dashboards, clinical educators can continuously monitor diagnostic reasoning and pinpoint individual knowledge gaps in real time, significantly enhancing the efficiency of remedial training interventions.
  • Additionally, widespread high-fidelity patient simulation software deployment provides interprofessional care teams with realistic scenarios to refine communication and resuscitation coordination.
  • Ultimately, these advanced digital education architectures not only accelerate clinical onboarding but also establish a scalable, data-driven framework that fortifies patient safety protocols, reduces institutional liability risks, and ensures that the healthcare workforce remains agile and proficient in an increasingly complex medical landscape.
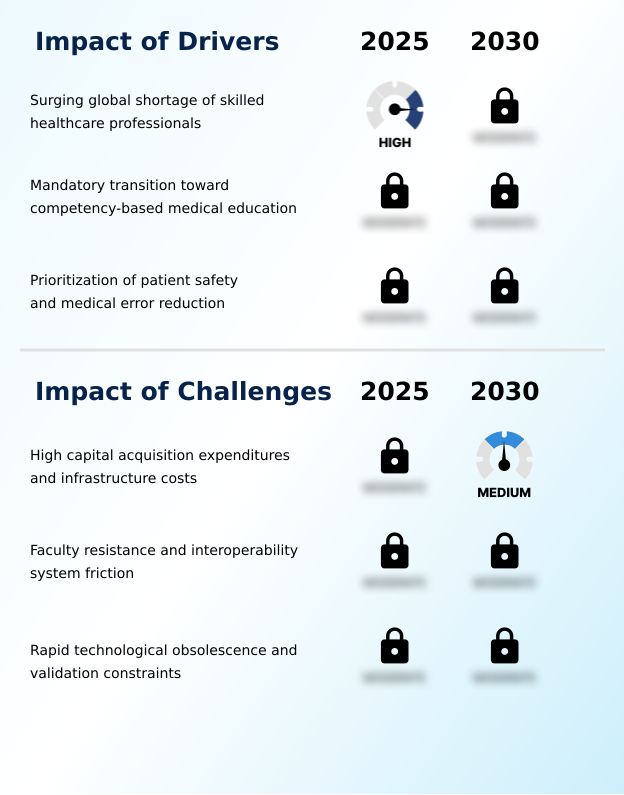
What are the key market drivers leading to the rise in the adoption of Healthcare Education Solutions Industry?

  • The surging global shortage of skilled healthcare professionals serves as a primary macroeconomic driver propelling the expansion of the market.

  • The accelerating healthcare workforce deficit serves as a powerful catalyst propelling the widespread adoption of advanced clinical training technologies through smart education initiatives.
  • To address the chronic shortage of qualified personnel, medical facilities are compelled to scale their training capacities rapidly without compromising stringent patient safety protocols or medical error reduction targets.
  • By implementing virtual reality surgical trainers and spatial computing headsets, institutions have successfully reduced onboarding duration by 25% while improving procedural error detection by 18%.
  • This shift toward immersive extended reality clinical environments allows learners to master minimally invasive interventional procedures and diagnostic radiology digitization workflows safely. Consequently, academic centers can optimize facility utilization and lower operational training costs by 15%.
  • The imperative to accelerate student readiness using evidence-based clinical decision support and virtual resuscitation trainers ensures continuous investment in scalable interprofessional healthcare education.

What are the market trends shaping the Healthcare Education Solutions Industry?

  • The integration of generative artificial intelligence and adaptive learning algorithms represents a defining technological trend in the market. These advanced systems personalize educational content in real time, significantly enhancing learner proficiency and clinical reasoning.

  • The rapid integration of generative artificial intelligence tutors and adaptive micro-learning algorithms into clinical simulation platforms is fundamentally transforming how objective clinical competencies are acquired. This technological shift is driven by the need to personalize learning pathways during complex precision medicine training and surgical robotics adoption.
  • By deploying these systems, institutions have improved diagnostic reasoning evaluation accuracy by 25% and reduced remediation time by 30%. These dynamic platforms analyze learner performance continuously, generating tailored interactive clinical case studies grounded in evidence-based medical literature.
  • Consequently, hospital departments experience a 20% increase in continuous professional development completion rates, particularly in specialized fields like neurovascular disease management and pediatric advanced life support.
  • The widespread adoption of AI-driven digital nursing simulation software and automated performance tracking directly impacts operations by streamlining clinical onboarding acceleration, enhancing clinical skill verification, and facilitating seamless telehealth education expansion alongside accredited continuing medical education.

What challenges does the Healthcare Education Solutions Industry face during its growth?

  • High capital acquisition expenditures and ongoing infrastructure costs represent significant challenges constraining broad market conversion across price-sensitive educational facilities.

  • Elevated procurement and maintenance costs associated with advanced learning technologies create substantial financial friction for academic institutions attempting healthcare infrastructure modernization. Deploying comprehensive standardized patient simulation suites and haptic-feedback surgical simulators requires massive upfront capital outlays, presenting a formidable purchasing barrier.
  • Institutions operating under constrained budgets frequently experience a 30% delay in upgrading legacy training equipment, which hampers effective clinical diagnostic training and the rollout of vital clinical pharmacology updates. Furthermore, technical interoperability hurdles between modern cloud-hosted learning management systems and proprietary hospital IT architectures increase administrative overhead by 20%.
  • These integration bottlenecks and high total costs of ownership force price-sensitive facilities to rely on traditional classroom instruction, reducing overall distance learning solutions efficiency by 15% and slowing the broader market penetration of sophisticated 3D anatomical modeling software.

Exclusive Technavio Analysis on Customer Landscape

The healthcare education solutions market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the healthcare education solutions market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
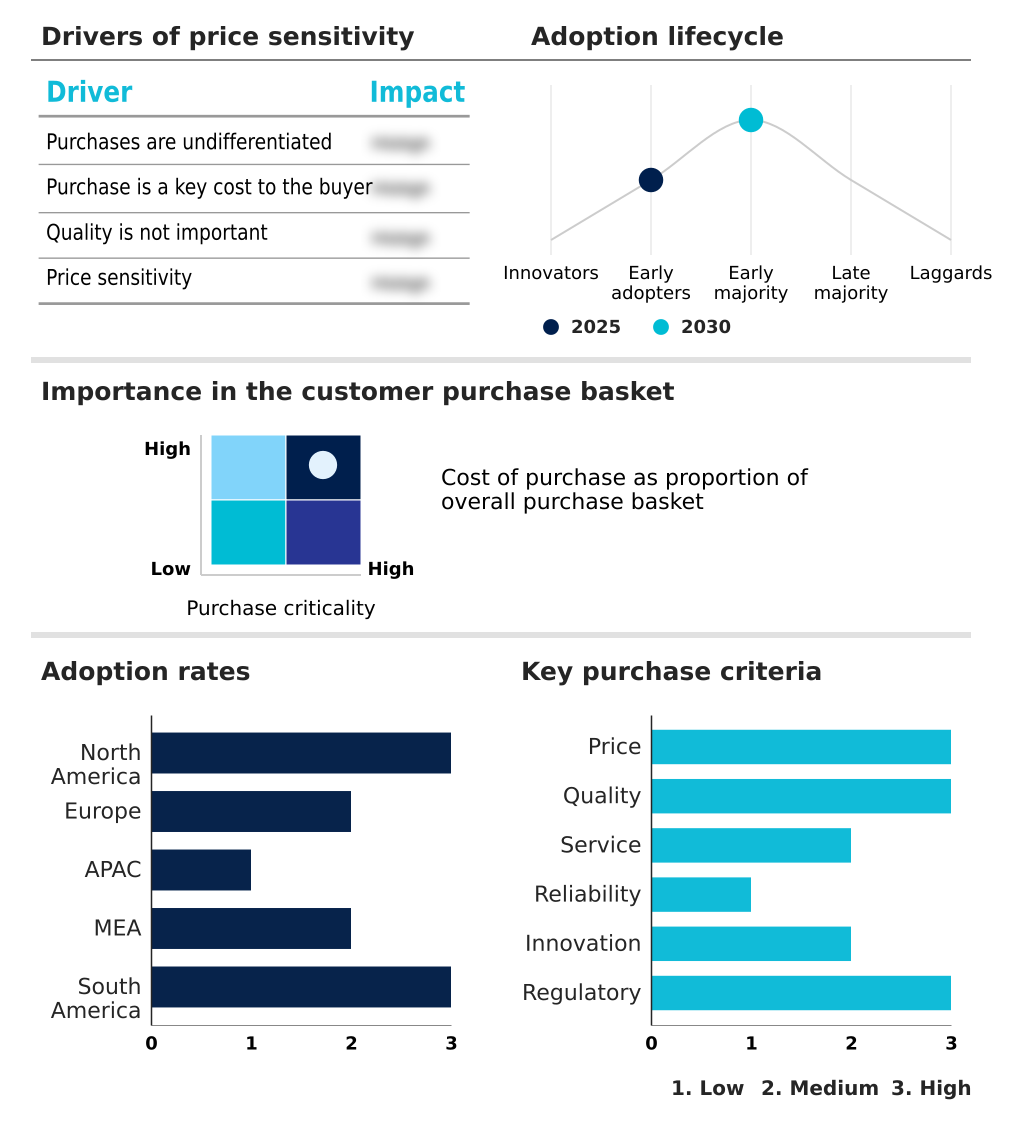
Customer Landscape of Healthcare Education Solutions Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, healthcare education solutions market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

3B Scientific GmbH - The provider delivers comprehensive healthcare education solutions, including advanced anatomical models, medical training simulators, and clinical skills trainers designed to enhance procedural competency and patient safety.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • 3B Scientific GmbH
  • Amboss GmbH
  • Ascend Learning LLC
  • Elevate Healthcare Inc.
  • Elsevier Ltd.
  • Gaumard Scientific Co. Inc.
  • HealthStream Inc.
  • Kyoto Kagaku Co. Ltd.
  • Laerdal Medical AS
  • Limbs and Things Ltd.
  • Mentice AB
  • Nasco Healthcare Inc.
  • Osso VR Inc.
  • Oxford Medical Simulation Ltd.
  • Simulab Corp.
  • SimX Inc
  • Surgical Science Sweden AB
  • Trucorp Ltd.
  • VirtaMed AG
  • Wolters Kluwer NV

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Healthcare education solutions market

  • In the Education Services industry, the rapid transition toward competency-based medical education frameworks has standardized clinical skill verification, directly impacting Healthcare Education Solutions demand by requiring institutions to adopt automated performance tracking systems that improve assessment accuracy by 25%.
  • The widespread integration of spatial computing headsets in vocational training programs has accelerated remote asynchronous learning capabilities, driving Healthcare Education Solutions providers to develop extended reality clinical environments that reduce physical laboratory dependency by 30%.
  • Stringent data privacy regulations governing digital health initiatives have forced educational platforms to upgrade cloud-hosted learning management systems, increasing the adoption of secure electronic health record simulators that ensure full compliance with patient confidentiality mandates.
  • The global expansion of telehealth education expansion initiatives has shifted continuous professional development requirements, compelling Healthcare Education Solutions developers to deploy mobile-accessible clinical reference tools that boost physician engagement rates by 40%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Healthcare Education Solutions Market insights. See full methodology.

Market Scope
Page number 291
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 9.9%
Market growth 2026-2030 USD 7797.4 million
Market structure Fragmented
YoY growth 2025-2026(%) 9.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The Healthcare Education Solutions sector is undergoing a profound structural transformation driven by the mandate to eliminate preventable medical errors and accelerate clinical readiness. Boardroom executives and clinical education directors are increasingly prioritizing the integration of generative artificial intelligence tutors and adaptive micro-learning algorithms to optimize workforce training budgets and ensure strict adherence to accreditation compliance frameworks.
  • By transitioning from static didactic models to dynamic, data-driven learning ecosystems, healthcare organizations have achieved a 30% reduction in time-to-competency for newly onboarded nursing staff. This strategic shift heavily relies on the deployment of electronic health record simulators and 3D anatomical modeling software, which seamlessly bridge the gap between academic theory and practical application.
  • Furthermore, the utilization of haptic-feedback surgical simulators provides surgeons with risk-free environments to master minimally invasive interventional procedures, directly lowering hospital liability risks. As precision medicine training becomes increasingly complex, the adoption of accredited continuing medical education platforms and automated performance tracking systems remains critical for maintaining objective clinical competencies and sustaining operational excellence across multi-campus health networks.

What are the Key Data Covered in this Healthcare Education Solutions Market Research and Growth Report?

  • What is the expected growth of the Healthcare Education Solutions Market between 2026 and 2030?

    • USD 7.80 billion, at a CAGR of 9.9%

  • What segmentation does the market report cover?

    • The report is segmented by Delivery (Classroom-based, and E-learning), End-user (Physician, and Non-physician), Application (Cardiology, Radiology, Neurology, Pediatrics, and Others) and Geography (North America, Europe, APAC, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, Europe, APAC, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Surging global shortage of skilled healthcare professionals, High capital acquisition expenditures and infrastructure costs

  • Who are the major players in the Healthcare Education Solutions Market?

    • 3B Scientific GmbH, Amboss GmbH, Ascend Learning LLC, Elevate Healthcare Inc., Elsevier Ltd., Gaumard Scientific Co. Inc., HealthStream Inc., Kyoto Kagaku Co. Ltd., Laerdal Medical AS, Limbs and Things Ltd., Mentice AB, Nasco Healthcare Inc., Osso VR Inc., Oxford Medical Simulation Ltd., Simulab Corp., SimX Inc, Surgical Science Sweden AB, Trucorp Ltd., VirtaMed AG and Wolters Kluwer NV

Market Research Insights

  • The Healthcare Education Solutions Market is rapidly evolving to address the critical healthcare workforce deficit through advanced digital learning architectures. Institutions are increasingly prioritizing patient safety protocols and medical error reduction by integrating immersive simulation technologies. Facilities adopting hybrid simulation environments have reported a 30% improvement in clinical diagnostic training efficiency and a 25% reduction in preventable procedural errors.
  • Furthermore, the shift toward remote asynchronous learning has accelerated the deployment of mobile-accessible platforms, boosting continuous professional development completion rates by 40%. These measurable operational improvements underscore the critical role of scalable educational technologies in meeting stringent accreditation compliance frameworks while optimizing clinical onboarding acceleration across diverse medical disciplines.

We can help! Our analysts can customize this healthcare education solutions market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Delivery
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Healthcare Education Solutions Market 2020 - 2024

Historic Market Size - Data Table on Global Healthcare Education Solutions Market 2020 - 2024 ($ million)

5.2 Delivery segment analysis 2020 - 2024

Historic Market Size - Delivery Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global healthcare education solutions market

6.2 Impact of geopolitical conflicts on global healthcare education solutions market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Delivery

8.1 Market segments

Chart on Delivery - Market share 2025-2030 (%)
Data Table on Delivery - Market share 2025-2030 (%)

8.2 Comparison by Delivery

Chart on Comparison by Delivery
Data Table on Comparison by Delivery

8.3 Classroom-based - Market size and forecast 2025-2030

Chart on Classroom-based - Market size and forecast 2025-2030 ($ million)
Data Table on Classroom-based - Market size and forecast 2025-2030 ($ million)
Chart on Classroom-based - Year-over-year growth 2025-2030 (%)
Data Table on Classroom-based - Year-over-year growth 2025-2030 (%)

8.4 E-learning - Market size and forecast 2025-2030

Chart on E-learning - Market size and forecast 2025-2030 ($ million)
Data Table on E-learning - Market size and forecast 2025-2030 ($ million)
Chart on E-learning - Year-over-year growth 2025-2030 (%)
Data Table on E-learning - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Delivery

Market opportunity by Delivery ($ million)
Data Table on Market opportunity by Delivery ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Physician - Market size and forecast 2025-2030

Chart on Physician - Market size and forecast 2025-2030 ($ million)
Data Table on Physician - Market size and forecast 2025-2030 ($ million)
Chart on Physician - Year-over-year growth 2025-2030 (%)
Data Table on Physician - Year-over-year growth 2025-2030 (%)

9.4 Non-physician - Market size and forecast 2025-2030

Chart on Non-physician - Market size and forecast 2025-2030 ($ million)
Data Table on Non-physician - Market size and forecast 2025-2030 ($ million)
Chart on Non-physician - Year-over-year growth 2025-2030 (%)
Data Table on Non-physician - Year-over-year growth 2025-2030 (%)

9.5 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Cardiology - Market size and forecast 2025-2030

Chart on Cardiology - Market size and forecast 2025-2030 ($ million)
Data Table on Cardiology - Market size and forecast 2025-2030 ($ million)
Chart on Cardiology - Year-over-year growth 2025-2030 (%)
Data Table on Cardiology - Year-over-year growth 2025-2030 (%)

10.4 Radiology - Market size and forecast 2025-2030

Chart on Radiology - Market size and forecast 2025-2030 ($ million)
Data Table on Radiology - Market size and forecast 2025-2030 ($ million)
Chart on Radiology - Year-over-year growth 2025-2030 (%)
Data Table on Radiology - Year-over-year growth 2025-2030 (%)

10.5 Neurology - Market size and forecast 2025-2030

Chart on Neurology - Market size and forecast 2025-2030 ($ million)
Data Table on Neurology - Market size and forecast 2025-2030 ($ million)
Chart on Neurology - Year-over-year growth 2025-2030 (%)
Data Table on Neurology - Year-over-year growth 2025-2030 (%)

10.6 Pediatrics - Market size and forecast 2025-2030

Chart on Pediatrics - Market size and forecast 2025-2030 ($ million)
Data Table on Pediatrics - Market size and forecast 2025-2030 ($ million)
Chart on Pediatrics - Year-over-year growth 2025-2030 (%)
Data Table on Pediatrics - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging global shortage of skilled healthcare professionals
Mandatory transition toward competency-based medical education
Prioritization of patient safety and medical error reduction

13.2 Market challenges

High capital acquisition expenditures and infrastructure costs
Faculty resistance and interoperability system friction
Rapid technological obsolescence and validation constraints

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Integration of generative AI and adaptive learning
Accelerated adoption of extended reality and VR simulations
Expansion of cloud-hosted LMS and EHR educational platforms

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 3B Scientific GmbH

3B Scientific GmbH - Overview
3B Scientific GmbH - Product / Service
3B Scientific GmbH - Key offerings
SWOT

15.5 Ascend Learning LLC

Ascend Learning LLC - Overview
Ascend Learning LLC - Product / Service
Ascend Learning LLC - Key offerings
SWOT

15.6 Elevate Healthcare Inc.

Elevate Healthcare Inc. - Overview
Elevate Healthcare Inc. - Product / Service
Elevate Healthcare Inc. - Key offerings
SWOT

15.7 Elsevier Ltd.

Elsevier Ltd. - Overview
Elsevier Ltd. - Product / Service
Elsevier Ltd. - Key offerings
SWOT

15.8 HealthStream Inc.

HealthStream Inc. - Overview
HealthStream Inc. - Product / Service
HealthStream Inc. - Key offerings
SWOT

15.9 Kyoto Kagaku Co. Ltd.

Kyoto Kagaku Co. Ltd. - Overview
Kyoto Kagaku Co. Ltd. - Product / Service
Kyoto Kagaku Co. Ltd. - Key offerings
SWOT

15.10 Laerdal Medical AS

Laerdal Medical AS - Overview
Laerdal Medical AS - Product / Service
Laerdal Medical AS - Key offerings
SWOT

15.11 Limbs and Things Ltd.

Limbs and Things Ltd. - Overview
Limbs and Things Ltd. - Product / Service
Limbs and Things Ltd. - Key offerings
SWOT

15.12 Mentice AB

Mentice AB - Overview
Mentice AB - Business segments
Mentice AB - Key offerings
Mentice AB - Segment focus
SWOT

15.13 Nasco Healthcare Inc.

Nasco Healthcare Inc. - Overview
Nasco Healthcare Inc. - Product / Service
Nasco Healthcare Inc. - Key offerings
SWOT

15.14 Osso VR Inc.

Osso VR Inc. - Overview
Osso VR Inc. - Product / Service
Osso VR Inc. - Key offerings
SWOT

15.15 Oxford Medical Simulation Ltd.

Oxford Medical Simulation Ltd. - Overview
Oxford Medical Simulation Ltd. - Product / Service
Oxford Medical Simulation Ltd. - Key offerings
SWOT

15.16 Surgical Science Sweden AB

Surgical Science Sweden AB - Overview
Surgical Science Sweden AB - Business segments
Surgical Science Sweden AB - Key offerings
Surgical Science Sweden AB - Segment focus
SWOT

15.17 VirtaMed AG

VirtaMed AG - Overview
VirtaMed AG - Product / Service
VirtaMed AG - Key offerings
SWOT

15.18 Wolters Kluwer NV

Wolters Kluwer NV - Overview
Wolters Kluwer NV - Business segments
Wolters Kluwer NV - Key news
Wolters Kluwer NV - Key offerings
Wolters Kluwer NV - Segment focus
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Healthcare Education Solutions market growth will increase by USD 7797.4 million during 2026-2030.

The Healthcare Education Solutions market is expected to grow at a CAGR of 9.9% during 2026-2030.

Healthcare Education Solutions market is segmented by Delivery (Classroom-based, E-learning) End-user (Physician, Non-physician) Application (Cardiology, Radiology, Neurology, Pediatrics, Others)

3B Scientific GmbH, Amboss GmbH, Ascend Learning LLC, Elevate Healthcare Inc., Elsevier Ltd., Gaumard Scientific Co. Inc., HealthStream Inc., Kyoto Kagaku Co. Ltd., Laerdal Medical AS, Limbs and Things Ltd., Mentice AB, Nasco Healthcare Inc., Osso VR Inc., Oxford Medical Simulation Ltd., Simulab Corp., SimX Inc, Surgical Science Sweden AB, Trucorp Ltd., VirtaMed AG, Wolters Kluwer NV are a few of the key vendors in the Healthcare Education Solutions market.

North America will register the highest growth rate of 32% among the other regions. Therefore, the Healthcare Education Solutions market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Australia, Indonesia, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Surging global shortage of skilled healthcare professionals is the driving factor this market.

The Healthcare Education Solutions market vendors should focus on grabbing business opportunities from the Delivery segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA