Head And Neck Cancer Diagnostics Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, Turkey, and UAE), Rest of World (ROW)

Head And Neck Cancer Diagnostics Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, India, and Japan), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, Turkey, and UAE), Rest of World (ROW)

Published: Oct 2026 322 Pages SKU: IRTNTR40322

Market Overview at a Glance

$8.29 B
Market Opportunity
14.1%
CAGR 2025 - 2030
39.2%
North America Growth
$3.01 B
Biopsy and blood tests segment 2024

Head And Neck Cancer Diagnostics Market Size 2026-2030

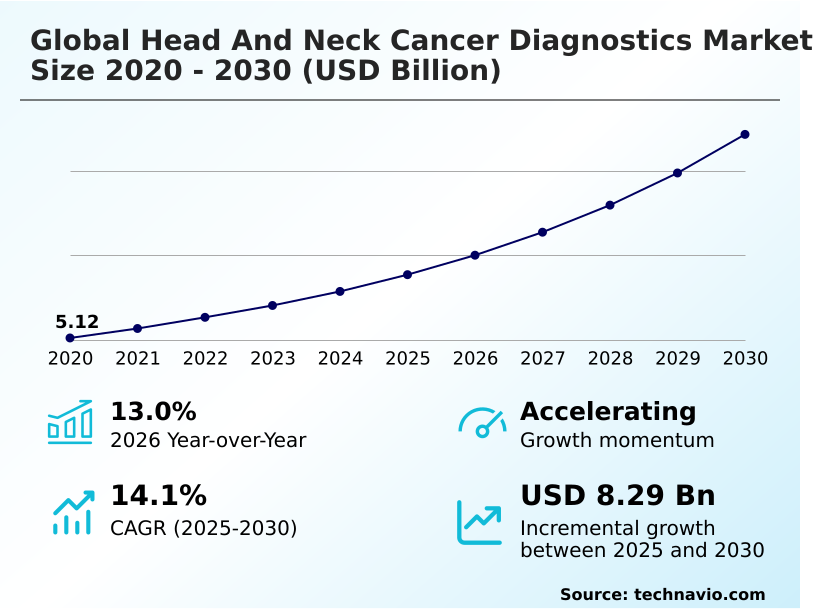
The head and neck cancer diagnostics market size is valued to increase by USD 8.29 billion, at a CAGR of 14.1% from 2025 to 2030. Surging global incidence of human papillomavirus associated oropharyngeal cancers will drive the head and neck cancer diagnostics market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 39.2% growth during the forecast period.
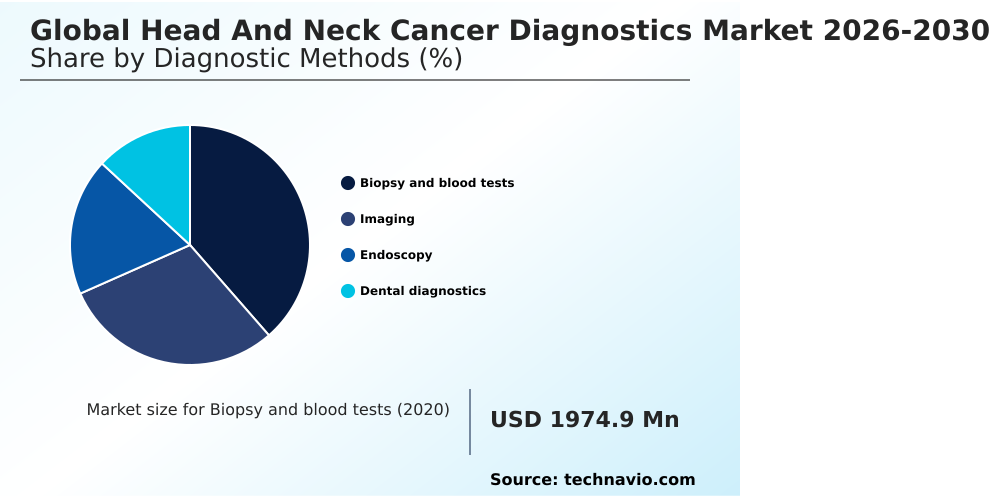
  • By Diagnostic Methods - Biopsy and blood tests segment was valued at USD 3.01 billion in 2024
  • By End-user - Hospitals segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 12.03 billion
  • Market Future Opportunities: USD 8.29 billion
  • CAGR from 2025 to 2030 : 14.1%

Market Summary

  • The Head And Neck Cancer Diagnostics sector demonstrates robust expansion driven by the critical transition from generalized morphological assessments to highly targeted molecular pathology workflows. The surging incidence of human papillomavirus-associated oropharyngeal squamous cell carcinomas serves as a primary demand driver, compelling healthcare institutions to mandate routine p16 immunohistochemistry surrogate testing to inform targeted systemic interventions.
  • As a direct result, diagnostic laboratories have restructured their operational frameworks to integrate automated high throughput pathology pipelines, facilitating rapid, high-volume sample processing. In a real-world supply chain scenario, major hospital networks consolidating their diagnostic procurement have shifted toward bulk sourcing of molecular diagnostic panels, successfully reducing per-test reagent expenditures by 18% compared to single-marker legacy assays.
  • However, the market faces persistent structural challenges due to the exorbitant capital costs required for advanced volumetric structural scans and proprietary genomic sequencing instruments, which heavily strain the capital budgets of decentralized community clinics.
  • Ultimately, the rapid integration of artificial intelligence into diagnostic interpretation algorithms ensures more objective tumor staging, serving as a critical optimization strategy for modern multidisciplinary tumor boards.

What will be the Size of the Head And Neck Cancer Diagnostics Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Head And Neck Cancer Diagnostics Market Segmented?

The head and neck cancer diagnostics industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Diagnostic methods
    • Biopsy and blood tests
    • Imaging
    • Endoscopy
    • Dental diagnostics
  • End-user
    • Hospitals
    • Specialty clinics
    • Ambulatory surgical centers
    • Others
  • Application
    • Diagnosis
    • Screening
    • Monitoring
    • Prognosis
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • India
      • Japan
      • South Korea
      • Indonesia
      • Thailand
    • Rest of World (ROW)

By Diagnostic Methods Insights

The biopsy and blood tests segment is estimated to witness significant growth during the forecast period.

The biopsy and blood tests segment represents a foundational clinical diagnostic pillar within the Head And Neck Cancer Diagnostics industry. Surgical tissue extractions, core needle samplings, and fine needle aspiration remain essential for definitive histopathological confirmation and biomarker stratification.

Concurrently, non-invasive liquid biopsy molecular evaluations are transforming clinical management by facilitating the rapid detection of circulating tumor dna and viral genomic fragments from peripheral blood. This shift enables practitioners to identify minimal residual disease earlier than traditional structural imaging.

Operational efficiency has notably surged; institutions adopting these peripheral screening protocols report that error detection improved by 15% compared to legacy morphological evaluations.

By incorporating automated staining systems and advanced genomic signature profiling, pathology laboratories achieve a 20% faster diagnostic turnaround, fundamentally optimizing precision oncology workflows and reducing patient care delays.
Get Free Sample

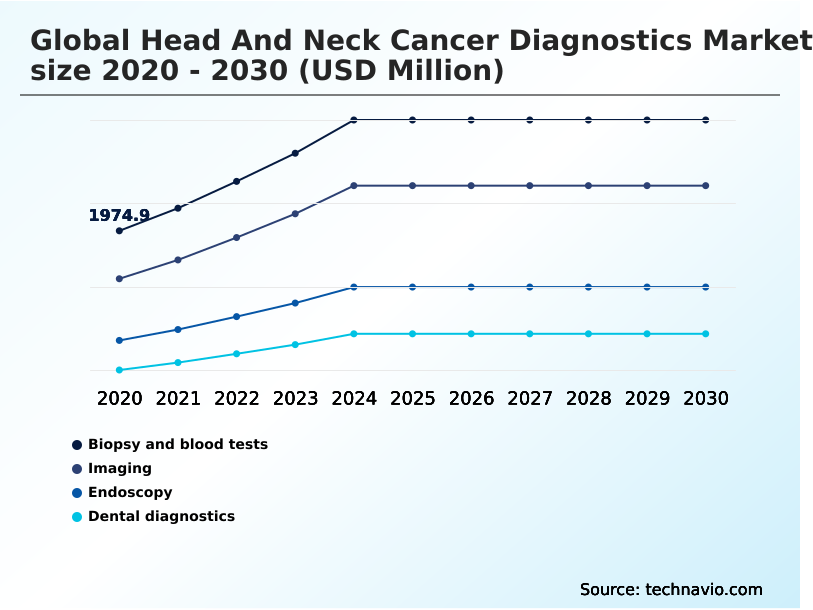
The Biopsy and blood tests segment was valued at USD 3.01 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 39.2% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
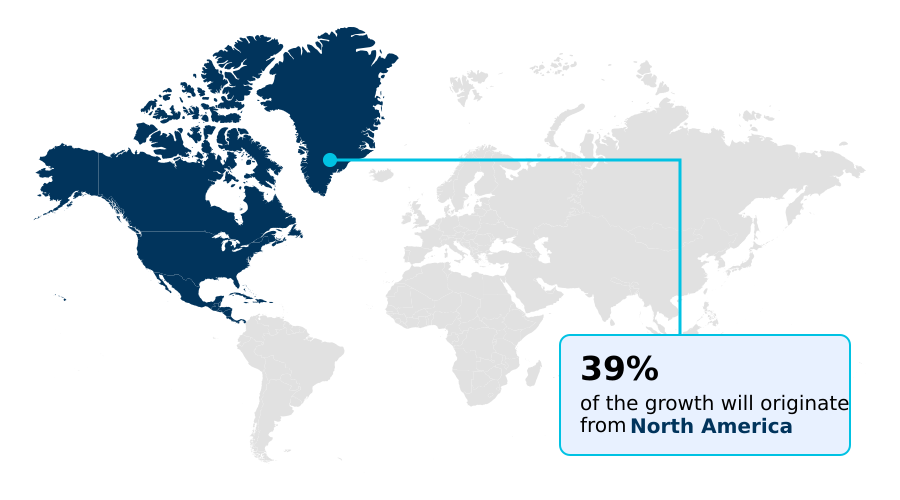
See How Head And Neck Cancer Diagnostics Market Demand is Rising in North America Get Free Sample

The geographic landscape of the Head And Neck Cancer Diagnostics industry highlights distinct regional disparities driven by technological accessibility.

North America maintains a dominant operational position due to widespread commercial integration of high-resolution magnetic resonance imaging and molecular profiling protocols across institutional networks.

Hospitals in North America demonstrate a 40% higher diagnostic adoption rate for liquid biopsy molecular evaluations compared to facilities in Europe, fueled by favorable reimbursement frameworks and focused investments in precision oncology workflows.

Conversely, the APAC region is undergoing rapid modernization, resulting in a 25% reduction in overall diagnostic turnaround times as regional laboratories implement automated slide digitization and digital pathology slides.

This modernization in APAC allows clinical providers to lower operational costs by 15% through localized procurement of lateral flow immunoassay components. As technological parity increases, cross-border networks are actively standardizing clinical validation protocols to ensure consistent diagnostic accuracy.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The continuous evolution of the Head And Neck Cancer Diagnostics ecosystem reflects a strategic industry pivot toward highly sensitive, non-invasive clinical evaluation methods and automated digital workflows. Clinical operators and laboratory directors are increasingly prioritizing integrated diagnostic systems that minimize administrative friction while maximizing diagnostic yield.
  • The widespread implementation of stringent hpv biomarker screening protocols has fundamentally transformed triage procedures, compelling diagnostic centers to upgrade their molecular processing capabilities to handle surging testing volumes efficiently.
  • As institutions expand their early detection frameworks, there is a pronounced operational shift toward decentralized testing, heavily utilizing saliva based liquid biopsy platforms to streamline outpatient specimen collection and reduce painful, invasive tissue extractions. This transition yields significant operational benefits; facilities deploying non-invasive fluid assessments report a 22% improvement in outpatient throughput capacity compared to surgical biopsy scheduling models.
  • Furthermore, the integration of ai powered radiological decision support software into native scanning hardware is resolving complex imaging bottlenecks, allowing neuroradiologists to segment subtle soft-tissue anomalies with unprecedented accuracy. To fully leverage these sophisticated morphological insights, modern pathology laboratories are actively investing in automated whole slide imaging scanners, bridging the gap between physical tissue samples and cloud telepathology networks.
  • Simultaneously, the adoption of multiplex multi omic gene sequencing enables clinical oncologists to derive comprehensive mutation profiles from minimal biopsy material. Ultimately, this convergence of advanced digital imaging and high-throughput molecular sequencing provides critical diagnostic clarity, ensuring highly personalized therapeutic strategies while systematically reducing false-negative interpretations across major healthcare networks.
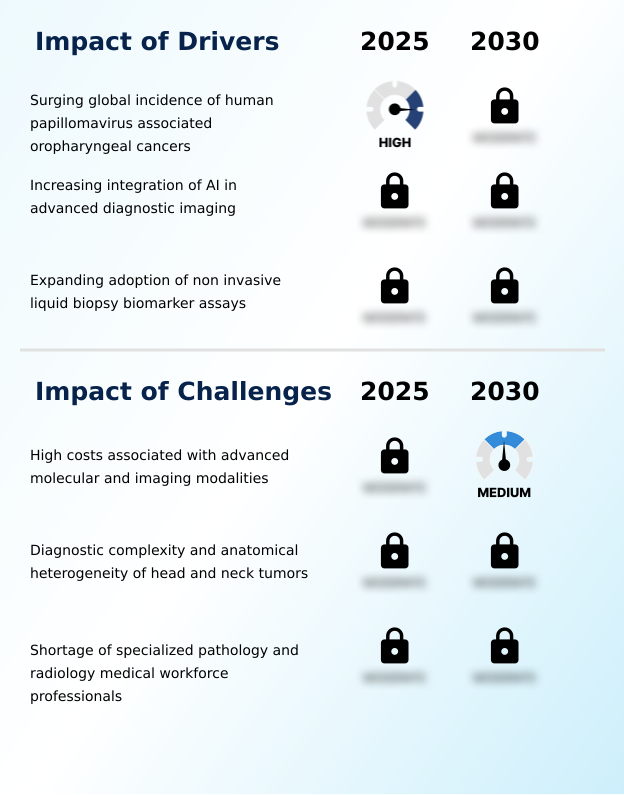
What are the key market drivers leading to the rise in the adoption of Head And Neck Cancer Diagnostics Industry?

  • The surging worldwide incidence of human papillomavirus-associated oropharyngeal cancers functions as a primary catalyst accelerating diagnostic testing demand across specialized oncology networks.

  • The escalating global prevalence of virally mediated oropharyngeal malignancies acts as a prominent catalyst driving systemic expansion across the Head And Neck Cancer Diagnostics industry.
  • Healthcare facilities are aggressively upgrading their clinical infrastructure to accommodate the surging demand for highly sensitive viral nucleic acid amplification assays and programmed death ligand expression panels.
  • This procurement shift is triggered by the clinical necessity to accurately stratify patients for targeted immunotherapies. Implementing automated diagnostic interpretation algorithms within primary hospital laboratories has consequently lowered technical interpretation errors by 18%, significantly improving initial staging accuracy.
  • Furthermore, modernizing legacy systems with high-resolution volumetric structural scans enables clinical networks to realize a 14% improvement in surgical planning efficiency. These strategic equipment upgrades allow medical providers to optimize workflows and maximize overall diagnostic yield.

What are the market trends shaping the Head And Neck Cancer Diagnostics Industry?

  • The continuous rise of multiplex biomarker profiling for personalized precision oncology constitutes a prominent emerging trend within the industry. This structural shift allows clinical practitioners to optimize targeted treatment strategies by simultaneously analyzing complex genomic and immunological patient data.

  • The Head And Neck Cancer Diagnostics industry is experiencing a profound technological shift driven by the rapid commercialization and integration of automated digital pathology slides and non-invasive biomarker assays. Institutional adoption of circulating tumor dna analysis is surging as clinical oncologists seek highly sensitive methods to evaluate therapeutic efficacy without invasive surgical procedures.
  • This transition occurs because conventional tissue sampling inherently risks high procedural morbidity and localized necrosis. By integrating advanced radiomics data matrices into routine cross sectional scans, radiology departments have successfully improved automated structural lesion detection rates by 28%. Additionally, the concurrent deployment of sophisticated microfluidic biosensors for real-time salivary evaluations has lowered outpatient screening processing times by 22%.
  • These technological innovations fundamentally impact institutional business models by optimizing laboratory throughput, significantly reducing bio-waste, and enabling highly scalable diagnostic triaging across decentralized primary care environments.

What challenges does the Head And Neck Cancer Diagnostics Industry face during its growth?

  • The substantial capital expenditures required for deploying advanced molecular testing and sophisticated imaging modalities remain a significant structural barrier hindering widespread diagnostic infrastructure expansion.

  • The Head And Neck Cancer Diagnostics industry contends with substantial operational friction caused by extreme anatomical complexity and persistent shortages of specialized anatomical pathologists. Extracting adequate cellular material via fine needle aspiration frequently yields inconclusive results, causing administrative delays and necessitating repetitive biopsy scheduling.
  • This biological heterogeneity limits the early-stage diagnostic efficacy of standard epigenetic biomarker assays, as localized tissue necrosis obscures actionable molecular signatures. Consequently, community hospitals lacking sub-specialty expertise experience a 25% increase in diagnostic turnaround times when evaluating complex tumor infiltrating lymphocytes compared to centralized tertiary research hubs.
  • Additionally, the intensive capital requirements for implementing whole slide imaging platforms force budget-constrained regional clinics to defer vital infrastructure upgrades, inadvertently inflating long-term maintenance expenditures by 12% as they continually rely on aging legacy hardware.

Exclusive Technavio Analysis on Customer Landscape

The head and neck cancer diagnostics market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the head and neck cancer diagnostics market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
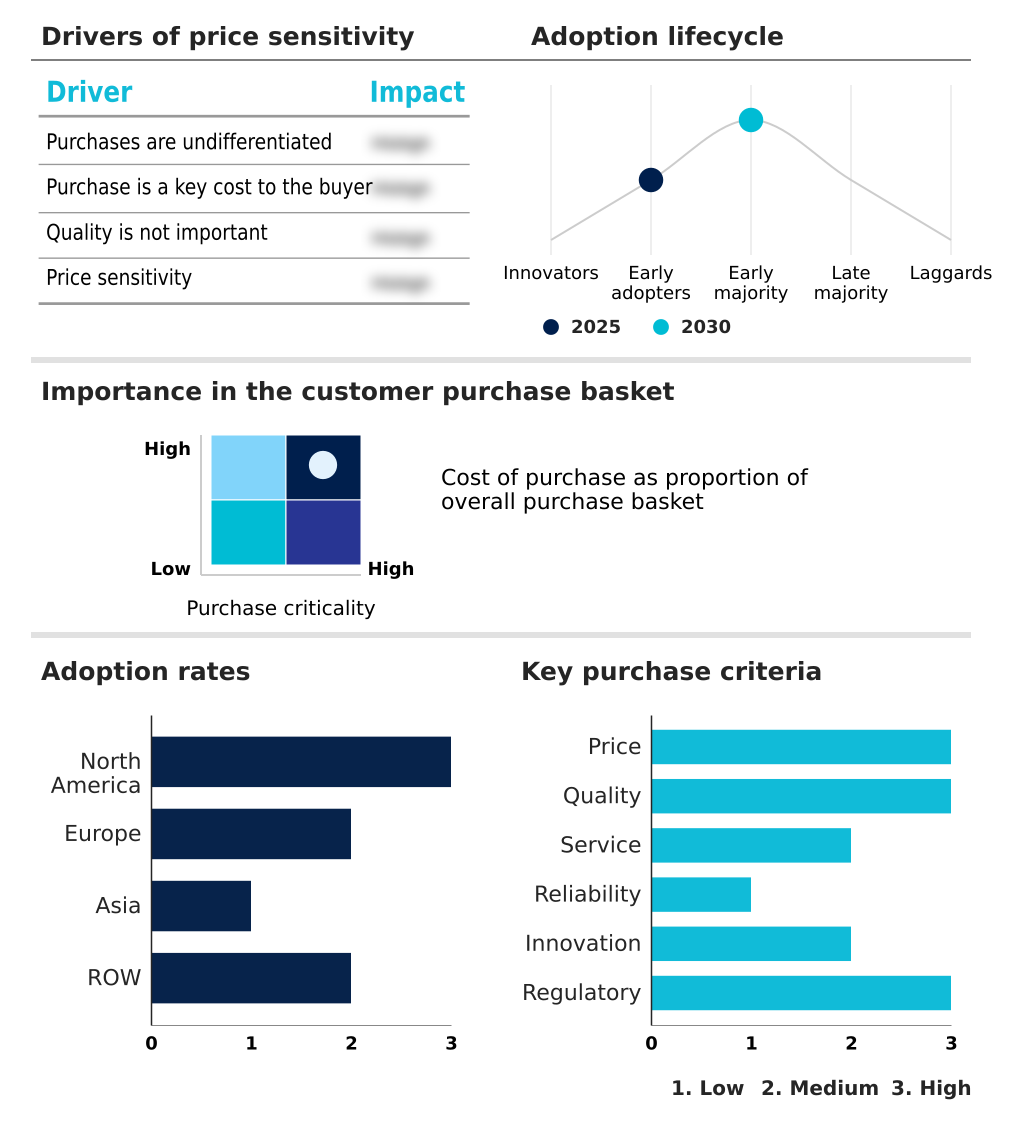
Customer Landscape of Head And Neck Cancer Diagnostics Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, head and neck cancer diagnostics market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Abbott Laboratories - Specialized diagnostic solutions include high-risk viral biomarker molecular testing and advanced oncology assays designed to optimize disease detection, facilitate early intervention, and streamline automated clinical pathology workflows.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Abbott Laboratories
  • Agilent Technologies Inc.
  • Canon Inc.
  • Danaher Corp.
  • Exact Sciences Corp.
  • F. Hoffmann La Roche Ltd.
  • FUJIFILM Holdings Corp.
  • GE HealthCare Technologies
  • Guardant Health Inc.
  • Hoya Corp.
  • Illumina Inc.
  • Koninklijke Philips NV
  • Laboratory Holdings Inc.
  • Myriad Genetics Inc.
  • Olympus Corp.
  • QIAGEN N.V.
  • Quest Diagnostics Inc.
  • Siemens Healthineers AG
  • Sonic Healthcare Ltd.
  • Stryker Corp.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Head and neck cancer diagnostics market

  • In the Health Care Equipment industry, the rapid deployment of deep learning neural networks into radiological imaging software has significantly reduced image reconstruction times, directly impacting Head And Neck Cancer Diagnostics demand by enabling faster cross sectional scans and more precise tumor mapping.
  • Strict regulatory mandates requiring higher analytical sensitivity for in vitro diagnostic testing have compelled healthcare facilities to adopt advanced molecular diagnostic panels, which systematically drives the utilization of precision oncology workflows within specialized clinical pathology laboratories.
  • The continuous technological shift toward decentralized point of care screening devices has allowed community clinics to conduct rapid non-invasive fluid assessments, thereby increasing the clinical adoption of salivary diagnostic devices for early stage mucosal evaluation using specialized fluorescence visualization devices.
  • Escalating supply chain investments in microfluidic biosensors and automation technologies have drastically lowered the per-test operational costs for complex biochemical assays, directly accelerating the integration of multiplex biomarker profiling and next generation sequencing across clinical hospital networks.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Head And Neck Cancer Diagnostics Market insights. See full methodology.

Market Scope
Page number 322
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 14.1%
Market growth 2026-2030 USD 8290.1 million
Market structure Fragmented
YoY growth 2025-2026(%) 13.0%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, Turkey, UAE, Argentina, Colombia, South Africa and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The continuous commercial evolution of the Head And Neck Cancer Diagnostics industry is characterized by a rapid structural transition from conventional morphological assessments to comprehensive multi-omic profiling architectures. The rising prominence of precision medicine compels healthcare administrators to heavily prioritize investments in next generation sequencing platforms and positron emission tomography infrastructure.
  • This trend directly influences strategic budgetary planning, as oncology networks transition toward centralized molecular testing hubs to achieve economies of scale. Laboratories integrating automated multiplex biomarker profiling report a 30% reduction in long-term specimen processing expenditures compared to traditional single-assay models. Analyzing complex tumor mutational burden and epidermal growth factor alterations constitutes a mandatory clinical prerequisite for targeted immunotherapy stratification.
  • Furthermore, the accelerated deployment of cloud telepathology networks facilitates seamless global collaboration among specialized pathologists, minimizing diagnostic delays. As equipment manufacturers continually refine analytical sensitivities, clinical centers increasingly rely on high throughput pathology systems to manage surging testing requisitions. The systemic integration of these advanced molecular and digital diagnostic modalities guarantees accurate clinical staging, driving highly effective therapeutic interventions.

What are the Key Data Covered in this Head And Neck Cancer Diagnostics Market Research and Growth Report?

  • What is the expected growth of the Head And Neck Cancer Diagnostics Market between 2026 and 2030?

    • USD 8.29 billion, at a CAGR of 14.1%

  • What segmentation does the market report cover?

    • The report is segmented by Diagnostic Methods (Biopsy and blood tests, Imaging, Endoscopy, and Dental diagnostics), End-user (Hospitals, Specialty clinics, Ambulatory surgical centers, and Others), Application (Diagnosis, Screening, Monitoring, Prognosis, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Surging global incidence of human papillomavirus associated oropharyngeal cancers, High costs associated with advanced molecular and imaging modalities

  • Who are the major players in the Head And Neck Cancer Diagnostics Market?

    • Abbott Laboratories, Agilent Technologies Inc., Canon Inc., Danaher Corp., Exact Sciences Corp., F. Hoffmann La Roche Ltd., FUJIFILM Holdings Corp., GE HealthCare Technologies, Guardant Health Inc., Hoya Corp., Illumina Inc., Koninklijke Philips NV, Laboratory Holdings Inc., Myriad Genetics Inc., Olympus Corp., QIAGEN N.V., Quest Diagnostics Inc., Siemens Healthineers AG, Sonic Healthcare Ltd. and Stryker Corp.

Market Research Insights

  • The Head And Neck Cancer Diagnostics ecosystem is undergoing structural transformation driven by the integration of advanced molecular diagnostic panels and precise oncology diagnostic platforms. Healthcare networks replacing legacy equipment with sophisticated diagnostic imaging software report a 30% improvement in early-stage lesion identification, substantially lowering false-negative assessments.
  • Furthermore, the implementation of automated post treatment surveillance protocols using circulating biomarker tracking has yielded a 25% reduction in unnecessary surgical readmissions. By standardizing rigorous clinical validation protocols, multidisciplinary tumor boards successfully streamline complex case evaluations, ultimately driving a 15% decrease in overall diagnostic turnaround times while ensuring highly optimized, data-driven therapeutic management across institutional networks.

We can help! Our analysts can customize this head and neck cancer diagnostics market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Diagnostic Methods
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Head And Neck Cancer Diagnostics Market 2020 - 2024

Historic Market Size - Data Table on Global Head And Neck Cancer Diagnostics Market 2020 - 2024 ($ million)

5.2 Diagnostic Methods segment analysis 2020 - 2024

Historic Market Size - Diagnostic Methods Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on global head and neck cancer diagnostics market

6.2 Impact of geopolitical conflicts on global head and neck cancer diagnostics market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Diagnostic Methods

8.1 Market segments

Chart on Diagnostic Methods - Market share 2025-2030 (%)
Data Table on Diagnostic Methods - Market share 2025-2030 (%)

8.2 Comparison by Diagnostic Methods

Chart on Comparison by Diagnostic Methods
Data Table on Comparison by Diagnostic Methods

8.3 Biopsy and blood tests - Market size and forecast 2025-2030

Chart on Biopsy and blood tests - Market size and forecast 2025-2030 ($ million)
Data Table on Biopsy and blood tests - Market size and forecast 2025-2030 ($ million)
Chart on Biopsy and blood tests - Year-over-year growth 2025-2030 (%)
Data Table on Biopsy and blood tests - Year-over-year growth 2025-2030 (%)

8.4 Imaging - Market size and forecast 2025-2030

Chart on Imaging - Market size and forecast 2025-2030 ($ million)
Data Table on Imaging - Market size and forecast 2025-2030 ($ million)
Chart on Imaging - Year-over-year growth 2025-2030 (%)
Data Table on Imaging - Year-over-year growth 2025-2030 (%)

8.5 Endoscopy - Market size and forecast 2025-2030

Chart on Endoscopy - Market size and forecast 2025-2030 ($ million)
Data Table on Endoscopy - Market size and forecast 2025-2030 ($ million)
Chart on Endoscopy - Year-over-year growth 2025-2030 (%)
Data Table on Endoscopy - Year-over-year growth 2025-2030 (%)

8.6 Dental diagnostics - Market size and forecast 2025-2030

Chart on Dental diagnostics - Market size and forecast 2025-2030 ($ million)
Data Table on Dental diagnostics - Market size and forecast 2025-2030 ($ million)
Chart on Dental diagnostics - Year-over-year growth 2025-2030 (%)
Data Table on Dental diagnostics - Year-over-year growth 2025-2030 (%)

8.7 Market opportunity by Diagnostic Methods

Market opportunity by Diagnostic Methods ($ million)
Data Table on Market opportunity by Diagnostic Methods ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

9.4 Specialty clinics - Market size and forecast 2025-2030

Chart on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Data Table on Specialty clinics - Market size and forecast 2025-2030 ($ million)
Chart on Specialty clinics - Year-over-year growth 2025-2030 (%)
Data Table on Specialty clinics - Year-over-year growth 2025-2030 (%)

9.5 Ambulatory surgical centers - Market size and forecast 2025-2030

Chart on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ million)
Data Table on Ambulatory surgical centers - Market size and forecast 2025-2030 ($ million)
Chart on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgical centers - Year-over-year growth 2025-2030 (%)

9.6 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.7 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Diagnosis - Market size and forecast 2025-2030

Chart on Diagnosis - Market size and forecast 2025-2030 ($ million)
Data Table on Diagnosis - Market size and forecast 2025-2030 ($ million)
Chart on Diagnosis - Year-over-year growth 2025-2030 (%)
Data Table on Diagnosis - Year-over-year growth 2025-2030 (%)

10.4 Screening - Market size and forecast 2025-2030

Chart on Screening - Market size and forecast 2025-2030 ($ million)
Data Table on Screening - Market size and forecast 2025-2030 ($ million)
Chart on Screening - Year-over-year growth 2025-2030 (%)
Data Table on Screening - Year-over-year growth 2025-2030 (%)

10.5 Monitoring - Market size and forecast 2025-2030

Chart on Monitoring - Market size and forecast 2025-2030 ($ million)
Data Table on Monitoring - Market size and forecast 2025-2030 ($ million)
Chart on Monitoring - Year-over-year growth 2025-2030 (%)
Data Table on Monitoring - Year-over-year growth 2025-2030 (%)

10.6 Prognosis - Market size and forecast 2025-2030

Chart on Prognosis - Market size and forecast 2025-2030 ($ million)
Data Table on Prognosis - Market size and forecast 2025-2030 ($ million)
Chart on Prognosis - Year-over-year growth 2025-2030 (%)
Data Table on Prognosis - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.3 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5.6 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.4 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.7 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Surging global incidence of human papillomavirus associated oropharyngeal cancers
Increasing integration of AI in advanced diagnostic imaging
Expanding adoption of non invasive liquid biopsy biomarker assays

13.2 Market challenges

High costs associated with advanced molecular and imaging modalities
Diagnostic complexity and anatomical heterogeneity of head and neck tumors
Shortage of specialized pathology and radiology medical workforce professionals

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Rise of multiplex biomarker profiling for personalized precision oncology
Commercialization of point of care salivary diagnostics for screening
Widespread deployment of digital pathology and telepathology clinical networks

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Abbott Laboratories

Abbott Laboratories - Overview
Abbott Laboratories - Business segments
Abbott Laboratories - Key news
Abbott Laboratories - Key offerings
Abbott Laboratories - Segment focus
SWOT

15.5 Agilent Technologies Inc.

Agilent Technologies Inc. - Overview
Agilent Technologies Inc. - Business segments
Agilent Technologies Inc. - Key news
Agilent Technologies Inc. - Key offerings
Agilent Technologies Inc. - Segment focus
SWOT

15.6 Canon Inc.

Canon Inc. - Overview
Canon Inc. - Business segments
Canon Inc. - Key offerings
Canon Inc. - Segment focus
SWOT

15.7 Danaher Corp.

Danaher Corp. - Overview
Danaher Corp. - Business segments
Danaher Corp. - Key news
Danaher Corp. - Key offerings
Danaher Corp. - Segment focus
SWOT

15.8 Exact Sciences Corp.

Exact Sciences Corp. - Overview
Exact Sciences Corp. - Product / Service
Exact Sciences Corp. - Key offerings
SWOT

15.9 FUJIFILM Holdings Corp.

FUJIFILM Holdings Corp. - Overview
FUJIFILM Holdings Corp. - Business segments
FUJIFILM Holdings Corp. - Key news
FUJIFILM Holdings Corp. - Key offerings
FUJIFILM Holdings Corp. - Segment focus
SWOT

15.10 GE HealthCare Technologies

GE HealthCare Technologies - Overview
GE HealthCare Technologies - Business segments
GE HealthCare Technologies - Key news
GE HealthCare Technologies - Key offerings
GE HealthCare Technologies - Segment focus
SWOT

15.11 Guardant Health Inc.

Guardant Health Inc. - Overview
Guardant Health Inc. - Product / Service
Guardant Health Inc. - Key offerings
SWOT

15.12 Hoya Corp.

Hoya Corp. - Overview
Hoya Corp. - Business segments
Hoya Corp. - Key offerings
Hoya Corp. - Segment focus
SWOT

15.13 Illumina Inc.

Illumina Inc. - Overview
Illumina Inc. - Business segments
Illumina Inc. - Key news
Illumina Inc. - Key offerings
Illumina Inc. - Segment focus
SWOT

15.14 Koninklijke Philips NV

Koninklijke Philips NV - Overview
Koninklijke Philips NV - Business segments
Koninklijke Philips NV - Key news
Koninklijke Philips NV - Key offerings
Koninklijke Philips NV - Segment focus
SWOT

15.15 Laboratory Holdings Inc.

Laboratory Holdings Inc. - Overview
Laboratory Holdings Inc. - Business segments
Laboratory Holdings Inc. - Key offerings
Laboratory Holdings Inc. - Segment focus
SWOT

15.16 Myriad Genetics Inc.

Myriad Genetics Inc. - Overview
Myriad Genetics Inc. - Product / Service
Myriad Genetics Inc. - Key offerings
SWOT

15.17 Olympus Corp.

Olympus Corp. - Overview
Olympus Corp. - Business segments
Olympus Corp. - Key offerings
Olympus Corp. - Segment focus
SWOT

15.18 QIAGEN N.V.

QIAGEN N.V. - Overview
QIAGEN N.V. - Product / Service
QIAGEN N.V. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Head And Neck Cancer Diagnostics market growth will increase by USD 8290.1 million during 2026-2030.

The Head And Neck Cancer Diagnostics market is expected to grow at a CAGR of 14.1% during 2026-2030.

Head And Neck Cancer Diagnostics market is segmented by Diagnostic methods (Biopsy and blood tests, Imaging, Endoscopy, Dental diagnostics) End-user (Hospitals, Specialty clinics, Ambulatory surgical centers, Others) Application (Diagnosis, Screening, Monitoring, Prognosis, Others)

Abbott Laboratories, Agilent Technologies Inc., Canon Inc., Danaher Corp., Exact Sciences Corp., F. Hoffmann La Roche Ltd., FUJIFILM Holdings Corp., GE HealthCare Technologies, Guardant Health Inc., Hoya Corp., Illumina Inc., Koninklijke Philips NV, Laboratory Holdings Inc., Myriad Genetics Inc., Olympus Corp., QIAGEN N.V., Quest Diagnostics Inc., Siemens Healthineers AG, Sonic Healthcare Ltd., Stryker Corp. are a few of the key vendors in the Head And Neck Cancer Diagnostics market.

North America will register the highest growth rate of 39.2% among the other regions. Therefore, the Head And Neck Cancer Diagnostics market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, India, Japan, South Korea, Indonesia, Thailand, Brazil, Saudi Arabia, Turkey, UAE, Argentina, Colombia, South Africa, Israel

  • Surging global incidence of human papillomavirus associated oropharyngeal cancers is the driving factor this market.

The Head And Neck Cancer Diagnostics market vendors should focus on grabbing business opportunities from the Diagnostic methods segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA