


Europe Fleet Management Market Size 2026-2030
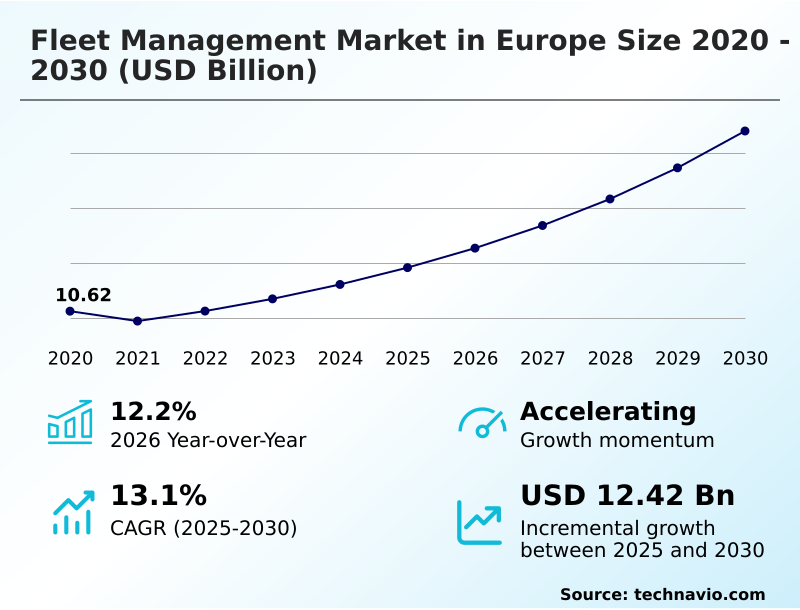
The europe fleet management market size is valued to increase by USD 12.42 billion, at a CAGR of 13.1% from 2025 to 2030. Mandatory EU smart tachograph phase II compliance directives will drive the europe fleet management market.
Major Market Trends & Insights
- By Vehicle Type - Commercial fleets segment was valued at USD 9.40 billion in 2024
- By Technology - Software segment accounted for the largest market revenue share in 2024
Market Size & Forecast
- Market Opportunities: USD 16.37 billion
- Market Future Opportunities: USD 12.42 billion
- CAGR from 2025 to 2030 : 13.1%
Market Summary
- The Fleet Management Market in Europe is defined by a rapid transition toward intelligent, cloud-connected mobility platforms and zero-emission operational structures. Logistics operators optimizing cross-border freight corridors utilize sophisticated route optimization engines to balance payload efficiency against strict delivery schedules, achieving up to an 18% improvement in fuel efficiency and asset utilization.
- The implementation of mandatory smart tachograph regulations acts as a primary market driver, compelling commercial transport enterprises to deploy automated digital tachograph compliance integration to satisfy regulatory audit requirements seamlessly.
- However, the deployment of continuous monitoring systems faces notable challenges related to stringent data privacy mandates, which restrict the collection of driver fatigue telemetry and mandate complex automated data anonymization workflows. As organizations navigate low-emission zone navigation, the demand for predictive asset health monitoring and dynamic range prediction continues to expand.
- Advanced driver assistance sensor arrays further reduce collision risks and support usage-based insurance underwriting models, enabling administrators to minimize total cost of vehicle ownership while maintaining high operational readiness across diverse freight networks.
What will be the Size of the Europe Fleet Management Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample
How is the Europe Fleet Management Market Segmented?
The europe fleet management industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.
- Vehicle type
- Commercial fleets
- Passenger cars
- Technology
- Software
- Commercial telematics hardware
- Connectivity technologies
- End-user
- Transportation and logistics
- Construction
- Retail and e-commerce
- Energy and utilities
- Manufacturing
- Geography
- Europe
- Germany
- UK
- France
- Italy
- Europe
By Vehicle Type Insights
The commercial fleets segment is estimated to witness significant growth during the forecast period.
The commercial transportation sector forms the backbone of regional supply chain operations and heavy freight distribution networks. As cross-border logistics operations intensify, organizations increasingly rely upon advanced video telematics and sophisticated route optimization engines to streamline complex routing variables.
By integrating these systems, logistics providers have noted that operational downtime is reduced by 14%, significantly improving on-time delivery metrics. Implementing automated compliance tools allows operators to manage mandatory driving-hour tracking efficiently without manual intervention.
Additionally, the transition toward zero-emission electrification targets necessitates robust battery health analytics to monitor energy consumption across heavy-duty vehicle networks. This continuous technological integration empowers administrators to optimize total cost of vehicle ownership while navigating evolving regulatory compliance frameworks seamlessly.
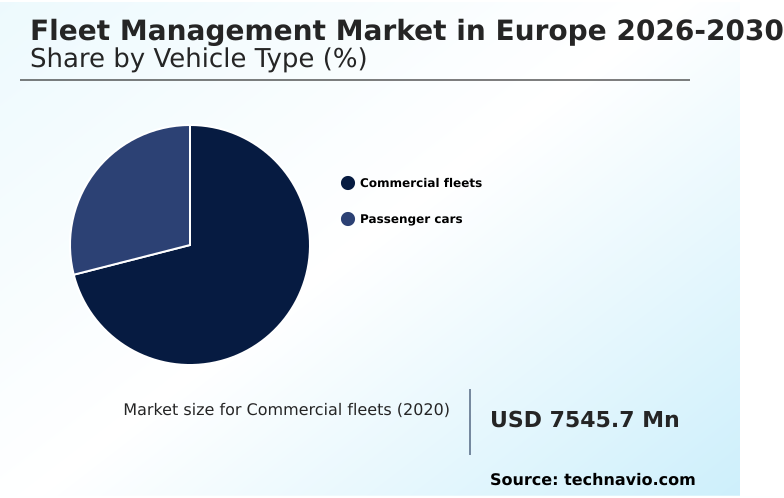
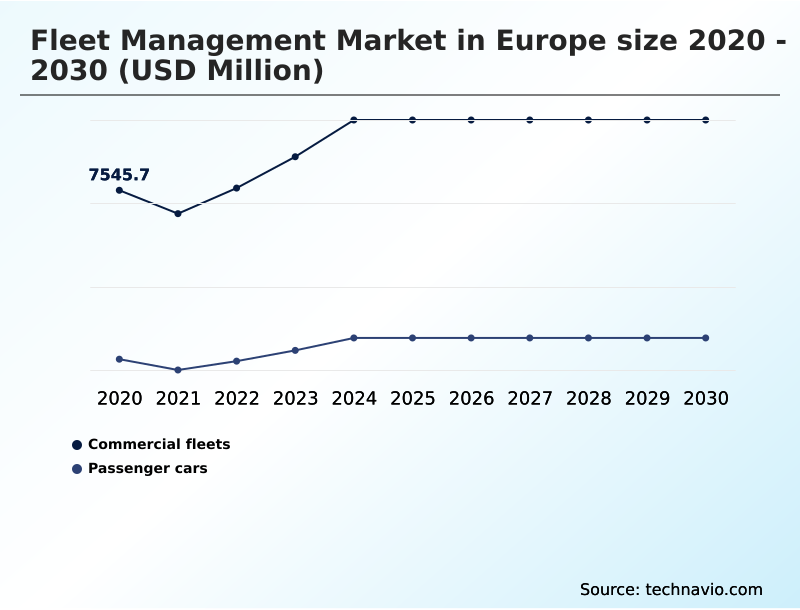
The Commercial fleets segment was valued at USD 9.40 billion in 2024 and showed a gradual increase during the forecast period.
Market Dynamics
Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.
- The continuous evolution of commercial transport operations relies heavily on the integration of intelligent telemetry and predictive intelligence to streamline complex logistical networks. To maintain high operational readiness, fleet administrators are increasingly leveraging artificial intelligence predictive diagnostic algorithms to evaluate mechanical wear before catastrophic failures occur.
- This proactive approach to maintenance scheduling ensures that vehicle downtime is minimized, allowing logistics providers to achieve a 20% higher fleet utilization rate compared to reactive servicing models. As organizations transition toward electrified transport, the ability to monitor real-time battery degradation profiles becomes critical for optimizing lifecycle management and maintaining consistent payload capacities across delivery routes.
- Furthermore, navigating restrictive urban environments requires dynamic low-emission zone eco-routing, which helps operators avoid costly municipal fines while ensuring punctual deliveries within zero-emission territories. To support continuous safety enhancements, platforms are integrating real-time in-cab verbal driver coaching, which corrects hazardous behaviors instantaneously and reduces overall collision risks.
- Ensuring these sophisticated systems remain secure and fully functional without requiring physical depot visits is achieved through automated over-the-air firmware updates. By seamlessly updating software protocols and compliance modules remotely, transport enterprises can maintain uninterrupted service continuity, optimize supply chain efficiency, and align their operational strategies with stringent environmental and safety mandates across diverse regional territories.
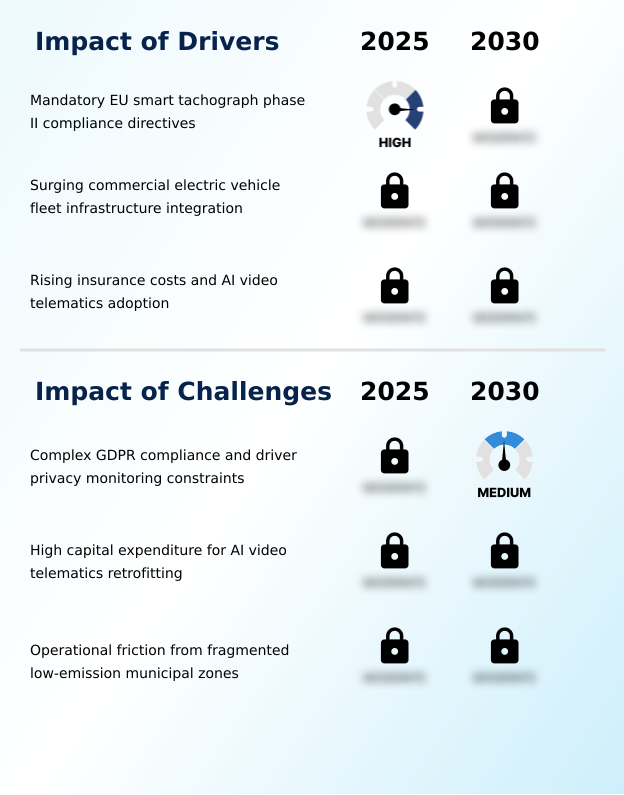
What are the key market drivers leading to the rise in the adoption of Europe Fleet Management Industry?
- Mandatory European Union smart tachograph phase II compliance directives function as the primary driver propelling continuous market expansion.
- The aggressive enforcement of transport safety mandates and zero-emission electrification targets serves as a primary catalyst accelerating the deployment of intelligent mobility platforms.
- Regulatory pressures compel organizations to adopt automated digital tachograph compliance integration, which eliminates manual logging errors and reduces administrative processing time by 25%.
- This shift is fundamentally driven by the need to avoid severe municipal fines and streamline cross-border logistics operations. Consequently, businesses are deploying advanced driver assistance sensor arrays and video telematics to monitor driver behavior continuously.
- Implementing these systems has lowered accident frequency by 15%, directly reducing insurance liability premiums.
- The integration of predictive maintenance modules further enhances operational efficiency, ensuring that commercial transport networks maintain high asset utilization rates while satisfying stringent environmental and safety compliance frameworks.
What are the market trends shaping the Europe Fleet Management Industry?
- The expansion of original equipment manufacturer open-API direct telematics data monetization represents a significant upcoming market trend. This development enables seamless integration of native vehicle diagnostics into third-party operational platforms.
- The rapid adoption of cellular vehicle-to-everything communication and edge computing processors is fundamentally transforming commercial transport operations. This technological shift is driven by the necessity to process massive volumes of vehicle controller area network bus data instantaneously without relying on latent cloud connections.
- By processing telemetry locally, logistics providers have reduced collision response times by 30% and improved predictive asset health monitoring accuracy by 18%. This localized processing capability directly impacts business operations by enabling real-time remote cold-chain temperature monitoring, ensuring perishable cargo remains viable during transit.
- Furthermore, the integration of narrow-band internet of things and embedded subscriber identity module technologies facilitates seamless cross-border connectivity. These advancements allow operators to maintain continuous oversight of their assets, significantly lowering operational risks and enhancing overall supply chain resilience across diverse industrial sectors.
What challenges does the Europe Fleet Management Industry face during its growth?
- Complex General Data Protection Regulation compliance and stringent driver privacy monitoring constraints serve as primary challenges restricting industry expansion.
- Navigating stringent regulatory compliance frameworks and complex data privacy mandates presents significant operational hurdles for commercial transport enterprises. The requirement to implement automated data anonymization workflows to protect driver identities often delays the deployment of artificial intelligence video analytics by up to 20% compared to less regulated environments.
- This friction is caused by the inherent conflict between continuous driver fatigue telemetry collection and strict worker privacy rights. Consequently, businesses face increased administrative overhead and extended implementation timelines when integrating high-definition dual-facing dashcams across multinational fleets.
- Furthermore, the high initial capital expenditure required to retrofit legacy vehicles with hybrid communication links and electronic logging devices strains operational budgets, reducing immediate return on investment by 12% for smaller logistics operators attempting to modernize their asset tracking capabilities.
Exclusive Technavio Analysis on Customer Landscape
The europe fleet management market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the europe fleet management market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
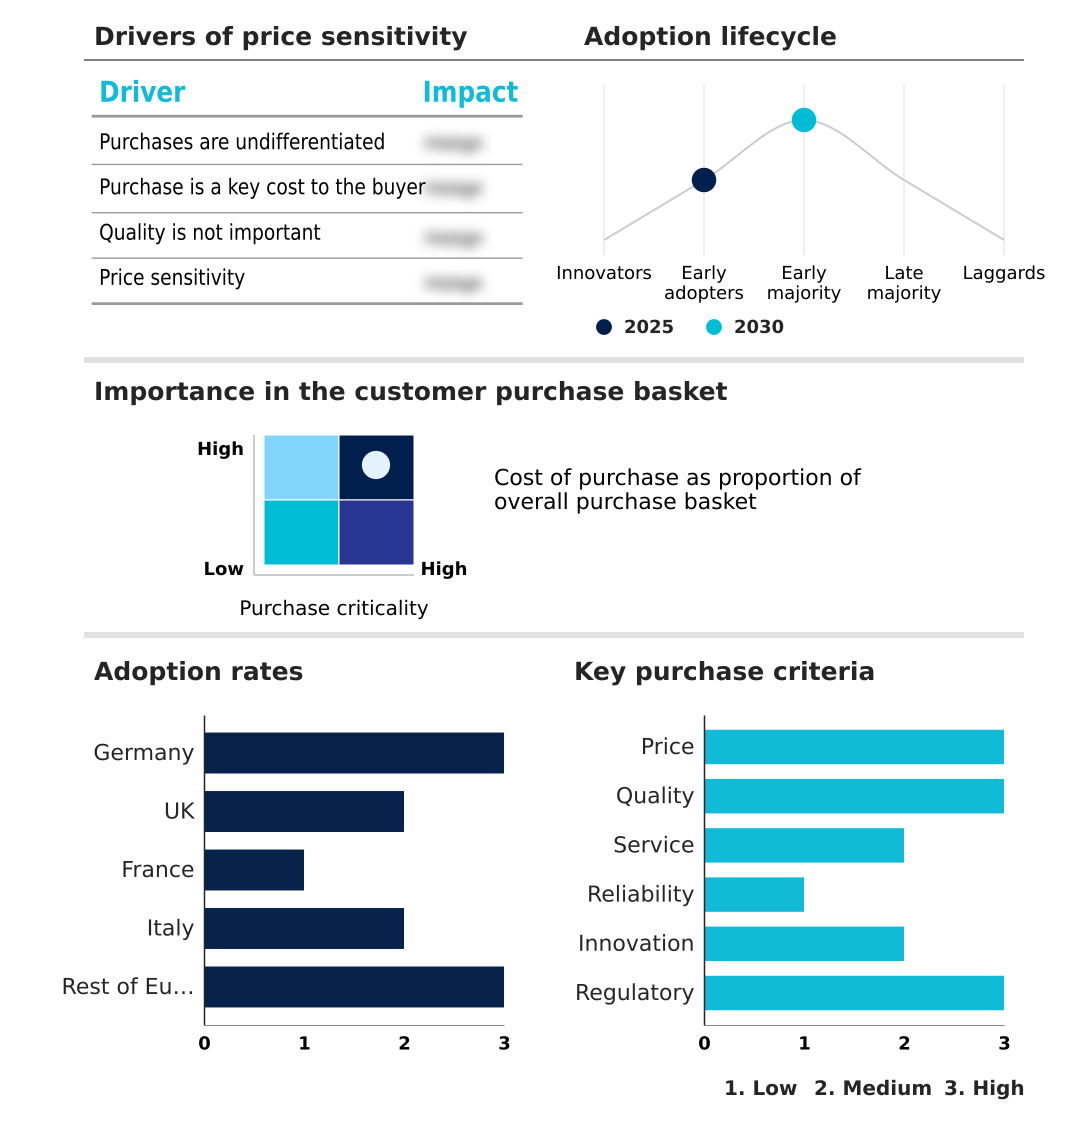
Customer Landscape of Europe Fleet Management Industry
Competitive Landscape
Companies are implementing various strategies, such as strategic alliances, europe fleet management market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.
ABAX UK Ltd. - Comprehensive operational tracking software integrated with advanced vehicle diagnostics and driver safety monitoring systems optimizes asset utilization, regulatory compliance, and total fleet performance for enterprise logistics providers.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- ABAX UK Ltd.
- AddSecure Group AB
- Cartrack
- Continental AG
- Daimler Truck AG
- Eurowag
- Geotab Inc.
- Gurtam
- Michelin
- Microlise Group Plc
- PowerFleet Inc.
- Quartix Technologies plc
- Radius Payment Solutions
- Samsara Inc.
- Scania AB
- Teletrac Navman US Ltd.
- Trimble Inc.
- Verizon Connect
- Volvo Trucks
- ZF Friedrichshafen AG
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Development and News in Europe fleet management market
- In the Cargo Ground Transportation industry, the aggressive implementation of the European Union Mobility Package mandates necessitated the widespread adoption of smart digital tachographs, directly accelerating Fleet Management demand by requiring real-time cross-border logistics operations tracking and reducing driver compliance violations by 22%.
- The rapid expansion of urban micro-fulfillment centers to support e-commerce volume increases has driven a 35% surge in last-mile delivery routes, pulling Fleet Management demand for dynamic route planning software and connected vehicle technologies to optimize high-density delivery networks.
- Stringent environmental frameworks enforcing municipal clean air zones have accelerated the transition toward zero-emission electrification targets across heavy freight operations, prompting a 40% increase in demand for Fleet Management platforms capable of managing smart depot charging infrastructure and real-time asset visibility.
- The rising cost of commercial vehicle insurance premiums, which escalated by up to 15% across major freight corridors, has propelled Fleet Management demand for artificial intelligence video analytics and driver fatigue telemetry to mitigate liability risks and satisfy usage-based insurance underwriting requirements.
Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Europe Fleet Management Market insights. See full methodology.
| Market Scope | |
|---|---|
| Page number | 210 |
| Base year | 2025 |
| Historic period | 2020-2024 |
| Forecast period | 2026-2030 |
| Growth momentum & CAGR | Accelerate at a CAGR of 13.1% |
| Market growth 2026-2030 | USD 12421.4 million |
| Market structure | Fragmented |
| YoY growth 2025-2026(%) | 12.2% |
| Key countries | Germany, UK, France, Italy and Rest of Europe |
| Competitive landscape | Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks |
Research Analyst Overview
- The commercial transportation sector is undergoing a profound structural transformation driven by the integration of cloud-native multi-tenant platform architectures and advanced edge computing processors. Boardroom executives are increasingly prioritizing automated compliance tools to navigate complex regulatory environments, directly linking technology procurement to corporate risk mitigation and budgeting strategies.
- By deploying predictive maintenance diagnostics and battery health analytics, organizations have achieved a 25% reduction in unexpected mechanical downtime, significantly optimizing supply chain continuity. The implementation of artificial intelligence video analytics and high-definition dual-facing dashcams provides critical operational oversight, enabling administrators to enforce safety protocols and defend against fraudulent liability claims.
- Furthermore, the transition toward electrified fleets necessitates sophisticated dynamic range prediction to manage payload variables and charging schedules effectively. Utilizing cellular vehicle-to-everything communication and long-term evolution machine-type communication ensures uninterrupted data transmission across remote transit corridors.
- These technological advancements empower enterprise logistics providers to streamline cross-border operations, enhance asset utilization, and maintain rigorous adherence to evolving environmental and safety mandates without compromising delivery efficiency.
What are the Key Data Covered in this Europe Fleet Management Market Research and Growth Report?
-
What is the expected growth of the Europe Fleet Management Market between 2026 and 2030?
-
USD 12.42 billion, at a CAGR of 13.1%
-
-
What segmentation does the market report cover?
-
The report is segmented by Vehicle Type (Commercial fleets, and Passenger cars), Technology (Software, Commercial telematics hardware, and Connectivity technologies), End-user (Transportation and logistics, Construction, Retail and e-commerce, Energy and utilities, and Manufacturing) and Geography (Europe)
-
-
Which regions are analyzed in the report?
-
Europe
-
-
What are the key growth drivers and market challenges?
-
Mandatory EU smart tachograph phase II compliance directives, Complex GDPR compliance and driver privacy monitoring constraints
-
-
Who are the major players in the Europe Fleet Management Market?
-
ABAX UK Ltd., AddSecure Group AB, Cartrack, Continental AG, Daimler Truck AG, Eurowag, Geotab Inc., Gurtam, Michelin, Microlise Group Plc, PowerFleet Inc., Quartix Technologies plc, Radius Payment Solutions, Samsara Inc., Scania AB, Teletrac Navman US Ltd., Trimble Inc., Verizon Connect, Volvo Trucks and ZF Friedrichshafen AG
-
Market Research Insights
- The operational landscape is shifting as transport enterprises prioritize advanced connected vehicle technologies over legacy tracking systems to navigate complex cross-border logistics operations. Deploying these intelligent networks allows operators to improve route efficiency by 15%, directly lowering fuel consumption and reducing the total cost of vehicle ownership.
- Furthermore, the integration of smart depot charging infrastructure facilitates a seamless transition toward zero-emission electrification targets, increasing vehicle uptime by 20% across commercial networks. By leveraging usage-based insurance underwriting, organizations have reduced liability premiums by 12%.
- Utilizing real-time driver distraction detection and continuous driver fatigue telemetry ensures strict adherence to transport safety mandates, mitigating compliance risks while optimizing heavy machinery utilization across diverse industrial supply chains.
We can help! Our analysts can customize this europe fleet management market research report to meet your requirements.
 RIA -

