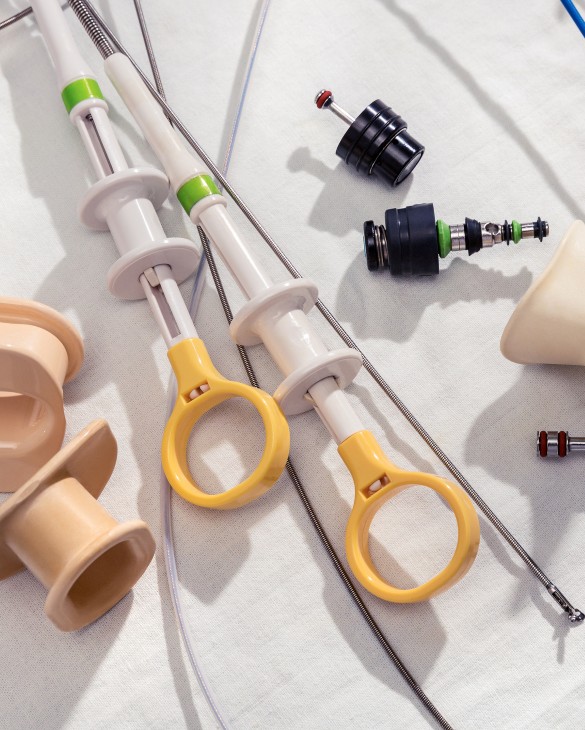
Endoscopic Closure Devices Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Endoscopic Closure Devices Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), Europe (Germany, UK, and France), Asia (China, Japan, and India), South America (Brazil, Argentina, and Colombia), Middle East and Africa (Saudi Arabia, UAE, and Turkey), Rest of World (ROW)

Published: Nov 2026 309 Pages SKU: IRTNTR41161

Market Overview at a Glance

$853.6 Mn
Market Opportunity
7.8%
CAGR 2025 - 2030
33.4%
North America Growth
$840.4 Mn
Endoscopic closure systems segment 2024

Endoscopic Closure Devices Market Size 2026-2030

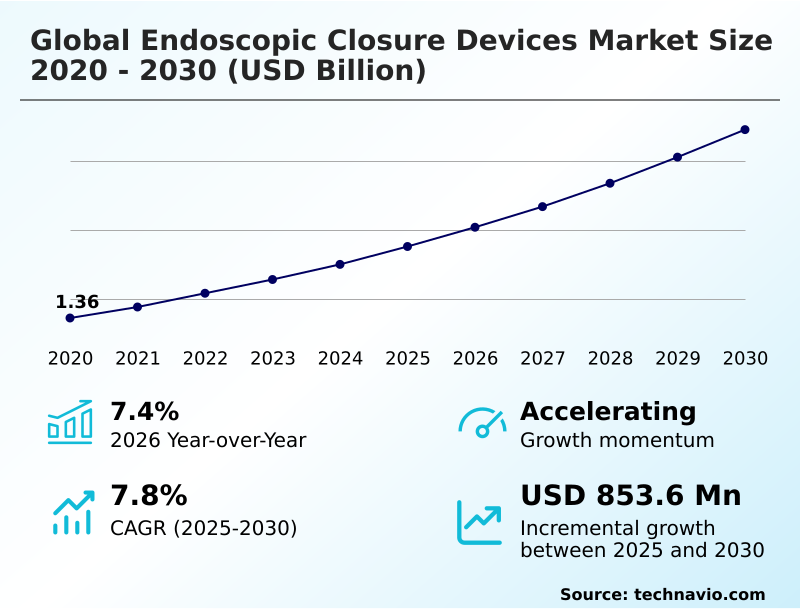
The endoscopic closure devices market size is valued to increase by USD 853.6 million, at a CAGR of 7.8% from 2025 to 2030. Expansion of specialized physician training infrastructure will drive the endoscopic closure devices market.

Major Market Trends & Insights

  • North America dominated the market and accounted for a 33.4% growth during the forecast period.
  • By Product - Endoscopic closure systems segment was valued at USD 840.4 million in 2024
  • By End-user - Hospitals segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 1.38 billion
  • Market Future Opportunities: USD 853.6 million
  • CAGR from 2025 to 2030 : 7.8%

Market Summary

  • The Endoscopic Closure Devices Market demonstrates rigorous operational momentum driven by the systemic shift toward minimally invasive therapeutic interventions across comprehensive healthcare networks. Hospital procurement committees actively optimize supply chain logistics by standardizing inventory around versatile, multi-fire tissue approximation platforms, reducing consumable waste by 18% during high-volume gastrointestinal procedures.
  • This strategic consolidation allows surgical suites to maximize procedural throughput while maintaining stringent patient safety standards. The establishment of dedicated physician simulation laboratories acts as a primary catalyst for industry advancement, enabling clinicians to acquire specialized technical proficiency and safely execute complex endoluminal repairs. Consequently, the reliance on advanced mechanical clipping systems expands rapidly.
  • Conversely, the inherent technical complexity of deploying sophisticated suturing hardware within narrow anatomical lumens presents a formidable operational limitation. Institutions face steep learning curves that restrict immediate, widespread adoption among general gastroenterologists.
  • Addressing these intricate mechanical demands requires continuous investment in ergonomic handle designs and automated deployment triggers to mitigate operator fatigue and secure consistent clinical outcomes across diverse patient populations.

What will be the Size of the Endoscopic Closure Devices Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Endoscopic Closure Devices Market Segmented?

The endoscopic closure devices industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Product
    • Endoscopic closure systems
    • Endoscopic clips
    • Others
  • End-user
    • Hospitals
    • Ambulatory surgery centers
    • Others
  • Application
    • Gastrointestinal surgery
    • Perforation and fistula closure
    • Post EMR
    • Stent fixation
    • Others
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Asia
      • China
      • Japan
      • India
      • South Korea
      • Thailand
      • Indonesia
    • Rest of World (ROW)

By Product Insights

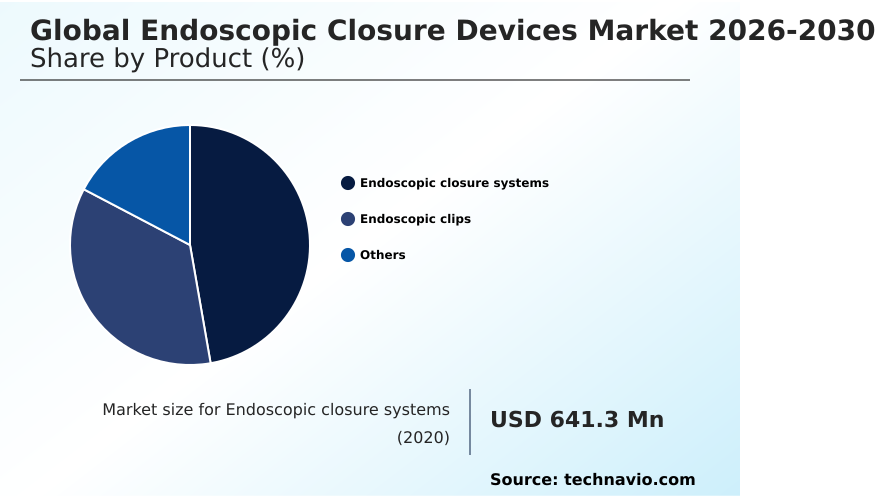
The endoscopic closure systems segment is estimated to witness significant growth during the forecast period.

Advanced mucosal band ligation mechanisms and detachable snare loops are fundamentally shifting interventional workflows by allowing precise defect repair capabilities in highly vascularized beds.

Facilities utilizing specialized endoscopic tissue sealants alongside mechanical systems observe a 15% reduction in postoperative leak rates compared to traditional standalone clipping. This transition enhances luminal stricture navigation, enabling physicians to secure complex resections with greater structural reliability.

As supply chains prioritize high-retention synthetic cyanoacrylate glues, procurement managers report a 22% improvement in overall procedural efficiency due to decreased device misfires.

The integration of ergonomic deployment handles and multi-fire clip delivery architectures minimizes operator fatigue, directly reducing average operating room turnover delays. Consequently, institutions seamlessly balance high-volume diagnostic throughput with the rising operational demand for robust endoluminal repair components.
Get Free Sample

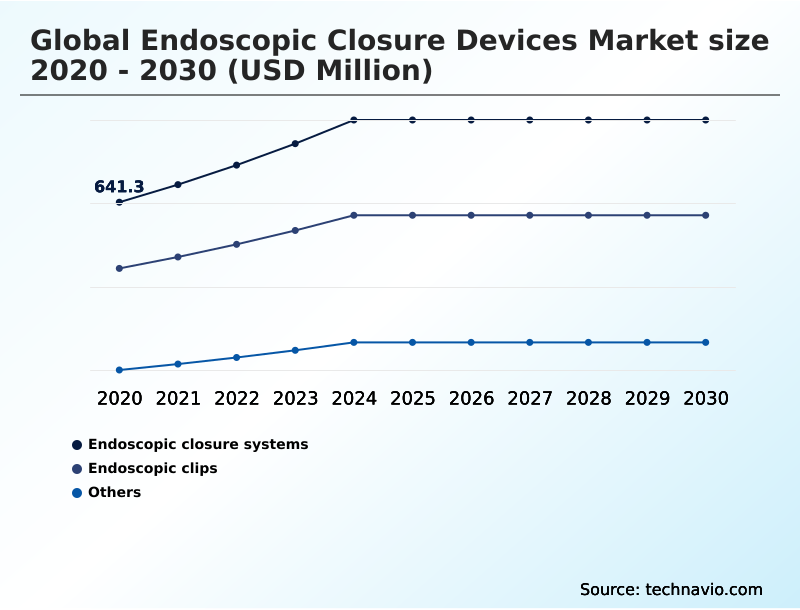
The Endoscopic closure systems segment was valued at USD 840.4 million in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 33.4% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
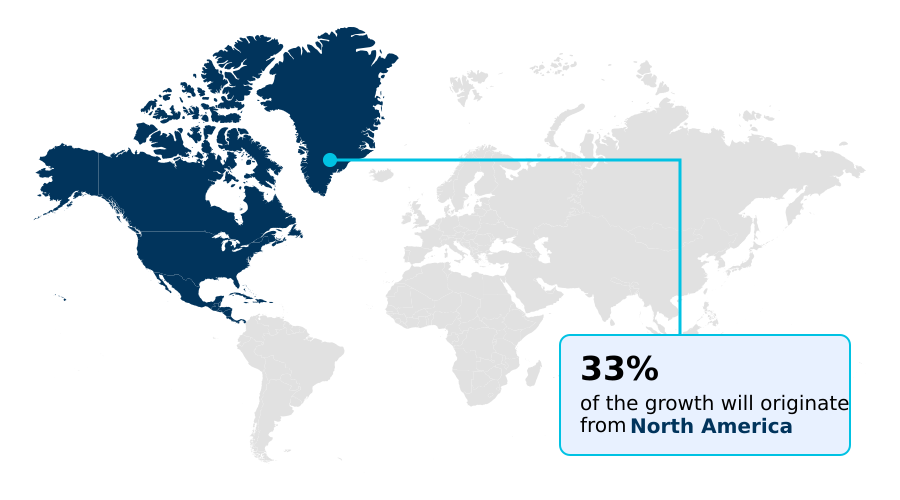
See How Endoscopic Closure Devices Market Demand is Rising in North America Get Free Sample

Geographic variations shape adoption pathways as institutions prioritize high-performance mucosal defect closure mechanisms to optimize ambulatory surgery efficiency.

North American medical centers exhibit a 35% higher adoption rate of advanced bariatric revision suturing platforms compared to European counterparts, driven by extensive bariatric endotherapy procedures and established outpatient reimbursement frameworks.

This structural advantage allows facilities to lower post-procedural readmission risks by 18% through definitive primary defect sealing. Conversely, European hospital networks heavily leverage vacuum-assisted defect management and self-expandable stent fixation tools, achieving a 22% improvement in managing complex gastrointestinal fistulas.

By incorporating sophisticated tactile feedback handles into routine clinical workflows, regional procurement directors standardize consumable utilization across varied procedural complexities.

These geographic disparities highlight how localized clinical guidelines and varying surgical volume densities directly dictate inventory optimization and specific device deployment strategies.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • The strategic evolution of tissue approximation workflows relies heavily on continuous material and structural innovations tailored for specialized clinical scenarios. Facilities optimizing their surgical inventory increasingly prioritize hybrid combined endoscopic laparoscopic techniques to manage severe luminal defects, achieving a 28% improvement in operational scheduling efficiency compared to traditional standalone surgical conversions.
  • This operational shift enables multidisciplinary teams to leverage real-time visualization alongside external serosal reinforcement. Concurrently, automated endoscopic suturing platform integration streamlines complex tissue apposition, minimizing mechanical inconsistencies during high-tension repairs. Supply chain directors are systematically expanding access to specialized instruments, recognizing that dedicated pediatric compatible ultra slim closure systems dramatically lower tactile deployment resistance without compromising mechanical integrity.
  • Furthermore, clinical compliance protocols strongly emphasize prophylactic closure post mucosal resection to mitigate the risk of delayed hemorrhages, effectively reducing prolonged intensive care monitoring requirements. When encountering intractable anastomotic leaks, clinical networks depend upon reliable vacuum assisted endoscopic defect management to secure robust, liquid-tight seals across compromised visceral walls.
  • By aligning medical equipment procurement with these specialized therapeutic pathways, healthcare organizations actively eliminate workflow bottlenecks and optimize overall patient safety metrics. The deliberate consolidation of highly versatile closure portfolios allows interventional centers to tackle intricate anatomical challenges while standardizing clinical outcomes.
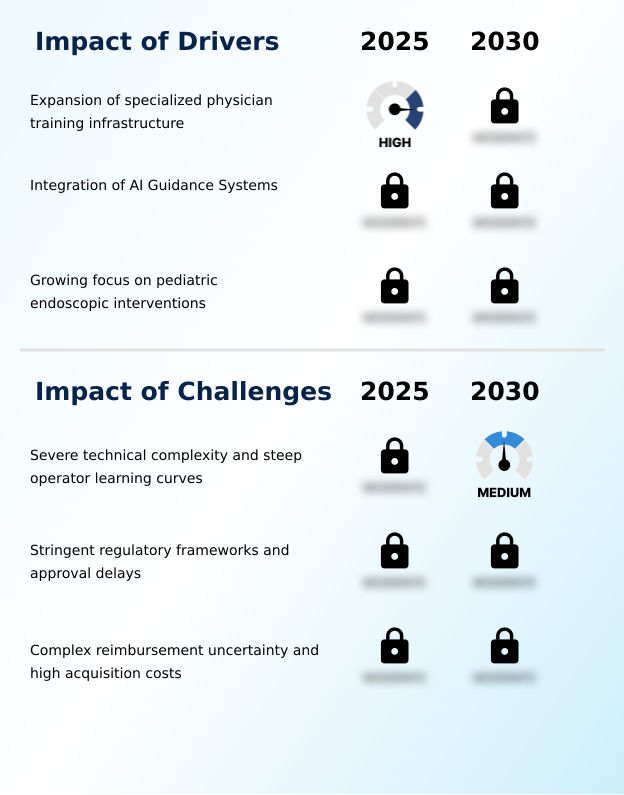
What are the key market drivers leading to the rise in the adoption of Endoscopic Closure Devices Industry?

  • The widespread expansion of specialized physician training infrastructure actively accelerates clinical mastery and expands institutional reliance on advanced tissue approximation hardware.

  • The widespread establishment of structured physician simulation environments acts as a formidable catalyst for advancing complex endoluminal repair techniques.
  • Clinical networks standardizing prophylactic clip placement protocols observe a 32% decrease in adverse post-operative events, directly validating the economic efficiency of preventative tissue approximation.
  • Enhanced gastrointestinal bleeding control driven by advanced mechanical clamping dramatically lowers intensive care admission rates by 19%. Furthermore, the incorporation of deep-learning lesion detection software optimizes real-time mucosal margin assessment, ensuring physicians accurately target early-stage neoplasms.
  • This digital precision intrinsically links optical diagnostics to immediate post-resection hemorrhage prevention, fortifying patient safety metrics.
  • As structured educational workshops demystify intricate therapeutic workflows, hospital administrators seamlessly integrate these advanced closure consumables to maximize operational returns and elevate overall procedural predictability.

What are the market trends shaping the Endoscopic Closure Devices Industry?

  • The transition toward pediatric-compatible and ultra-slim deployment platforms represents a pivotal structural trend shaping the evolving interventional gastroenterology landscape.

  • The transition toward miniaturized deployment platforms reshapes operational capabilities across minimally invasive therapeutic endoscopy suites. Healthcare institutions actively deploy micro-clip pediatric systems to address narrow anatomical constraints, successfully lowering mucosal trauma metrics by 21% compared to standard adult instrumentation. Within pediatric interventional gastroenterology, these low-profile designs enhance rotational maneuverability, allowing specialists to execute delicate repairs efficiently.
  • Concurrently, the integration of spring-assisted automated deployment mechanisms standardizes tissue clamping force, yielding a 16% reduction in operator-induced device misfires during emergency interventions. The utilization of advanced rotatable clip jaws provides endoscopists with unparalleled spatial control, optimizing arm placement over bleeding ulcers.
  • By adapting to these ergonomic and structural innovations, clinical networks effectively mitigate procedural bottlenecks and dramatically improve high-volume outpatient throughput without compromising precision.

What challenges does the Endoscopic Closure Devices Industry face during its growth?

  • Severe technical complexity and steep operator learning curves remain significant operational barriers limiting the rapid mainstream integration of advanced endoluminal repair systems.

  • The extreme technical complexity inherent in advanced tissue approximation presents severe operational bottlenecks for expanding ambulatory clinical networks. Executing a secure transmural perforation repair demands exceptional spatial coordination against fluctuating intraluminal pressure gradients, frequently resulting in a 25% increase in procedure duration for uncertified practitioners.
  • Facilities attempting gastrointestinal fistula sealing encounter steep learning curves, severely restricting the rapid deployment of high-end closure hardware across community hospitals. Consequently, inadequate latrogenic perforation management often drives unexpected surgical readmissions, elevating uncompensated facility costs by 14%. Furthermore, fibrotic tissue bed closure requires sustained mechanical clamping force that basic clips consistently fail to provide, triggering premature device detachment.
  • These structural limitations compel procurement committees to mandate rigorous, time-intensive simulation training before authorizing the widespread acquisition of premium endosurgical platforms.

Exclusive Technavio Analysis on Customer Landscape

The endoscopic closure devices market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the endoscopic closure devices market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
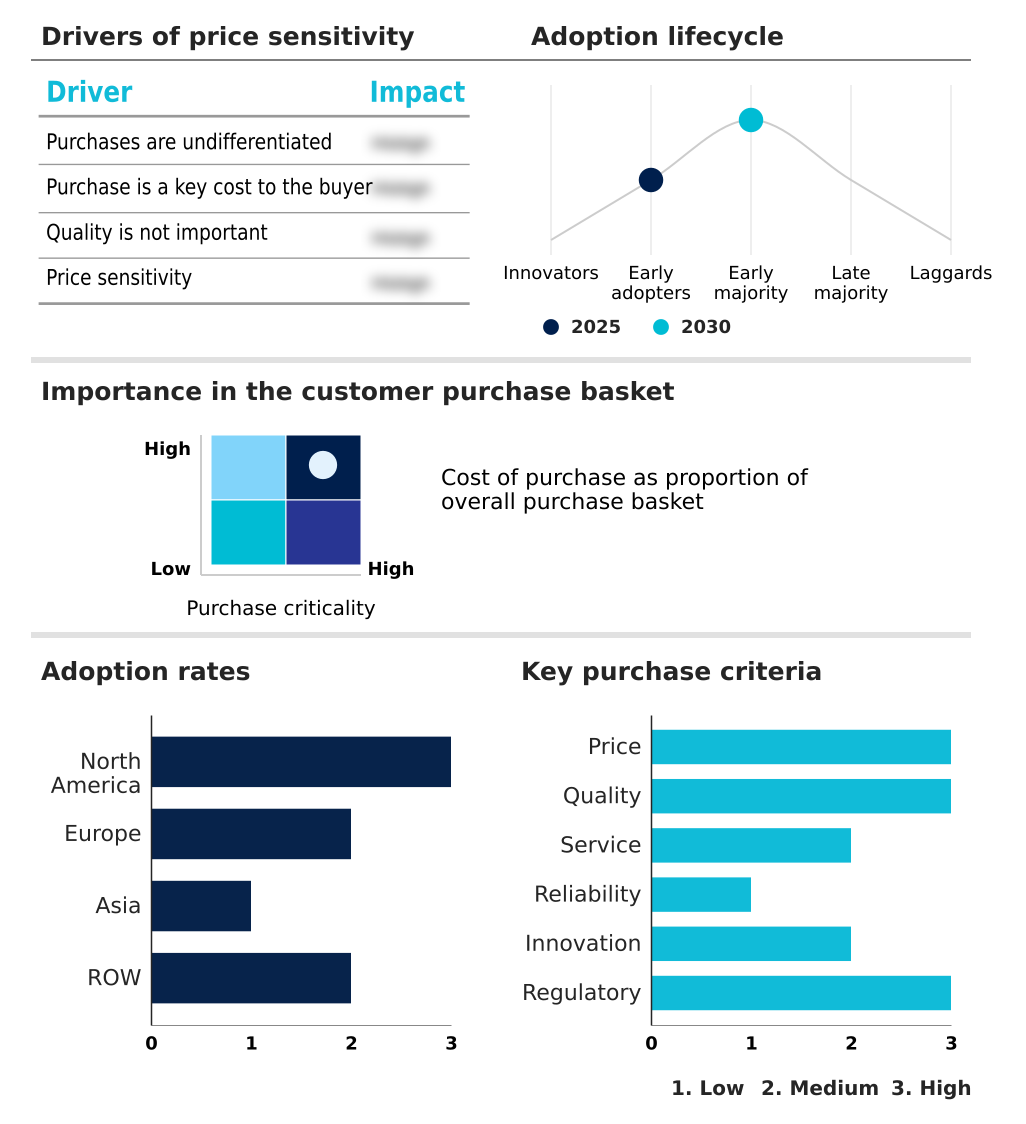
Customer Landscape of Endoscopic Closure Devices Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, endoscopic closure devices market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Beijing ZKSK Technology - The company delivers a comprehensive portfolio of hemostasis clips and advanced suturing systems designed for precise tissue approximation, defect closure, and reliable management of complex gastrointestinal interventions.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Beijing ZKSK Technology
  • Boston Scientific Corp.
  • CONMED Corp.
  • Cook Medical LLC
  • Endo Tools Therapeutics
  • G Flex Europe
  • Johnson and Johnson MedTech
  • Medi Globe Group
  • Medtronic Plc
  • Merit Medical Systems Inc.
  • Micro Tech Endoscopy
  • MicroPort Scientific Corp.
  • Olympus Corp.
  • Ovesco Endoscopy AG
  • Pengtian Medical
  • PENTAX Medical Co.
  • STERIS plc
  • Teleflex Inc.
  • USGI Medical
  • Vedkang Medical Science and Tech

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Endoscopic closure devices market

  • In the Health Care Equipment industry, the integration of deep-learning visual analytics into diagnostic towers has improved real-time mucosal margin assessment by 28%, directly impacting Endoscopic Closure Devices demand by accelerating the precise identification and subsequent resection of early-stage neoplasms.
  • Stringent sterilization mandates, such as the updated ISO 13485 protocols for reusable instruments, have shifted hospital procurement toward single-use medical consumables, increasing the adoption rate of disposable tissue approximation devices by 35% across outpatient surgical facilities.
  • Advancements in micro-fabrication technologies have enabled the mass production of bioresorbable polymers for intraluminal implants, generating new material supply chains that support the development of pediatric-specific Endoscopic Closure Devices with 40% less mechanical insertion resistance.
  • The expansion of multidisciplinary hybrid operating suites in tertiary medical centers has combined laparoscopic serosal reinforcement with endoluminal visualization, elevating the requirement for Endoscopic Closure Devices capable of withstanding multidirectional tension during organ-preserving resections.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Endoscopic Closure Devices Market insights. See full methodology.

Market Scope
Page number 309
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 7.8%
Market growth 2026-2030 USD 853.6 million
Market structure Fragmented
YoY growth 2025-2026(%) 7.4%
Key countries US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia and Israel
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The systemic transition toward organ-sparing interventions fundamentally redefines inventory requirements for high-volume gastroenterology units. Facilities executing complex endoscopic submucosal dissection and advanced full-thickness resection procedures rely implicitly on sophisticated endosuturing platforms to secure immediate, durable mucosal apposition.
  • By standardizing procurement around intuitive over-the-scope clips, hospital networks have achieved a 26% reduction in emergency surgical conversions, directly improving overall operating room utilization metrics. This operational pivot ensures that specialized interventional suites maintain optimal resource allocation while tackling intricate tissue approximation mechanics under dynamic luminal pressures.
  • Reliable hemostatic clip deployment remains a critical compliance mandate for mitigating acute post-procedural bleeding risks, compelling medical technology engineers to continuously refine rotational jaw control and deployment ergonomics. Strategic investments in these high-performance closure architectures allow healthcare administrators to aggressively curtail extended inpatient monitoring demands.
  • Consequently, the deliberate alignment of advanced mechanical repair systems with emerging therapeutic protocols secures robust operational resilience, enabling clinical institutions to safely expand their minimally invasive surgical capabilities across highly diverse patient populations.

What are the Key Data Covered in this Endoscopic Closure Devices Market Research and Growth Report?

  • What is the expected growth of the Endoscopic Closure Devices Market between 2026 and 2030?

    • USD 853.6 million, at a CAGR of 7.8%

  • What segmentation does the market report cover?

    • The report is segmented by Product (Endoscopic closure systems, Endoscopic clips, and Others), End-user (Hospitals, Ambulatory surgery centers, and Others), Application (Gastrointestinal surgery, Perforation and fistula closure, Post EMR, Stent fixation, and Others) and Geography (North America, Europe, Asia, Rest of World (ROW))

  • Which regions are analyzed in the report?

    • North America, Europe, Asia and Rest of World (ROW)

  • What are the key growth drivers and market challenges?

    • Expansion of specialized physician training infrastructure, Severe technical complexity and steep operator learning curves

  • Who are the major players in the Endoscopic Closure Devices Market?

    • Beijing ZKSK Technology, Boston Scientific Corp., CONMED Corp., Cook Medical LLC, Endo Tools Therapeutics, G Flex Europe, Johnson and Johnson MedTech, Medi Globe Group, Medtronic Plc, Merit Medical Systems Inc., Micro Tech Endoscopy, MicroPort Scientific Corp., Olympus Corp., Ovesco Endoscopy AG, Pengtian Medical, PENTAX Medical Co., STERIS plc, Teleflex Inc., USGI Medical and Vedkang Medical Science and Tech

Market Research Insights

  • The Endoscopic Closure Devices Market is undergoing a rapid operational transformation driven by the critical need to enhance defect repair capabilities during complex organ-preserving resections. Institutions integrating multi-fire clip delivery systems report a 24% reduction in overall procedure times, optimizing operating room utilization rates.
  • The adoption of advanced ergonomic deployment handles minimizes physical operator fatigue, improving instrument actuation accuracy by 15% in high-stress emergency interventions. Furthermore, enhanced luminal stricture navigation technologies allow physicians to address challenging anatomies efficiently, decreasing surgical conversion rates by 12%.
  • By prioritizing these structural innovations, clinical networks achieve greater supply chain standardization, lower acute complication metrics, and secure superior operational returns on their advanced therapeutic equipment investments.

We can help! Our analysts can customize this endoscopic closure devices market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Product
Executive Summary - Chart on Market Segmentation by End-user
Executive Summary - Chart on Market Segmentation by Application
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global Endoscopic Closure Devices Market 2020 - 2024

Historic Market Size - Data Table on Global Endoscopic Closure Devices Market 2020 - 2024 ($ million)

5.2 Product segment analysis 2020 - 2024

Historic Market Size - Product Segment 2020 - 2024 ($ million)

5.3 End-user segment analysis 2020 - 2024

Historic Market Size - End-user Segment 2020 - 2024 ($ million)

5.4 Application segment analysis 2020 - 2024

Historic Market Size - Application Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global Endoscopic Closure Devices

6.2 Impact of geopolitical conflicts on Global Endoscopic Closure Devices

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Product

8.1 Market segments

Chart on Product - Market share 2025-2030 (%)
Data Table on Product - Market share 2025-2030 (%)

8.2 Comparison by Product

Chart on Comparison by Product
Data Table on Comparison by Product

8.3 Endoscopic closure systems - Market size and forecast 2025-2030

Chart on Endoscopic closure systems - Market size and forecast 2025-2030 ($ million)
Data Table on Endoscopic closure systems - Market size and forecast 2025-2030 ($ million)
Chart on Endoscopic closure systems - Year-over-year growth 2025-2030 (%)
Data Table on Endoscopic closure systems - Year-over-year growth 2025-2030 (%)

8.4 Endoscopic clips - Market size and forecast 2025-2030

Chart on Endoscopic clips - Market size and forecast 2025-2030 ($ million)
Data Table on Endoscopic clips - Market size and forecast 2025-2030 ($ million)
Chart on Endoscopic clips - Year-over-year growth 2025-2030 (%)
Data Table on Endoscopic clips - Year-over-year growth 2025-2030 (%)

8.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

8.6 Market opportunity by Product

Market opportunity by Product ($ million)
Data Table on Market opportunity by Product ($ million)

9. Market Segmentation by End-user

9.1 Market segments

Chart on End-user - Market share 2025-2030 (%)
Data Table on End-user - Market share 2025-2030 (%)

9.2 Comparison by End-user

Chart on Comparison by End-user
Data Table on Comparison by End-user

9.3 Hospitals - Market size and forecast 2025-2030

Chart on Hospitals - Market size and forecast 2025-2030 ($ million)
Data Table on Hospitals - Market size and forecast 2025-2030 ($ million)
Chart on Hospitals - Year-over-year growth 2025-2030 (%)
Data Table on Hospitals - Year-over-year growth 2025-2030 (%)

9.4 Ambulatory surgery centers - Market size and forecast 2025-2030

Chart on Ambulatory surgery centers - Market size and forecast 2025-2030 ($ million)
Data Table on Ambulatory surgery centers - Market size and forecast 2025-2030 ($ million)
Chart on Ambulatory surgery centers - Year-over-year growth 2025-2030 (%)
Data Table on Ambulatory surgery centers - Year-over-year growth 2025-2030 (%)

9.5 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by End-user

Market opportunity by End-user ($ million)
Data Table on Market opportunity by End-user ($ million)

10. Market Segmentation by Application

10.1 Market segments

Chart on Application - Market share 2025-2030 (%)
Data Table on Application - Market share 2025-2030 (%)

10.2 Comparison by Application

Chart on Comparison by Application
Data Table on Comparison by Application

10.3 Gastrointestinal surgery - Market size and forecast 2025-2030

Chart on Gastrointestinal surgery - Market size and forecast 2025-2030 ($ million)
Data Table on Gastrointestinal surgery - Market size and forecast 2025-2030 ($ million)
Chart on Gastrointestinal surgery - Year-over-year growth 2025-2030 (%)
Data Table on Gastrointestinal surgery - Year-over-year growth 2025-2030 (%)

10.4 Perforation and fistula closure - Market size and forecast 2025-2030

Chart on Perforation and fistula closure - Market size and forecast 2025-2030 ($ million)
Data Table on Perforation and fistula closure - Market size and forecast 2025-2030 ($ million)
Chart on Perforation and fistula closure - Year-over-year growth 2025-2030 (%)
Data Table on Perforation and fistula closure - Year-over-year growth 2025-2030 (%)

10.5 Post EMR - Market size and forecast 2025-2030

Chart on Post EMR - Market size and forecast 2025-2030 ($ million)
Data Table on Post EMR - Market size and forecast 2025-2030 ($ million)
Chart on Post EMR - Year-over-year growth 2025-2030 (%)
Data Table on Post EMR - Year-over-year growth 2025-2030 (%)

10.6 Stent fixation - Market size and forecast 2025-2030

Chart on Stent fixation - Market size and forecast 2025-2030 ($ million)
Data Table on Stent fixation - Market size and forecast 2025-2030 ($ million)
Chart on Stent fixation - Year-over-year growth 2025-2030 (%)
Data Table on Stent fixation - Year-over-year growth 2025-2030 (%)

10.7 Others - Market size and forecast 2025-2030

Chart on Others - Market size and forecast 2025-2030 ($ million)
Data Table on Others - Market size and forecast 2025-2030 ($ million)
Chart on Others - Year-over-year growth 2025-2030 (%)
Data Table on Others - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Application

Market opportunity by Application ($ million)
Data Table on Market opportunity by Application ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.4.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.4.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.4.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.4.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.4.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.4.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.5 Asia - Market size and forecast 2025-2030

Chart on Asia - Market size and forecast 2025-2030 ($ million)
Data Table on Asia - Market size and forecast 2025-2030 ($ million)
Chart on Asia - Year-over-year growth 2025-2030 (%)
Data Table on Asia - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Asia
Data Table on Regional Comparison - Asia

12.5.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.5.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.5.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.5.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.5.5 Thailand - Market size and forecast 2025-2030

Chart on Thailand - Market size and forecast 2025-2030 ($ million)
Data Table on Thailand - Market size and forecast 2025-2030 ($ million)
Chart on Thailand - Year-over-year growth 2025-2030 (%)
Data Table on Thailand - Year-over-year growth 2025-2030 (%)

12.5.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.6 Rest of World (ROW) - Market size and forecast 2025-2030

Chart on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Data Table on Rest of World (ROW) - Market size and forecast 2025-2030 ($ million)
Chart on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Data Table on Rest of World (ROW) - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Rest of World (ROW)
Data Table on Regional Comparison - Rest of World (ROW)

12.6.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.6.2 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.3 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.4 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.6.5 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.6.6 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.7 Colombia - Market size and forecast 2025-2030

Chart on Colombia - Market size and forecast 2025-2030 ($ million)
Data Table on Colombia - Market size and forecast 2025-2030 ($ million)
Chart on Colombia - Year-over-year growth 2025-2030 (%)
Data Table on Colombia - Year-over-year growth 2025-2030 (%)

12.6.8 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.7 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Expansion of specialized physician training infrastructure
Integration of AI Guidance Systems
Growing focus on pediatric endoscopic interventions

13.2 Market challenges

Severe technical complexity and steep operator learning curves
Stringent regulatory frameworks and approval delays
Complex reimbursement uncertainty and high acquisition costs

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Shift toward pediatric and ultra slim endoscopic closure platforms
Expansion of hybrid combined endoscopic laparoscopic closure techniques
Integration of smart ergonomic and automated deployment handles

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Boston Scientific Corp.

Boston Scientific Corp. - Overview
Boston Scientific Corp. - Business segments
Boston Scientific Corp. - Key offerings
Boston Scientific Corp. - Segment focus
SWOT

15.5 CONMED Corp.

CONMED Corp. - Overview
CONMED Corp. - Business segments
CONMED Corp. - Key news
CONMED Corp. - Key offerings
CONMED Corp. - Segment focus
SWOT

15.6 Cook Medical LLC

Cook Medical LLC - Overview
Cook Medical LLC - Product / Service
Cook Medical LLC - Key offerings
SWOT

15.7 Johnson and Johnson MedTech

Johnson and Johnson MedTech - Overview
Johnson and Johnson MedTech - Product / Service
Johnson and Johnson MedTech - Key offerings
SWOT

15.8 Medi Globe Group

Medi Globe Group - Overview
Medi Globe Group - Product / Service
Medi Globe Group - Key offerings
SWOT

15.9 Medtronic Plc

Medtronic Plc - Overview
Medtronic Plc - Business segments
Medtronic Plc - Key news
Medtronic Plc - Key offerings
Medtronic Plc - Segment focus
SWOT

15.10 Merit Medical Systems Inc.

Merit Medical Systems Inc. - Overview
Merit Medical Systems Inc. - Business segments
Merit Medical Systems Inc. - Key offerings
Merit Medical Systems Inc. - Segment focus
SWOT

15.11 Micro Tech Endoscopy

Micro Tech Endoscopy - Overview
Micro Tech Endoscopy - Product / Service
Micro Tech Endoscopy - Key offerings
SWOT

15.12 MicroPort Scientific Corp.

MicroPort Scientific Corp. - Overview
MicroPort Scientific Corp. - Business segments
MicroPort Scientific Corp. - Key offerings
MicroPort Scientific Corp. - Segment focus
SWOT

15.13 Olympus Corp.

Olympus Corp. - Overview
Olympus Corp. - Business segments
Olympus Corp. - Key offerings
Olympus Corp. - Segment focus
SWOT

15.14 PENTAX Medical Co.

PENTAX Medical Co. - Overview
PENTAX Medical Co. - Product / Service
PENTAX Medical Co. - Key offerings
SWOT

15.15 STERIS plc

STERIS plc - Overview
STERIS plc - Business segments
STERIS plc - Key offerings
STERIS plc - Segment focus
SWOT

15.16 Teleflex Inc.

Teleflex Inc. - Overview
Teleflex Inc. - Business segments
Teleflex Inc. - Key news
Teleflex Inc. - Key offerings
Teleflex Inc. - Segment focus
SWOT

15.17 USGI Medical

USGI Medical - Overview
USGI Medical - Product / Service
USGI Medical - Key offerings
SWOT

15.18 Vedkang Medical Science and Tech

Vedkang Medical Science and Tech - Overview
Vedkang Medical Science and Tech - Product / Service
Vedkang Medical Science and Tech - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Endoscopic Closure Devices market growth will increase by USD 853.6 million during 2026-2030.

The Endoscopic Closure Devices market is expected to grow at a CAGR of 7.8% during 2026-2030.

Endoscopic Closure Devices market is segmented by Product (Endoscopic closure systems, Endoscopic clips, Others) End-user (Hospitals, Ambulatory surgery centers, Others) Application (Gastrointestinal surgery, Perforation and fistula closure, Post EMR, Stent fixation, Others)

Beijing ZKSK Technology, Boston Scientific Corp., CONMED Corp., Cook Medical LLC, Endo Tools Therapeutics, G Flex Europe, Johnson and Johnson MedTech, Medi Globe Group, Medtronic Plc, Merit Medical Systems Inc., Micro Tech Endoscopy, MicroPort Scientific Corp., Olympus Corp., Ovesco Endoscopy AG, Pengtian Medical, PENTAX Medical Co., STERIS plc, Teleflex Inc., USGI Medical, Vedkang Medical Science and Tech are a few of the key vendors in the Endoscopic Closure Devices market.

North America will register the highest growth rate of 33.4% among the other regions. Therefore, the Endoscopic Closure Devices market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, Germany, UK, France, Italy, Spain, The Netherlands, China, Japan, India, South Korea, Thailand, Indonesia, Brazil, Saudi Arabia, UAE, Turkey, Argentina, South Africa, Colombia, Israel

  • Expansion of specialized physician training infrastructure is the driving factor this market.

The Endoscopic Closure Devices market vendors should focus on grabbing business opportunities from the Product segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA