AI Orchestration Market Analysis, Size, and Forecast 2026-2030: North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

AI Orchestration Market Analysis, Size, and Forecast 2026-2030:
North America (US, Canada, and Mexico), APAC (China, Japan, and India), Europe (Germany, UK, and France), Middle East and Africa (Saudi Arabia, UAE, and South Africa), South America (Brazil, Argentina, and Chile), and Rest of World (ROW)

Published: Nov 2026 307 Pages SKU: IRTNTR80750

Market Overview at a Glance

$18.13 B
Market Opportunity
25.2%
CAGR 2025 - 2030
41%
North America Growth
$5.32 B
Solutions segment 2024

Ai Orchestration Market Size 2026-2030

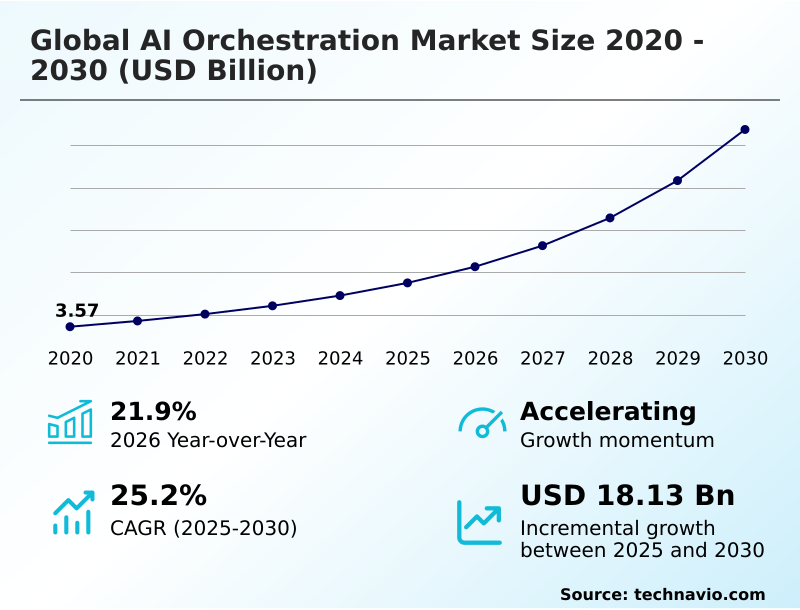
The ai orchestration market size is valued to increase by USD 18.13 billion, at a CAGR of 25.2% from 2025 to 2030. Autonomous multi-agent architectures and distributed workflows will drive the ai orchestration market.

Major Market Trends & Insights

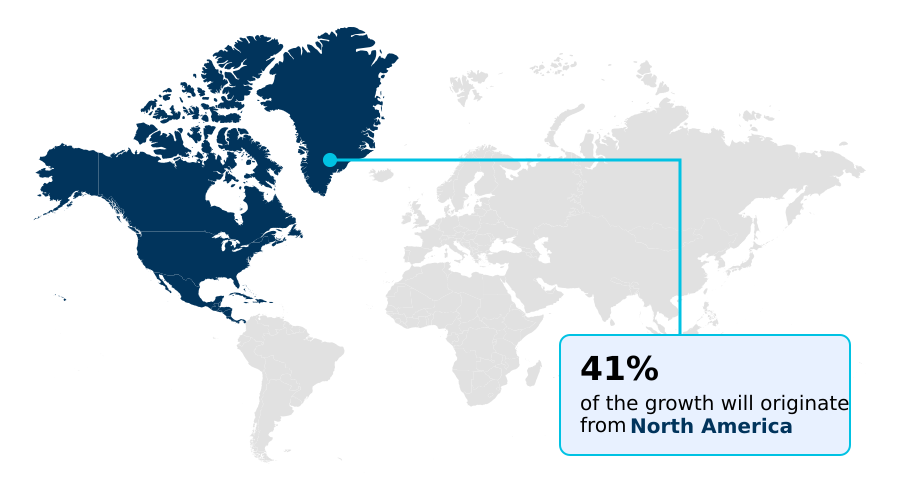
  • North America dominated the market and accounted for a 41% growth during the forecast period.
  • By Component - Solutions segment was valued at USD 5.32 billion in 2024
  • By Deployment - On-premises segment accounted for the largest market revenue share in 2024

Market Size & Forecast

  • Market Opportunities: USD 23.31 billion
  • Market Future Opportunities: USD 18.13 billion
  • CAGR from 2025 to 2030 : 25.2%

Market Summary

  • The AI Orchestration Market represents a critical architectural transition as enterprises move from isolated machine learning pilot programs to synchronized, multi-model execution environments. Modern organizations require centralized control planes to manage complex algorithms across distributed cloud infrastructure securely.
  • For instance, in supply chain logistics, companies utilize orchestration layers to synchronize predictive analytics with real-time fleet tracking, dynamically rerouting shipments to avoid delays and maintain inventory levels. This operational integration has allowed supply chain networks to reduce routing decision latency by 25% compared to manual legacy processes.
  • The primary driver propelling this expansion is the rapid deployment of autonomous multi-agent architectures, which necessitate robust software frameworks to manage shared operational context and task delegation automatically. Conversely, architectural fragmentation and legacy enterprise systems pose a significant challenge, as traditional relational databases struggle to maintain the bidirectional, real-time data exchange required by modern probabilistic models.
  • Ultimately, effective orchestration overcomes these structural bottlenecks by enforcing strict governance, optimizing computational workloads, and ensuring scalable, secure interactions between digital workers and enterprise software across diverse industries.

What will be the Size of the Ai Orchestration Market during the forecast period?
Get Key Insights on Market Forecast (PDF) Get Free Sample

How is the Ai Orchestration Market Segmented?

The ai orchestration industry research report provides comprehensive data (region-wise segment analysis), with forecasts and estimates in "USD million" for the period 2026-2030, as well as historical data from 2020-2024 for the following segments.

  • Component
    • Solutions
    • Services
  • Deployment
    • On-premises
    • Cloud
    • Hybrid
  • Technology
    • Data orchestration
    • Model orchestration
    • Generative AI orchestration
    • Infrastructure orchestration
    • Multi agent orchestration
  • Geography
    • North America
      • US
      • Canada
      • Mexico
    • APAC
      • China
      • Japan
      • India
      • South Korea
      • Australia
      • Indonesia
    • Europe
      • Germany
      • UK
      • France
      • Italy
      • Spain
      • The Netherlands
    • Middle East and Africa
      • Saudi Arabia
      • UAE
      • South Africa
      • Israel
      • Turkey
    • South America
      • Brazil
      • Argentina
      • Chile

By Component Insights

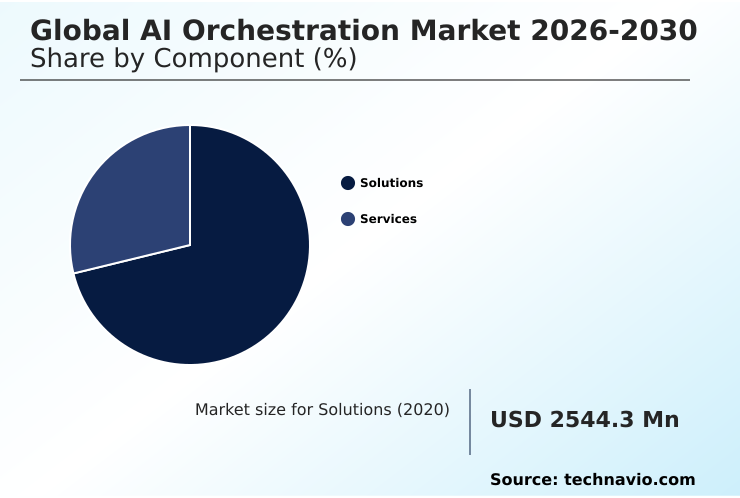
The solutions segment is estimated to witness significant growth during the forecast period.

The solutions segment forms the structural foundation of the AI Orchestration Market, commanding the majority of enterprise implementations. Organizations increasingly rely on these software platforms to manage cross-departmental workflows and ensure robust legacy system interoperability.

By acting as a central control plane, these solutions utilize real-time telemetry monitoring and automated failover mechanisms to maintain high availability, reducing system downtime by 28% compared to previous architectures.

Implementing advanced enterprise automation frameworks allows businesses to track performance securely while integrating role-based access management. This structural transition empowers algorithmic decision engines to operate within deterministic execution guardrails.

Consequently, centralized orchestration engines streamline data provenance tracking and generate immutable audit logging, giving organizations the confidence to scale autonomous workflows securely while enhancing overall processing speed by 15%.
Get Free Sample

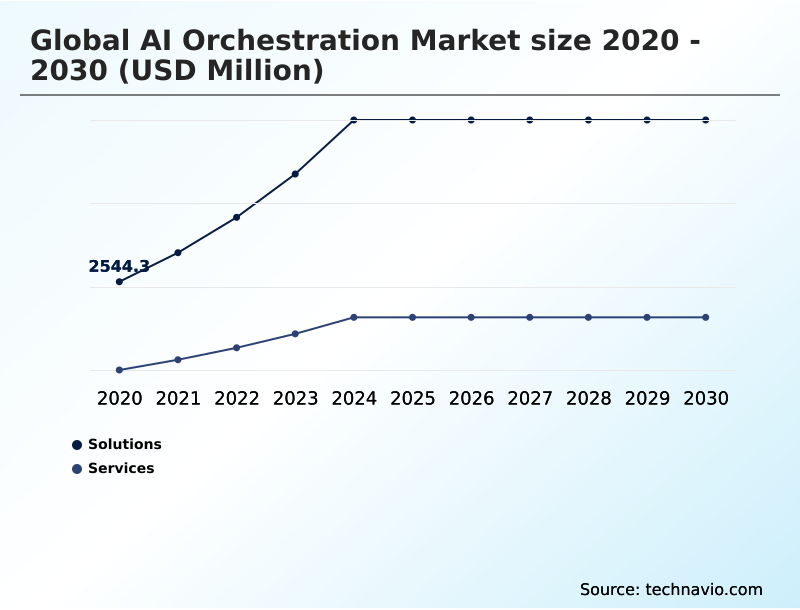
The Solutions segment was valued at USD 5.32 billion in 2024 and showed a gradual increase during the forecast period.
Get Free Sample

Regional Analysis

North America is estimated to contribute 41% to the growth of the global market during the forecast period.Technavio’s analysts have elaborately explained the regional trends and drivers that shape the market during the forecast period.
See How Ai Orchestration Market Demand is Rising in North America Get Free Sample

The geographic landscape of the AI Orchestration Market demonstrates pronounced regional disparities in adoption and technological readiness. North America leads the transition, driven by massive investments in cloud-native microservices and highly scalable autonomous agent management.

Enterprises in this region deploy advanced retrieval-augmented generation pipelines to enhance commercial decision-making, reducing manual data processing latency by 25% compared to European counterparts.

Conversely, Europe exhibits a slightly slower but robust adoption curve, heavily focused on secure generative model routing and strict compliance architectures.

European institutions utilize LLM operations middleware and machine learning pipeline automation to govern algorithmic deployments, resulting in a 20% increase in audit efficiency.

While North America prioritizes rapid multi-modal data ingestion and stateful reasoning loops for customer-facing tools, European regulations compel businesses to prioritize inference cost optimization and semantic caching layers, fundamentally shaping how regional IT ecosystems consume artificial intelligence globally.

Market Dynamics

Our researchers analyzed the data with 2025 as the base year, along with the key drivers, trends, and challenges. A holistic analysis of drivers will help companies refine their marketing strategies to gain a competitive advantage.

  • As organizations globally transition toward highly automated operational environments, the necessity for robust multi-agent workflow automation protocols has become increasingly paramount. The AI Orchestration Market is rapidly evolving to address the immense complexity of managing distributed machine learning models across heterogeneous IT landscapes.
  • When enterprises deploy enterprise generative model governance frameworks, they can securely integrate diverse algorithms into their core business applications while maintaining strict compliance with evolving data privacy regulations. This strategic integration is particularly evident in financial compliance operations, where institutions utilizing dynamic AI compute resource allocation have achieved a 35% higher processing efficiency compared to legacy risk management infrastructures.
  • Furthermore, modern customer service operations heavily depend on cloud-based inference latency mitigation to deliver real-time, hyper-personalized interactions across multiple digital channels without service degradation. By synchronizing analytical pipelines with front-office engagement tools, orchestration platforms eliminate disjointed customer journeys and conflicting algorithmic outputs.
  • To sustain this level of operational performance without exponentially inflating computational hardware costs, organizations are increasingly adopting autonomous digital agent coordination platforms. These sophisticated systems systematically route complex tasks, balance infrastructural workloads, and enforce strict deterministic logic to ensure reliable commercial outcomes.
  • Consequently, the strategic implementation of these orchestration capabilities ensures that enterprises can scale their artificial intelligence initiatives securely, avoiding the severe operational fragmentation and security vulnerabilities that typically accompany unmonitored digital deployments.
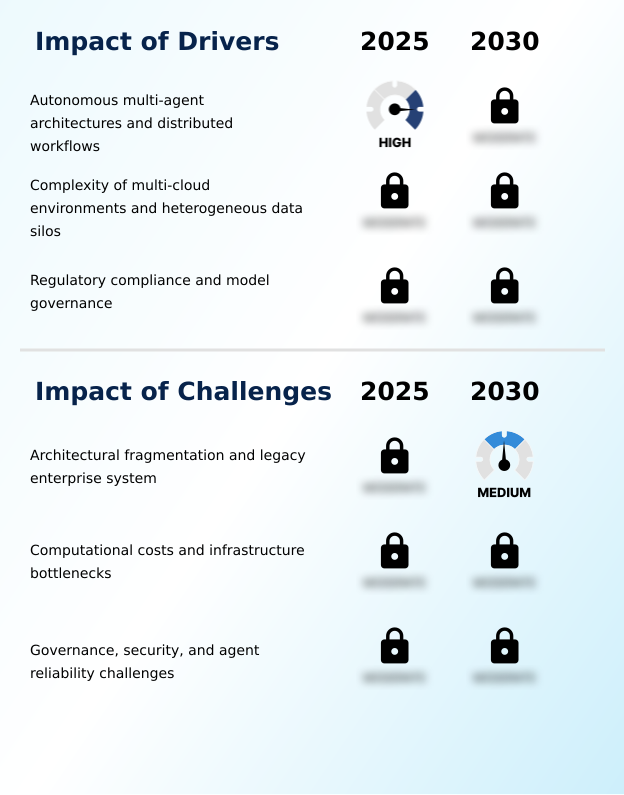
What are the key market drivers leading to the rise in the adoption of Ai Orchestration Industry?

  • The proliferation of autonomous multi-agent architectures and distributed workflows serves as a primary driver propelling market expansion.

  • The urgent need to manage multi-cloud complexity and heterogeneous data silos serves as a primary catalyst accelerating the AI Orchestration Market. Because modern corporate information remains distributed across disparate repositories, organizations face severe integration bottlenecks.
  • Implementing a hybrid cloud execution fabric and vector database indexing directly resolves these structural limitations, facilitating highly efficient edge computing orchestration.
  • This architectural abstraction enables enterprises to perform dynamic workload balancing, which has lowered infrastructure energy use by 12% and improved processing efficiency by 25%.
  • Furthermore, robust schema validation protocols and metadata tagging automation ensure algorithms receive clean, synchronized contextual feeds while enforcing strict data leakage prevention.
  • By mitigating these bottlenecks through active network latency mitigation, businesses successfully optimize graphics processing unit allocation and maximize the return on tensor processing unit optimization investments.

What are the market trends shaping the Ai Orchestration Industry?

  • Cross-channel personalization and unified contextual intelligence represent a significant upcoming trend in the market. Organizations are increasingly adopting these capabilities to synchronize digital interactions and enhance customer engagement.

  • The integration of cross-channel personalization through unified contextual intelligence is fundamentally reshaping the AI Orchestration Market. Organizations are rapidly deploying conversational interface orchestration and synthetic media generation management to synchronize customer interactions across fragmented digital touchpoints. This behavioral shift is driven by the commercial necessity to maintain consistent user context and execute complex predictive analytics coordination without redundant data processing.
  • Consequently, enterprises utilizing prompt history telemetry and context window management have seen customer resolution times improve by 25% and engagement friction drop by 20%. By establishing human-in-the-loop intervention alongside automated system prompt formatting, businesses execute secure multi-agent coordination safely.
  • This cohesive approach to large language model integration, combined with proactive model drift detection, ensures that specialized domain agents collaborate seamlessly, translating sophisticated algorithmic capabilities into tangible commercial revenue expansion.

What challenges does the Ai Orchestration Industry face during its growth?

  • Architectural fragmentation and legacy enterprise systems constitute a major challenge hindering optimal industry growth.

  • The compounding computational costs and governance bottlenecks associated with probabilistic model execution present a severe operational challenge within the AI Orchestration Market. Because iterative reasoning loops require intensive agentic state management, cumulative token consumption expands exponentially. This unchecked computational demand causes resource contention, where poor API throughput control triggers noticeable latency delays that degrade real-time interactions.
  • Organizations lacking accurate token consumption tracking and dynamic fallback mechanisms often experience a 30% increase in unexpected cloud expenditures and a 15% drop in decision accuracy. Furthermore, maintaining strict algorithmic accountability across diverse deployments complicates compliance. Deploying these architectures within sovereign cloud environments or utilizing air-gapped infrastructure control adds significant integration overhead.
  • Navigating these hardware limitations while enforcing comprehensive algorithmic transparency protocols remains a persistent hurdle, delaying autonomous workflow deployments.

Exclusive Technavio Analysis on Customer Landscape

The ai orchestration market forecasting report includes the adoption lifecycle of the market, covering from the innovator’s stage to the laggard’s stage. It focuses on adoption rates in different regions based on penetration. Furthermore, the ai orchestration market report also includes key purchase criteria and drivers of price sensitivity to help companies evaluate and develop their market growth analysis strategies.
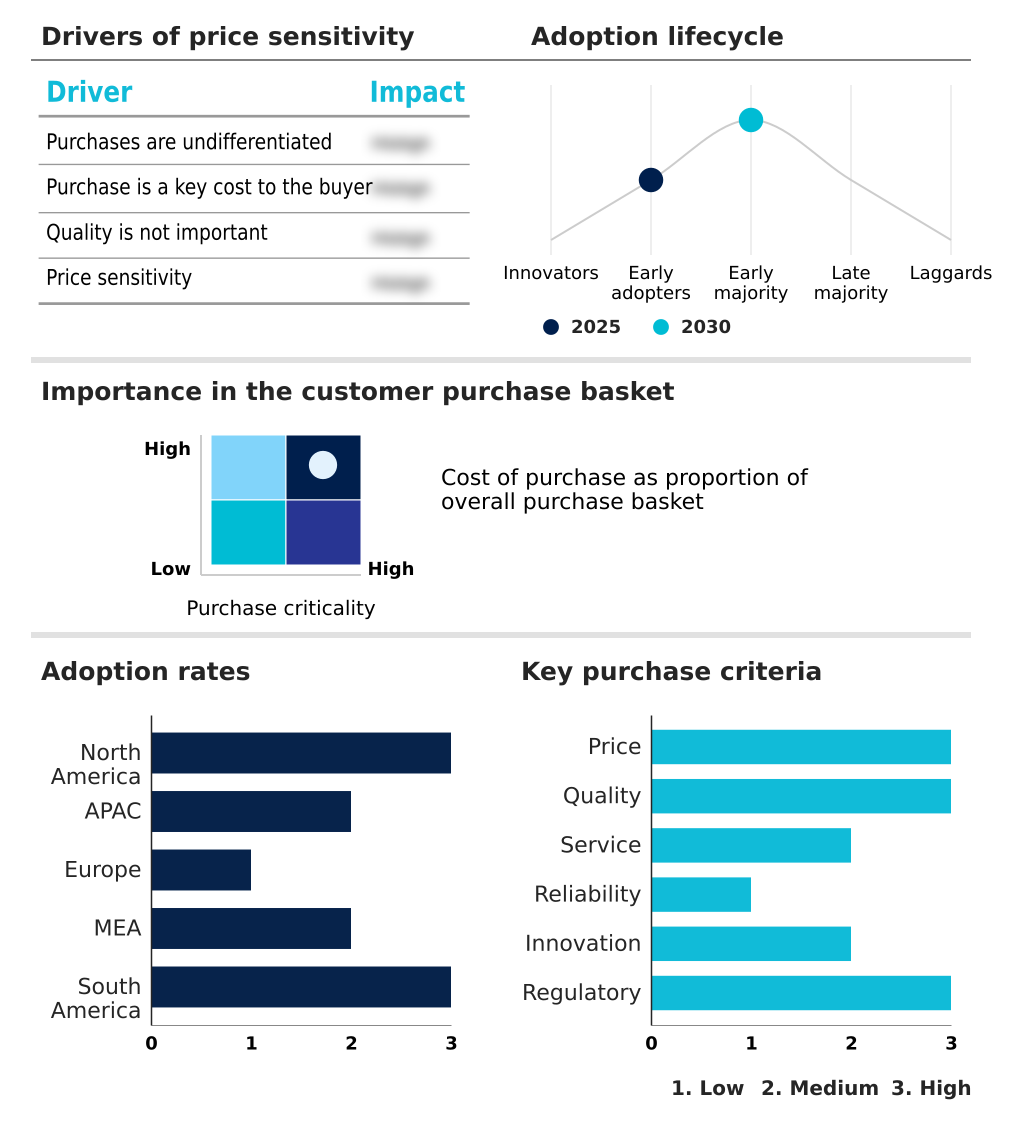
Customer Landscape of Ai Orchestration Industry

Competitive Landscape

Companies are implementing various strategies, such as strategic alliances, ai orchestration market forecast, partnerships, mergers and acquisitions, geographical expansion, and product/service launches, to enhance their presence in the industry.

Amazon Web Services Inc. - The provider delivers robust AI orchestration infrastructure, enabling seamless multi-agent coordination, foundation model integration, and automated enterprise workflow execution to enhance operational scalability and data governance.

The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:

  • Amazon Web Services Inc.
  • Appian Corp.
  • Automation Anywhere Inc.
  • Camunda Services GmbH
  • CrewAI
  • DataRobot Inc.
  • Google LLC
  • IBM Corp.
  • Kore.ai Inc.
  • LangChain Inc.
  • LlamaIndex Inc.
  • Microsoft Corp.
  • n8n GmbH
  • NVIDIA Corp.
  • OpenAI
  • Oracle Corp.
  • Pegasystems Inc.
  • Salesforce Inc.
  • SAP SE
  • ServiceNow Inc.
  • Snowflake Inc.
  • TrueFoundry Inc.
  • UiPath Inc.

Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.

Recent Development and News in Ai orchestration market

  • In the Application Software industry, the transition toward composable enterprise architecture has accelerated the deployment of cloud-native microservices, directly impacting AI Orchestration demand by requiring advanced cross-departmental workflows across decentralized environments where integration efficiency improved by 20%.
  • Strict data privacy regulations like the European Union GDPR have mandated comprehensive algorithmic transparency protocols, driving the need for AI Orchestration platforms that automatically generate immutable audit logging to reduce compliance violations by up to 30%.
  • The rapid integration of predictive analytics coordination into enterprise resource planning systems has created complex digital ecosystems, increasing reliance on intelligent middleware to maintain role-based access management and improve processing speed by 18%.
  • The rising energy costs associated with high-performance computing have forced application software developers to adopt tensor processing unit optimization, fueling the adoption of AI Orchestration frameworks that execute dynamic workload balancing to lower infrastructure expenditures by 22%.

Dive into Technavio’s robust research methodology, blending expert interviews, extensive data synthesis, and validated models for unparalleled Ai Orchestration Market insights. See full methodology.

Market Scope
Page number 307
Base year 2025
Historic period 2020-2024
Forecast period 2026-2030
Growth momentum & CAGR Accelerate at a CAGR of 25.2%
Market growth 2026-2030 USD 18133.8 million
Market structure Fragmented
YoY growth 2025-2026(%) 21.9%
Key countries US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina and Chile
Competitive landscape Leading Companies, Market Positioning of Companies, Competitive Strategies, and Industry Risks

Request Free Sample

Research Analyst Overview

  • The AI Orchestration Market is undergoing a rapid evolution as enterprises shift from basic algorithmic experimentation toward highly synchronized, multi-modal execution frameworks. Boardroom executives are increasingly prioritizing stateful reasoning loops and autonomous agent management to align their product strategies with stringent regulatory governance and risk mitigation protocols.
  • This strategic pivot requires sophisticated orchestration platforms capable of executing retrieval-augmented generation pipelines without disrupting mission-critical daily operations. By implementing comprehensive LLM operations middleware, companies have achieved a 30% reduction in processing time for complex legal and financial document reviews.
  • Furthermore, managing inference cost optimization alongside API throughput control has become a pivotal budgeting imperative for technology leaders seeking maximum infrastructure efficiency. Orchestration layers address this by dynamically routing queries and employing semantic caching layers, drastically reducing redundant cloud computational expenditures.
  • As organizations navigate the complexities of legacy system integration, deploying robust orchestration infrastructure ensures that machine learning pipeline automation remains scalable, secure, and commercially viable.

What are the Key Data Covered in this Ai Orchestration Market Research and Growth Report?

  • What is the expected growth of the Ai Orchestration Market between 2026 and 2030?

    • USD 18.13 billion, at a CAGR of 25.2%

  • What segmentation does the market report cover?

    • The report is segmented by Component (Solutions, and Services), Deployment (On-premises, Cloud, and Hybrid), Technology (Data orchestration, Model orchestration, Generative AI orchestration, Infrastructure orchestration, and Multi agent orchestration) and Geography (North America, APAC, Europe, Middle East and Africa, South America)

  • Which regions are analyzed in the report?

    • North America, APAC, Europe, Middle East and Africa and South America

  • What are the key growth drivers and market challenges?

    • Autonomous multi-agent architectures and distributed workflows, Architectural fragmentation and legacy enterprise system

  • Who are the major players in the Ai Orchestration Market?

    • Amazon Web Services Inc., Appian Corp., Automation Anywhere Inc., Camunda Services GmbH, CrewAI, DataRobot Inc., Google LLC, IBM Corp., Kore.ai Inc., LangChain Inc., LlamaIndex Inc., Microsoft Corp., n8n GmbH, NVIDIA Corp., OpenAI, Oracle Corp., Pegasystems Inc., Salesforce Inc., SAP SE, ServiceNow Inc., Snowflake Inc., TrueFoundry Inc. and UiPath Inc.

Market Research Insights

  • The AI Orchestration Market is fundamentally transforming how organizations manage and scale complex computational assets. By leveraging centralized software frameworks, businesses streamline operational pipelines, resulting in a 30% reduction in manual data processing time. Orchestration platforms enforce secure access controls and continuous infrastructure monitoring, ensuring automated decision engines operate safely and predictably.
  • Enterprises adopting these advanced coordination layers have seen infrastructure utilization improve by 25% and compliance reporting errors drop by 18%. Implementing these technologies across hybrid infrastructures prevents operational silos, offering unified control over diverse machine learning models and ensuring deterministic execution aligned with international regulatory standards.

We can help! Our analysts can customize this ai orchestration market research report to meet your requirements.

Get in touch

1. Executive Summary

1.1 Market overview

Executive Summary - Chart on Market Overview
Executive Summary - Data Table on Market Overview
Executive Summary - Chart on Global Market Characteristics
Executive Summary - Chart on Market by Geography
Executive Summary - Chart on Market Segmentation by Component
Executive Summary - Chart on Market Segmentation by Deployment
Executive Summary - Chart on Market Segmentation by Technology
Executive Summary - Chart on Incremental Growth
Executive Summary - Data Table on Incremental Growth
Executive Summary - Chart on Company Market Positioning

2. Technavio Analysis

2.1 Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

2.2 Criticality of inputs and Factors of differentiation

Chart on Overview on criticality of inputs and factors of differentiation

2.3 Factors of disruption

Chart on Overview on factors of disruption

2.4 Impact of drivers and challenges

Chart on Impact of drivers and challenges in 2025 and 2030

3. Market Landscape

3.1 Market ecosystem

Chart on Parent Market
Data Table on - Parent Market

3.2 Market characteristics

Chart on Market characteristics analysis

3.3 Value chain analysis

Chart on Value chain analysis

4. Market Sizing

4.1 Market definition

Data Table on Offerings of companies included in the market definition

4.2 Market segment analysis

Market segments

4.3 Market size 2025

4.4 Market outlook: Forecast for 2025-2030

Chart on Global - Market size and forecast 2025-2030 ($ million)
Data Table on Global - Market size and forecast 2025-2030 ($ million)
Chart on Global Market: Year-over-year growth 2025-2030 (%)
Data Table on Global Market: Year-over-year growth 2025-2030 (%)

5. Historic Market Size

5.1 Global AI Orchestration Market 2020 - 2024

Historic Market Size - Data Table on Global AI Orchestration Market 2020 - 2024 ($ million)

5.2 Component segment analysis 2020 - 2024

Historic Market Size - Component Segment 2020 - 2024 ($ million)

5.3 Deployment segment analysis 2020 - 2024

Historic Market Size - Deployment Segment 2020 - 2024 ($ million)

5.4 Technology segment analysis 2020 - 2024

Historic Market Size - Technology Segment 2020 - 2024 ($ million)

5.5 Geography segment analysis 2020 - 2024

Historic Market Size - Geography Segment 2020 - 2024 ($ million)

5.6 Country segment analysis 2020 - 2024

Historic Market Size - Country Segment 2020 - 2024 ($ million)

6. Qualitative Analysis

6.1 Impact of AI on Global AI Orchestration Market

6.2 Impact of Geopolitical Conflicts on Global AI Orchestration Market

7. Five Forces Analysis

7.1 Five forces summary

Five forces analysis - Comparison between 2025 and 2030

7.2 Bargaining power of buyers

Bargaining power of buyers - Impact of key factors 2025 and 2030

7.3 Bargaining power of suppliers

Bargaining power of suppliers - Impact of key factors in 2025 and 2030

7.4 Threat of new entrants

Threat of new entrants - Impact of key factors in 2025 and 2030

7.5 Threat of substitutes

Threat of substitutes - Impact of key factors in 2025 and 2030

7.6 Threat of rivalry

Threat of rivalry - Impact of key factors in 2025 and 2030

7.7 Market condition

Chart on Market condition - Five forces 2025 and 2030

8. Market Segmentation by Component

8.1 Market segments

Chart on Component - Market share 2025-2030 (%)
Data Table on Component - Market share 2025-2030 (%)

8.2 Comparison by Component

Chart on Comparison by Component
Data Table on Comparison by Component

8.3 Solutions - Market size and forecast 2025-2030

Chart on Solutions - Market size and forecast 2025-2030 ($ million)
Data Table on Solutions - Market size and forecast 2025-2030 ($ million)
Chart on Solutions - Year-over-year growth 2025-2030 (%)
Data Table on Solutions - Year-over-year growth 2025-2030 (%)

8.4 Services - Market size and forecast 2025-2030

Chart on Services - Market size and forecast 2025-2030 ($ million)
Data Table on Services - Market size and forecast 2025-2030 ($ million)
Chart on Services - Year-over-year growth 2025-2030 (%)
Data Table on Services - Year-over-year growth 2025-2030 (%)

8.5 Market opportunity by Component

Market opportunity by Component ($ million)
Data Table on Market opportunity by Component ($ million)

9. Market Segmentation by Deployment

9.1 Market segments

Chart on Deployment - Market share 2025-2030 (%)
Data Table on Deployment - Market share 2025-2030 (%)

9.2 Comparison by Deployment

Chart on Comparison by Deployment
Data Table on Comparison by Deployment

9.3 On-premises - Market size and forecast 2025-2030

Chart on On-premises - Market size and forecast 2025-2030 ($ million)
Data Table on On-premises - Market size and forecast 2025-2030 ($ million)
Chart on On-premises - Year-over-year growth 2025-2030 (%)
Data Table on On-premises - Year-over-year growth 2025-2030 (%)

9.4 Cloud - Market size and forecast 2025-2030

Chart on Cloud - Market size and forecast 2025-2030 ($ million)
Data Table on Cloud - Market size and forecast 2025-2030 ($ million)
Chart on Cloud - Year-over-year growth 2025-2030 (%)
Data Table on Cloud - Year-over-year growth 2025-2030 (%)

9.5 Hybrid - Market size and forecast 2025-2030

Chart on Hybrid - Market size and forecast 2025-2030 ($ million)
Data Table on Hybrid - Market size and forecast 2025-2030 ($ million)
Chart on Hybrid - Year-over-year growth 2025-2030 (%)
Data Table on Hybrid - Year-over-year growth 2025-2030 (%)

9.6 Market opportunity by Deployment

Market opportunity by Deployment ($ million)
Data Table on Market opportunity by Deployment ($ million)

10. Market Segmentation by Technology

10.1 Market segments

Chart on Technology - Market share 2025-2030 (%)
Data Table on Technology - Market share 2025-2030 (%)

10.2 Comparison by Technology

Chart on Comparison by Technology
Data Table on Comparison by Technology

10.3 Data orchestration - Market size and forecast 2025-2030

Chart on Data orchestration - Market size and forecast 2025-2030 ($ million)
Data Table on Data orchestration - Market size and forecast 2025-2030 ($ million)
Chart on Data orchestration - Year-over-year growth 2025-2030 (%)
Data Table on Data orchestration - Year-over-year growth 2025-2030 (%)

10.4 Model orchestration - Market size and forecast 2025-2030

Chart on Model orchestration - Market size and forecast 2025-2030 ($ million)
Data Table on Model orchestration - Market size and forecast 2025-2030 ($ million)
Chart on Model orchestration - Year-over-year growth 2025-2030 (%)
Data Table on Model orchestration - Year-over-year growth 2025-2030 (%)

10.5 Generative AI orchestration - Market size and forecast 2025-2030

Chart on Generative AI orchestration - Market size and forecast 2025-2030 ($ million)
Data Table on Generative AI orchestration - Market size and forecast 2025-2030 ($ million)
Chart on Generative AI orchestration - Year-over-year growth 2025-2030 (%)
Data Table on Generative AI orchestration - Year-over-year growth 2025-2030 (%)

10.6 Infrastructure orchestration - Market size and forecast 2025-2030

Chart on Infrastructure orchestration - Market size and forecast 2025-2030 ($ million)
Data Table on Infrastructure orchestration - Market size and forecast 2025-2030 ($ million)
Chart on Infrastructure orchestration - Year-over-year growth 2025-2030 (%)
Data Table on Infrastructure orchestration - Year-over-year growth 2025-2030 (%)

10.7 Multi agent orchestration - Market size and forecast 2025-2030

Chart on Multi agent orchestration - Market size and forecast 2025-2030 ($ million)
Data Table on Multi agent orchestration - Market size and forecast 2025-2030 ($ million)
Chart on Multi agent orchestration - Year-over-year growth 2025-2030 (%)
Data Table on Multi agent orchestration - Year-over-year growth 2025-2030 (%)

10.8 Market opportunity by Technology

Market opportunity by Technology ($ million)
Data Table on Market opportunity by Technology ($ million)

11. Customer Landscape

11.1 Customer landscape overview

Analysis of price sensitivity, lifecycle, customer purchase basket, adoption rates, and purchase criteria

12. Geographic Landscape

12.1 Geographic segmentation

Chart on Market share by geography 2025-2030 (%)
Data Table on Market share by geography 2025-2030 (%)

12.2 Geographic comparison

Chart on Geographic comparison
Data Table on Geographic comparison

12.3 North America - Market size and forecast 2025-2030

Chart on North America - Market size and forecast 2025-2030 ($ million)
Data Table on North America - Market size and forecast 2025-2030 ($ million)
Chart on North America - Year-over-year growth 2025-2030 (%)
Data Table on North America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - North America
Data Table on Regional Comparison - North America

12.3.1 US - Market size and forecast 2025-2030

Chart on US - Market size and forecast 2025-2030 ($ million)
Data Table on US - Market size and forecast 2025-2030 ($ million)
Chart on US - Year-over-year growth 2025-2030 (%)
Data Table on US - Year-over-year growth 2025-2030 (%)

12.3.2 Canada - Market size and forecast 2025-2030

Chart on Canada - Market size and forecast 2025-2030 ($ million)
Data Table on Canada - Market size and forecast 2025-2030 ($ million)
Chart on Canada - Year-over-year growth 2025-2030 (%)
Data Table on Canada - Year-over-year growth 2025-2030 (%)

12.3.3 Mexico - Market size and forecast 2025-2030

Chart on Mexico - Market size and forecast 2025-2030 ($ million)
Data Table on Mexico - Market size and forecast 2025-2030 ($ million)
Chart on Mexico - Year-over-year growth 2025-2030 (%)
Data Table on Mexico - Year-over-year growth 2025-2030 (%)

12.4 APAC - Market size and forecast 2025-2030

Chart on APAC - Market size and forecast 2025-2030 ($ million)
Data Table on APAC - Market size and forecast 2025-2030 ($ million)
Chart on APAC - Year-over-year growth 2025-2030 (%)
Data Table on APAC - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - APAC
Data Table on Regional Comparison - APAC

12.4.1 China - Market size and forecast 2025-2030

Chart on China - Market size and forecast 2025-2030 ($ million)
Data Table on China - Market size and forecast 2025-2030 ($ million)
Chart on China - Year-over-year growth 2025-2030 (%)
Data Table on China - Year-over-year growth 2025-2030 (%)

12.4.2 Japan - Market size and forecast 2025-2030

Chart on Japan - Market size and forecast 2025-2030 ($ million)
Data Table on Japan - Market size and forecast 2025-2030 ($ million)
Chart on Japan - Year-over-year growth 2025-2030 (%)
Data Table on Japan - Year-over-year growth 2025-2030 (%)

12.4.3 India - Market size and forecast 2025-2030

Chart on India - Market size and forecast 2025-2030 ($ million)
Data Table on India - Market size and forecast 2025-2030 ($ million)
Chart on India - Year-over-year growth 2025-2030 (%)
Data Table on India - Year-over-year growth 2025-2030 (%)

12.4.4 South Korea - Market size and forecast 2025-2030

Chart on South Korea - Market size and forecast 2025-2030 ($ million)
Data Table on South Korea - Market size and forecast 2025-2030 ($ million)
Chart on South Korea - Year-over-year growth 2025-2030 (%)
Data Table on South Korea - Year-over-year growth 2025-2030 (%)

12.4.5 Australia - Market size and forecast 2025-2030

Chart on Australia - Market size and forecast 2025-2030 ($ million)
Data Table on Australia - Market size and forecast 2025-2030 ($ million)
Chart on Australia - Year-over-year growth 2025-2030 (%)
Data Table on Australia - Year-over-year growth 2025-2030 (%)

12.4.6 Indonesia - Market size and forecast 2025-2030

Chart on Indonesia - Market size and forecast 2025-2030 ($ million)
Data Table on Indonesia - Market size and forecast 2025-2030 ($ million)
Chart on Indonesia - Year-over-year growth 2025-2030 (%)
Data Table on Indonesia - Year-over-year growth 2025-2030 (%)

12.5 Europe - Market size and forecast 2025-2030

Chart on Europe - Market size and forecast 2025-2030 ($ million)
Data Table on Europe - Market size and forecast 2025-2030 ($ million)
Chart on Europe - Year-over-year growth 2025-2030 (%)
Data Table on Europe - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Europe
Data Table on Regional Comparison - Europe

12.5.1 Germany - Market size and forecast 2025-2030

Chart on Germany - Market size and forecast 2025-2030 ($ million)
Data Table on Germany - Market size and forecast 2025-2030 ($ million)
Chart on Germany - Year-over-year growth 2025-2030 (%)
Data Table on Germany - Year-over-year growth 2025-2030 (%)

12.5.2 UK - Market size and forecast 2025-2030

Chart on UK - Market size and forecast 2025-2030 ($ million)
Data Table on UK - Market size and forecast 2025-2030 ($ million)
Chart on UK - Year-over-year growth 2025-2030 (%)
Data Table on UK - Year-over-year growth 2025-2030 (%)

12.5.3 France - Market size and forecast 2025-2030

Chart on France - Market size and forecast 2025-2030 ($ million)
Data Table on France - Market size and forecast 2025-2030 ($ million)
Chart on France - Year-over-year growth 2025-2030 (%)
Data Table on France - Year-over-year growth 2025-2030 (%)

12.5.4 Italy - Market size and forecast 2025-2030

Chart on Italy - Market size and forecast 2025-2030 ($ million)
Data Table on Italy - Market size and forecast 2025-2030 ($ million)
Chart on Italy - Year-over-year growth 2025-2030 (%)
Data Table on Italy - Year-over-year growth 2025-2030 (%)

12.5.5 Spain - Market size and forecast 2025-2030

Chart on Spain - Market size and forecast 2025-2030 ($ million)
Data Table on Spain - Market size and forecast 2025-2030 ($ million)
Chart on Spain - Year-over-year growth 2025-2030 (%)
Data Table on Spain - Year-over-year growth 2025-2030 (%)

12.5.6 The Netherlands - Market size and forecast 2025-2030

Chart on The Netherlands - Market size and forecast 2025-2030 ($ million)
Data Table on The Netherlands - Market size and forecast 2025-2030 ($ million)
Chart on The Netherlands - Year-over-year growth 2025-2030 (%)
Data Table on The Netherlands - Year-over-year growth 2025-2030 (%)

12.6 Middle East and Africa - Market size and forecast 2025-2030

Chart on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Data Table on Middle East and Africa - Market size and forecast 2025-2030 ($ million)
Chart on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Data Table on Middle East and Africa - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - Middle East and Africa
Data Table on Regional Comparison - Middle East and Africa

12.6.1 Saudi Arabia - Market size and forecast 2025-2030

Chart on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Data Table on Saudi Arabia - Market size and forecast 2025-2030 ($ million)
Chart on Saudi Arabia - Year-over-year growth 2025-2030 (%)
Data Table on Saudi Arabia - Year-over-year growth 2025-2030 (%)

12.6.2 UAE - Market size and forecast 2025-2030

Chart on UAE - Market size and forecast 2025-2030 ($ million)
Data Table on UAE - Market size and forecast 2025-2030 ($ million)
Chart on UAE - Year-over-year growth 2025-2030 (%)
Data Table on UAE - Year-over-year growth 2025-2030 (%)

12.6.3 South Africa - Market size and forecast 2025-2030

Chart on South Africa - Market size and forecast 2025-2030 ($ million)
Data Table on South Africa - Market size and forecast 2025-2030 ($ million)
Chart on South Africa - Year-over-year growth 2025-2030 (%)
Data Table on South Africa - Year-over-year growth 2025-2030 (%)

12.6.4 Israel - Market size and forecast 2025-2030

Chart on Israel - Market size and forecast 2025-2030 ($ million)
Data Table on Israel - Market size and forecast 2025-2030 ($ million)
Chart on Israel - Year-over-year growth 2025-2030 (%)
Data Table on Israel - Year-over-year growth 2025-2030 (%)

12.6.5 Turkey - Market size and forecast 2025-2030

Chart on Turkey - Market size and forecast 2025-2030 ($ million)
Data Table on Turkey - Market size and forecast 2025-2030 ($ million)
Chart on Turkey - Year-over-year growth 2025-2030 (%)
Data Table on Turkey - Year-over-year growth 2025-2030 (%)

12.7 South America - Market size and forecast 2025-2030

Chart on South America - Market size and forecast 2025-2030 ($ million)
Data Table on South America - Market size and forecast 2025-2030 ($ million)
Chart on South America - Year-over-year growth 2025-2030 (%)
Data Table on South America - Year-over-year growth 2025-2030 (%)
Chart on Regional Comparison - South America
Data Table on Regional Comparison - South America

12.7.1 Brazil - Market size and forecast 2025-2030

Chart on Brazil - Market size and forecast 2025-2030 ($ million)
Data Table on Brazil - Market size and forecast 2025-2030 ($ million)
Chart on Brazil - Year-over-year growth 2025-2030 (%)
Data Table on Brazil - Year-over-year growth 2025-2030 (%)

12.7.2 Argentina - Market size and forecast 2025-2030

Chart on Argentina - Market size and forecast 2025-2030 ($ million)
Data Table on Argentina - Market size and forecast 2025-2030 ($ million)
Chart on Argentina - Year-over-year growth 2025-2030 (%)
Data Table on Argentina - Year-over-year growth 2025-2030 (%)

12.7.3 Chile - Market size and forecast 2025-2030

Chart on Chile - Market size and forecast 2025-2030 ($ million)
Data Table on Chile - Market size and forecast 2025-2030 ($ million)
Chart on Chile - Year-over-year growth 2025-2030 (%)
Data Table on Chile - Year-over-year growth 2025-2030 (%)

12.8 Market opportunity by geography

Market opportunity by geography ($ million)
Data Tables on Market opportunity by geography ($ million)

13. Drivers, Challenges, and Opportunity

13.1 Market drivers

Autonomous multi-agent architectures and distributed workflows
Complexity of multi-cloud environments and heterogeneous data silos
Regulatory compliance and model governance

13.2 Market challenges

Architectural fragmentation and legacy enterprise system
Computational costs and infrastructure bottlenecks
Governance, security, and agent reliability challenges

13.3 Impact of drivers and challenges

Impact of drivers and challenges in 2025 and 2030

13.4 Market opportunities

Cross-channel personalization and unified contextual intelligence
Specialized vertical AI tools and unified operational frameworks
Open inter-agent protocols and dynamic routing standardization

14. Competitive Landscape

14.1 Overview

14.2

Overview on criticality of inputs and factors of differentiation

14.3 Landscape disruption

Overview on factors of disruption

14.4 Industry risks

Impact of key risks on business

15. Competitive Analysis

15.1 Companies profiled

Companies covered

15.2 Company ranking index

15.3 Market positioning of companies

Matrix on companies position and classification

15.4 Amazon Web Services Inc.

Amazon Web Services Inc. - Overview
Amazon Web Services Inc. - Product / Service
Amazon Web Services Inc. - Key offerings
SWOT

15.5 Appian Corp.

Appian Corp. - Overview
Appian Corp. - Business segments
Appian Corp. - Key offerings
Appian Corp. - Segment focus
SWOT

15.6 Automation Anywhere Inc.

Automation Anywhere Inc. - Overview
Automation Anywhere Inc. - Product / Service
Automation Anywhere Inc. - Key offerings
SWOT

15.7 DataRobot Inc.

DataRobot Inc. - Overview
DataRobot Inc. - Product / Service
DataRobot Inc. - Key offerings
SWOT

15.8 Google LLC

Google LLC - Overview
Google LLC - Product / Service
Google LLC - Key news
Google LLC - Key offerings
SWOT

15.9 IBM Corp.

IBM Corp. - Overview
IBM Corp. - Business segments
IBM Corp. - Key news
IBM Corp. - Key offerings
IBM Corp. - Segment focus
SWOT

15.10 Microsoft Corp.

Microsoft Corp. - Overview
Microsoft Corp. - Business segments
Microsoft Corp. - Key news
Microsoft Corp. - Key offerings
Microsoft Corp. - Segment focus
SWOT

15.11 NVIDIA Corp.

NVIDIA Corp. - Overview
NVIDIA Corp. - Business segments
NVIDIA Corp. - Key news
NVIDIA Corp. - Key offerings
NVIDIA Corp. - Segment focus
SWOT

15.12 Oracle Corp.

Oracle Corp. - Overview
Oracle Corp. - Business segments
Oracle Corp. - Key news
Oracle Corp. - Key offerings
Oracle Corp. - Segment focus
SWOT

15.13 Pegasystems Inc.

Pegasystems Inc. - Overview
Pegasystems Inc. - Business segments
Pegasystems Inc. - Key offerings
Pegasystems Inc. - Segment focus
SWOT

15.14 Salesforce Inc.

Salesforce Inc. - Overview
Salesforce Inc. - Business segments
Salesforce Inc. - Key news
Salesforce Inc. - Key offerings
Salesforce Inc. - Segment focus
SWOT

15.15 SAP SE

SAP SE - Overview
SAP SE - Business segments
SAP SE - Key news
SAP SE - Key offerings
SAP SE - Segment focus
SWOT

15.16 ServiceNow Inc.

ServiceNow Inc. - Overview
ServiceNow Inc. - Product / Service
ServiceNow Inc. - Key news
ServiceNow Inc. - Key offerings
SWOT

15.17 Snowflake Inc.

Snowflake Inc. - Overview
Snowflake Inc. - Business segments
Snowflake Inc. - Key news
Snowflake Inc. - Key offerings
Snowflake Inc. - Segment focus
SWOT

15.18 UiPath Inc.

UiPath Inc. - Overview
UiPath Inc. - Product / Service
UiPath Inc. - Key news
UiPath Inc. - Key offerings
SWOT

16. Appendix

16.1 Scope of the report

Market definition
Objectives
Notes and caveats

16.2 Inclusions and exclusions checklist

Inclusions checklist
Exclusions checklist

16.3 Currency conversion rates for US$

16.4 Research methodology

16.5 Data procurement

Information sources

16.6 Data validation

16.7 Validation techniques employed for market sizing

16.8 Data synthesis

16.9 360 degree market analysis

16.10 List of abbreviations

Research Methodology

Technavio presents a detailed picture of the market by way of study, synthesis, and summation of data from multiple sources. The analysts have presented the various facets of the market with a particular focus on identifying the key industry influencers. The data thus presented is comprehensive, reliable, and the result of extensive research, both primary and secondary.

INFORMATION SOURCES

Primary sources

  • Manufacturers and suppliers
  • Channel partners
  • Industry experts
  • Strategic decision makers

Secondary sources

  • Industry journals and periodicals
  • Government data
  • Financial reports of key industry players
  • Historical data
  • Press releases

DATA ANALYSIS

Data Synthesis

  • Collation of data
  • Estimation of key figures
  • Analysis of derived insights

Data Validation

  • Triangulation with data models
  • Reference against proprietary databases
  • Corroboration with industry experts

REPORT WRITING

Qualitative

  • Market drivers
  • Market challenges
  • Market trends
  • Five forces analysis

Quantitative

  • Market size and forecast
  • Market segmentation
  • Geographical insights
  • Competitive landscape

Interested in this report?

Get your sample now to see our research methodology and insights!

Download Now

Frequently Asked Questions

Ai Orchestration market growth will increase by USD 18133.8 million during 2026-2030.

The Ai Orchestration market is expected to grow at a CAGR of 25.2% during 2026-2030.

Ai Orchestration market is segmented by Component (Solutions, Services) Deployment (On-premises, Cloud, Hybrid) Technology (Data orchestration, Model orchestration, Generative AI orchestration, Infrastructure orchestration, Multi agent orchestration)

Amazon Web Services Inc., Appian Corp., Automation Anywhere Inc., Camunda Services GmbH, CrewAI, DataRobot Inc., Google LLC, IBM Corp., Kore.ai Inc., LangChain Inc., LlamaIndex Inc., Microsoft Corp., n8n GmbH, NVIDIA Corp., OpenAI, Oracle Corp., Pegasystems Inc., Salesforce Inc., SAP SE, ServiceNow Inc., Snowflake Inc., TrueFoundry Inc., UiPath Inc. are a few of the key vendors in the Ai Orchestration market.

North America will register the highest growth rate of 41% among the other regions. Therefore, the Ai Orchestration market in North America is expected to garner significant business opportunities for the vendors during the forecast period.

US, Canada, Mexico, China, Japan, India, South Korea, Australia, Indonesia, Germany, UK, France, Italy, Spain, The Netherlands, Saudi Arabia, UAE, South Africa, Israel, Turkey, Brazil, Argentina, Chile

  • Autonomous multi-agent architectures and distributed workflows is the driving factor this market.

The Ai Orchestration market vendors should focus on grabbing business opportunities from the Component segment as it accounted for the largest market share in the base year.
RIA - Research AI Assistant
Ask RIA